
Introduction
If cash feels tight, a clear sixty-day plan restores calm and control.
This short-horizon approach helps you prioritize spending, protect essentials, and reduce decision fatigue.
Small, concrete choices now can prevent larger disruptions later and keep momentum.
Use this guide to map priorities, sequence payments, and rebuild breathing room quickly.
Set Clear Priorities
Start by listing essential expenses for the next sixty days: housing, food, utilities, transportation, and any high-priority obligations. Assign each item a priority level and a minimum required amount to cover. When income is limited, fund the highest priorities first and reduce or pause nonessentials to stretch available cash. Clarity on priorities simplifies trade-offs and prevents overspending when decisions feel urgent.
Keep this list visible and update it if circumstances change. Treat it as a working roadmap rather than a rigid rule.
Build a Focused Short-Term Buffer
Aim to create a compact buffer that covers immediate timing gaps rather than a full emergency fund. Target an amount that covers essential costs for two to four pay periods depending on your income cadence. Use temporary reallocations, small transfers, or automatic rounding-up to accelerate the build without derailing basic needs. The objective is quick liquidity and predictable coverage for the near term.
Even modest cushions reduce stress and overdraft risk. Replenish it each month as stability improves.
Sequence Payments and Income
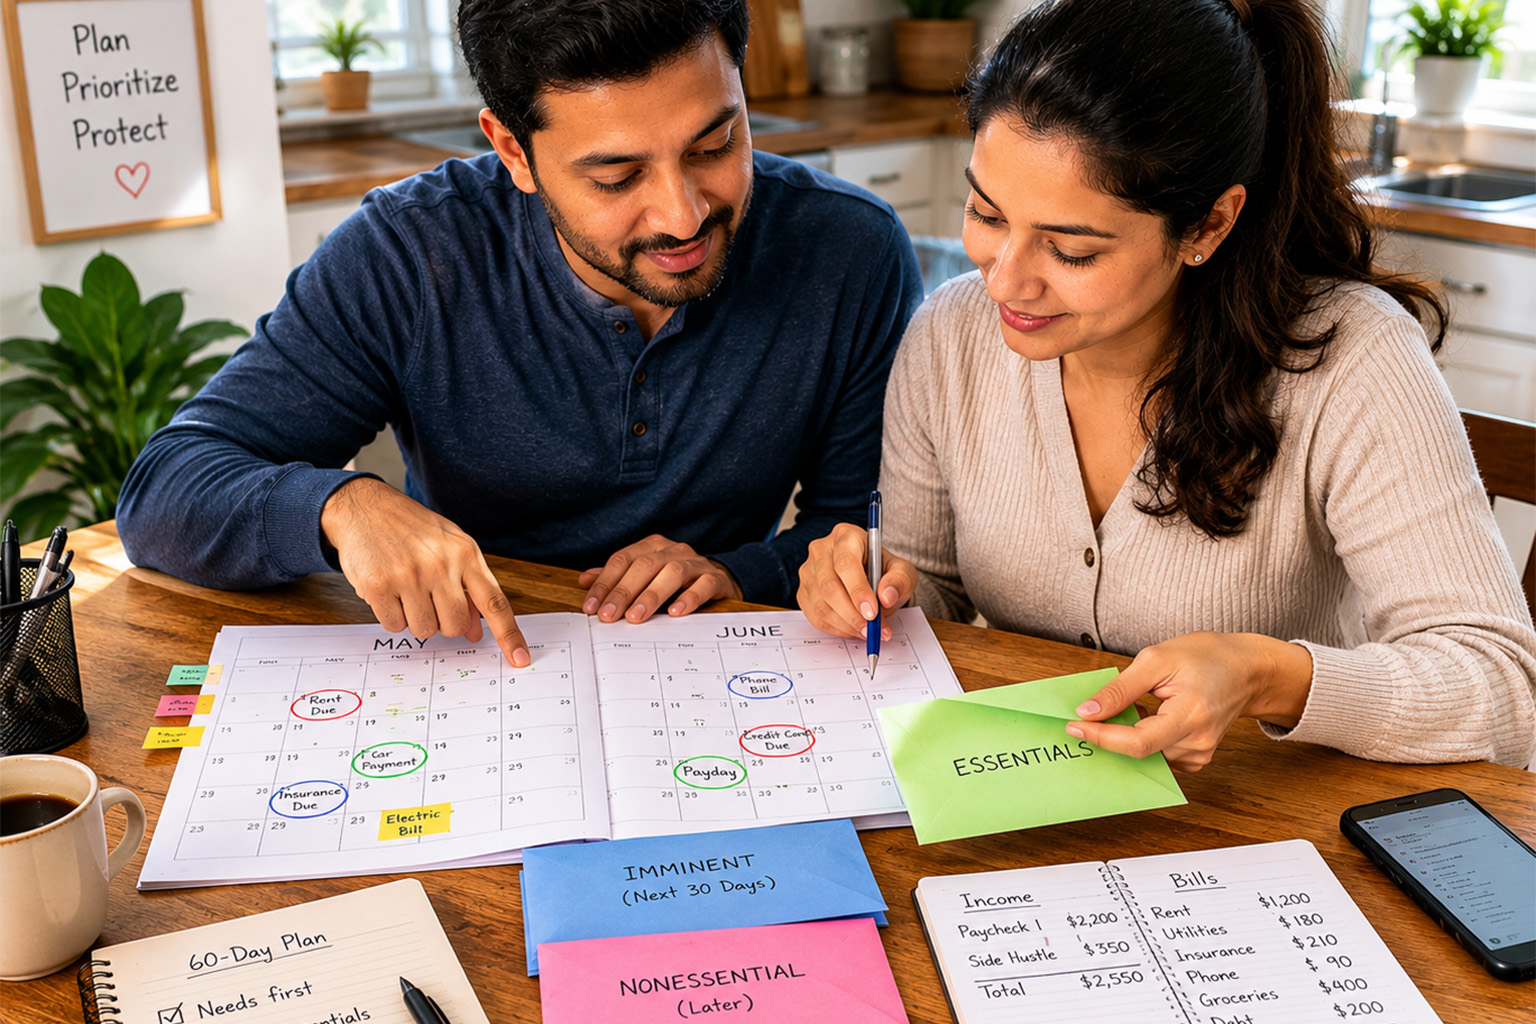
Map upcoming bills and expected income over the next sixty days to identify potential shortfalls and overlaps. Prioritize due dates that affect housing, utilities, and transportation, then consider negotiated arrangements for flexible creditors or service providers. When possible, align income timing—ask about advancing payments or splitting invoices to smooth cash flow. Sequencing reduces pressure and can buy time without taking on new debt.
Communicate proactively with service providers when you need adjustments. Small timing shifts often prevent larger problems.
Use Simple Tools to Track Progress
Choose one straightforward method to monitor cash—an app, a spreadsheet, or a dedicated notebook—so you see inflows and outflows at a glance. Update it weekly and mark progress against your sixty-day priorities to stay accountable and spot emerging gaps. Consider lightweight automation for recurring items and alerts for low balances to avoid surprises. Visibility reduces stress and supports better, faster choices.
- Track income timing
- Mark essential payments
- Record discretionary cuts
Keep the system simple to ensure you use it consistently. Adjust rules as you learn what helps most in your situation.
Conclusion
Sixty days is a manageable window to regain control and build momentum.
Prioritize essentials, create a compact buffer, sequence payments, and stay visible.
Repeat the process and you’ll restore breathing room while preserving long-term goals.