
Introduction
Choosing insurance that protects your household without gutting monthly cash flow is a balancing act. Small changes in premiums, deductibles, or limits can either free up budget or leave you exposed when a loss happens. This article outlines a practical approach to evaluate policies through the lens of routine expenses and emergency readiness. Use these steps to align protection with what you can comfortably pay each month.
Begin by separating essential protections from optional extras so your spending targets are clear. A disciplined review keeps surprises out of your budget planning. Focus on the costs that matter most to your household’s stability.
Assess Your Cash-Flow Vulnerabilities
Start by listing recurring obligations that would be hardest to cover if income stopped or an unexpected bill arrived. Typical vulnerabilities include mortgage or rent, car loans used for commuting, and medical or caregiving costs that could spike after an event. Quantify how many months of each expense your emergency savings would cover, and note gaps that insurance might close. This creates a prioritized map of what protection matters most to your monthly budget.
- Mortgage or rent: months of coverage needed to avoid displacement.
- Transport costs: repairs and replacement that keep work access intact.
- Health-related bills: limits that could otherwise drain savings.
With vulnerabilities identified, you can match insurance choices directly to the functions that sustain your household cash flow. That prevents overpaying for low-impact coverages.
Map Policies to Everyday Functions
Think of each policy as a tool that preserves a specific part of your monthly routine rather than as an abstract contract. Auto insurance protects commute and income access; homeowner or renter policies protect shelter and possessions that would otherwise require immediate cash to replace. Disability and life insurance protect income streams and long-term financial obligations. Clarifying what each policy preserves helps you decide where a higher premium is justified.
When a policy doesn’t clearly preserve a monthly function, question whether coverage or a dedicated emergency fund is more cost-effective. This approach refines spending toward the highest impact protections.
Adjust Deductibles, Limits, and Emergency Savings
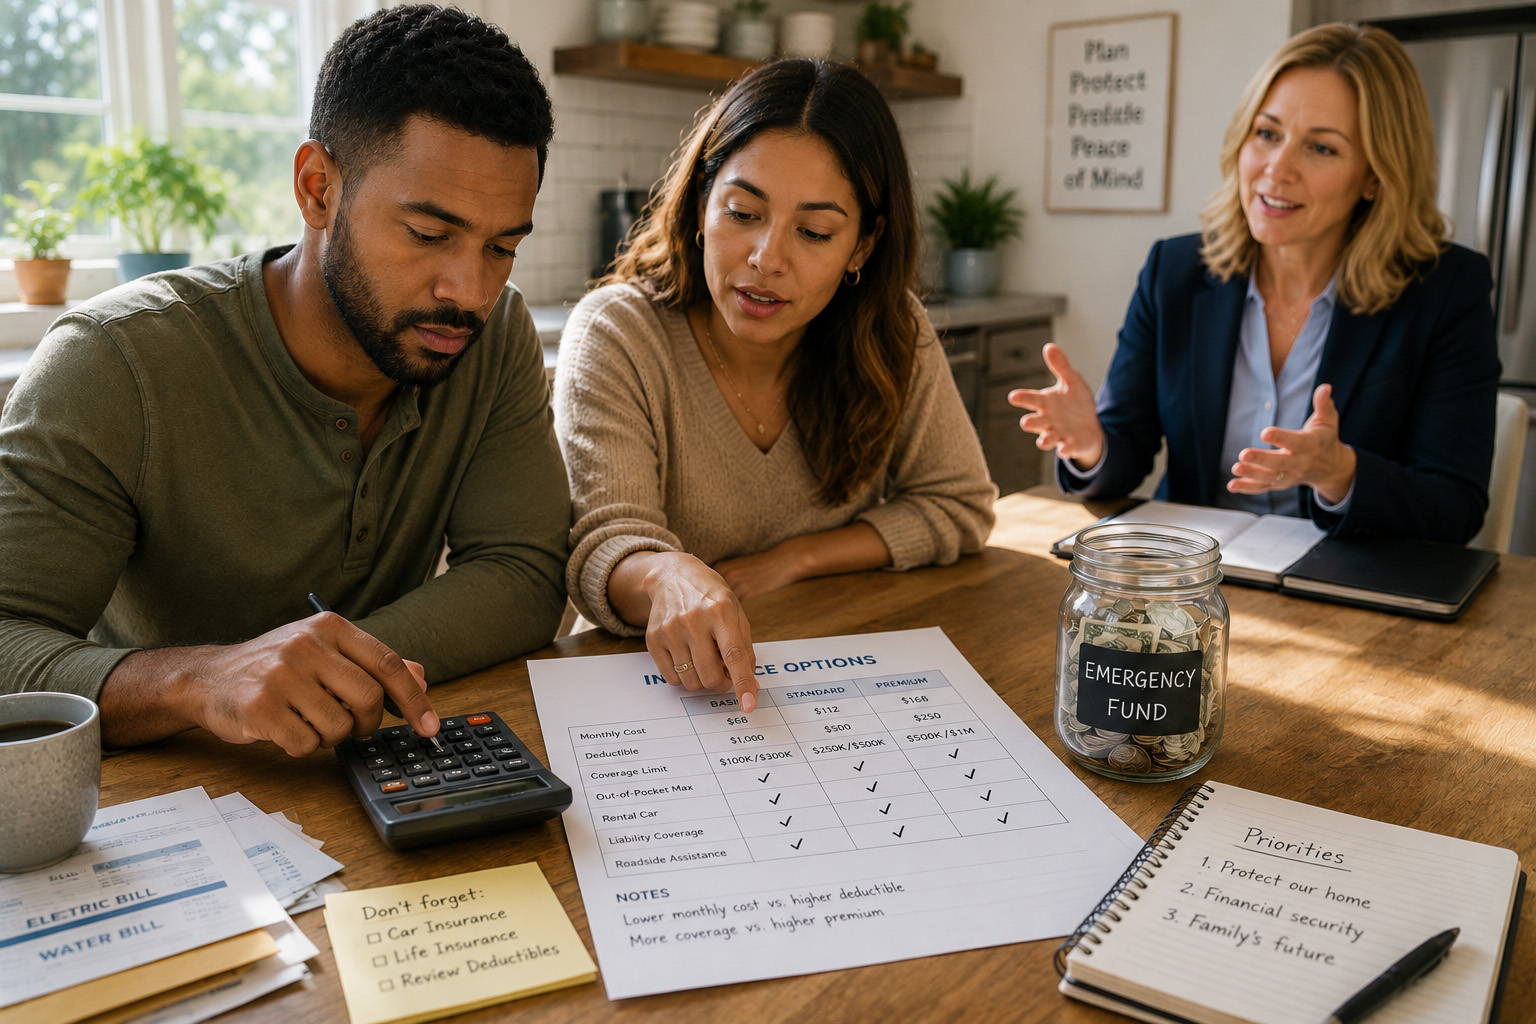
Higher deductibles lower premiums but raise the cash you must have on hand if a claim occurs. Align deductible choices with the size of your emergency fund so a claim won’t force extra debt. Likewise, limits should reflect realistic replacement costs and your tolerance for out-of-pocket recovery. Use small increases in emergency savings to buy down deductible risk where premiums spike sharply.
- Set deductibles you can cover within 30–90 days of an incident.
- Raise limits where replacement cost would otherwise exhaust savings.
Regularly revisit deductibles and savings as income, debts, or household needs change. That keeps both premiums and unexpected bills predictable.
Conclusion
Design insurance to protect the household functions that would otherwise disrupt your monthly budget. Match deductibles and limits to the emergency funds you can maintain without strain. Periodic reviews ensure protection stays aligned with evolving cash-flow realities.