
Introduction
When income varies or bills pile up, a simple weekly routine can reduce stress and improve cash visibility. Spending decisions become clearer when you see obligations grouped and scheduled. This approach focuses on small, repeatable actions rather than dramatic cuts or complicated spreadsheets. Over a few weeks it builds reliable momentum and clearer choices.
Map recurring costs and timing
Start by listing every regular outgoing: rent or mortgage, utilities, subscriptions, loan payments, and essential living costs. Note each due date and the typical amount so you can see clusters and gaps. Identifying when large debits hit will help you avoid surprises and manage cash flow across multiple pay periods. This map becomes the basis for weekly buckets and prioritization.
Keep this list concise and update it once a month. A short, accurate map prevents last-minute scrambling and supports better allocation of available funds.
Group payments into weekly buckets
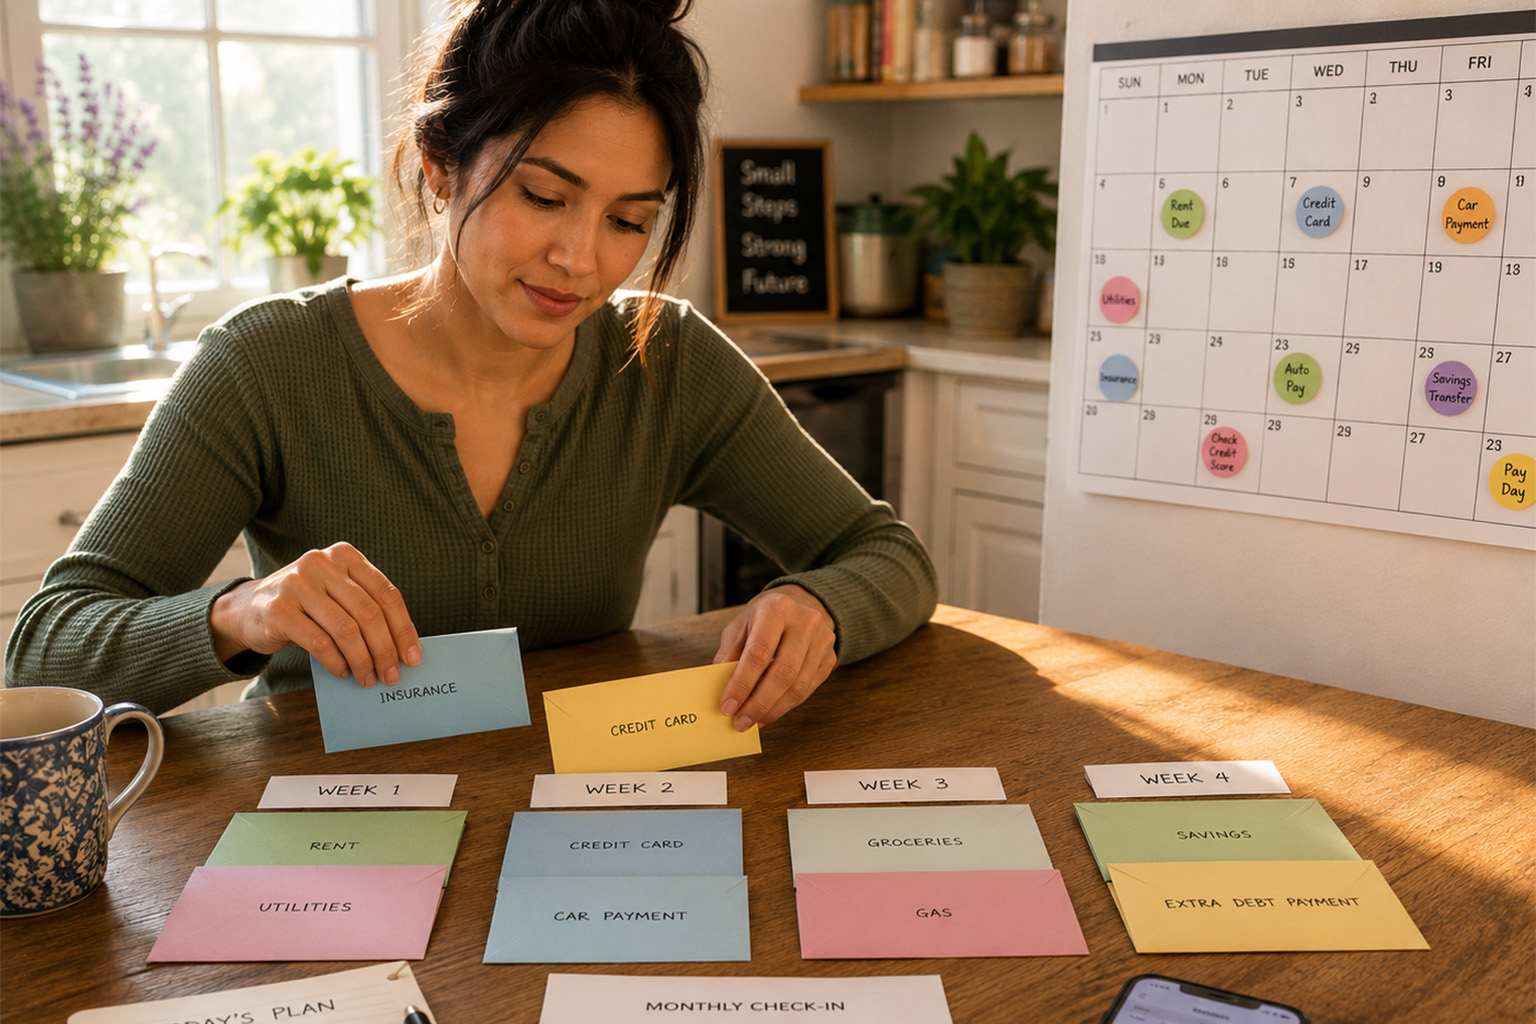
Rather than managing everything as monthly pressure, assign obligations to weekly buckets aligned with your pay cadence. For example, week one covers housing-related costs; week two covers utilities and insurance; week three covers debt payments; week four manages groceries and discretionary items. This transforms daunting totals into manageable weekly targets.
Use a simple calendar or recurring reminders to keep buckets visible. The mental shift to weekly helps reduce impulse spending and clarifies when you need to prioritize.
Build a short weekly ritual
Set a fixed 20–30 minute weekly check-in to move money into buckets, pay scheduled bills, and note upcoming pressures. During this ritual, reconcile balances, adjust transfers for variations, and pause nonessential charges if necessary. Automate transfers when possible, but keep one manual touchpoint so you stay aware of balances. The ritual trains discipline without requiring large time commitments.
Consistency matters more than perfection; a steady weekly habit reduces last-minute decisions and gives you time to respond when income changes.
Adjust priorities and communicate proactively
If a week looks tight, reassign discretionary buckets and focus on essentials: housing, utilities, food, and critical loan payments. Reach out early to creditors or service providers if you anticipate a delay—many accept short-term arrangements when contacted before a missed payment. Consider temporary reductions in subscription spending or pausing nonessential transfers until balances stabilize.
Proactive adjustments preserve relationships and reduce fees. Clear communication and small, planned changes keep your budget resilient while you rebuild cushion.
Conclusion
Adopting a weekly payment routine turns a chaotic month into a series of clear, manageable steps. The process relies on mapping obligations, grouping costs, and a short weekly ritual to stay in control. Over time this simple structure improves cash visibility and reduces stress.