
Introduction
When a paycheck is smaller than expected, deciding what to pay first can feel overwhelming. A clear sequence for limited funds reduces stress and keeps essential services running. This article outlines practical steps to map obligations, prioritize by consequence, and make short-term adjustments. The goal is to stabilize cash flow for the coming pay period without introducing unnecessary risk.
Assess and Map Immediate Obligations
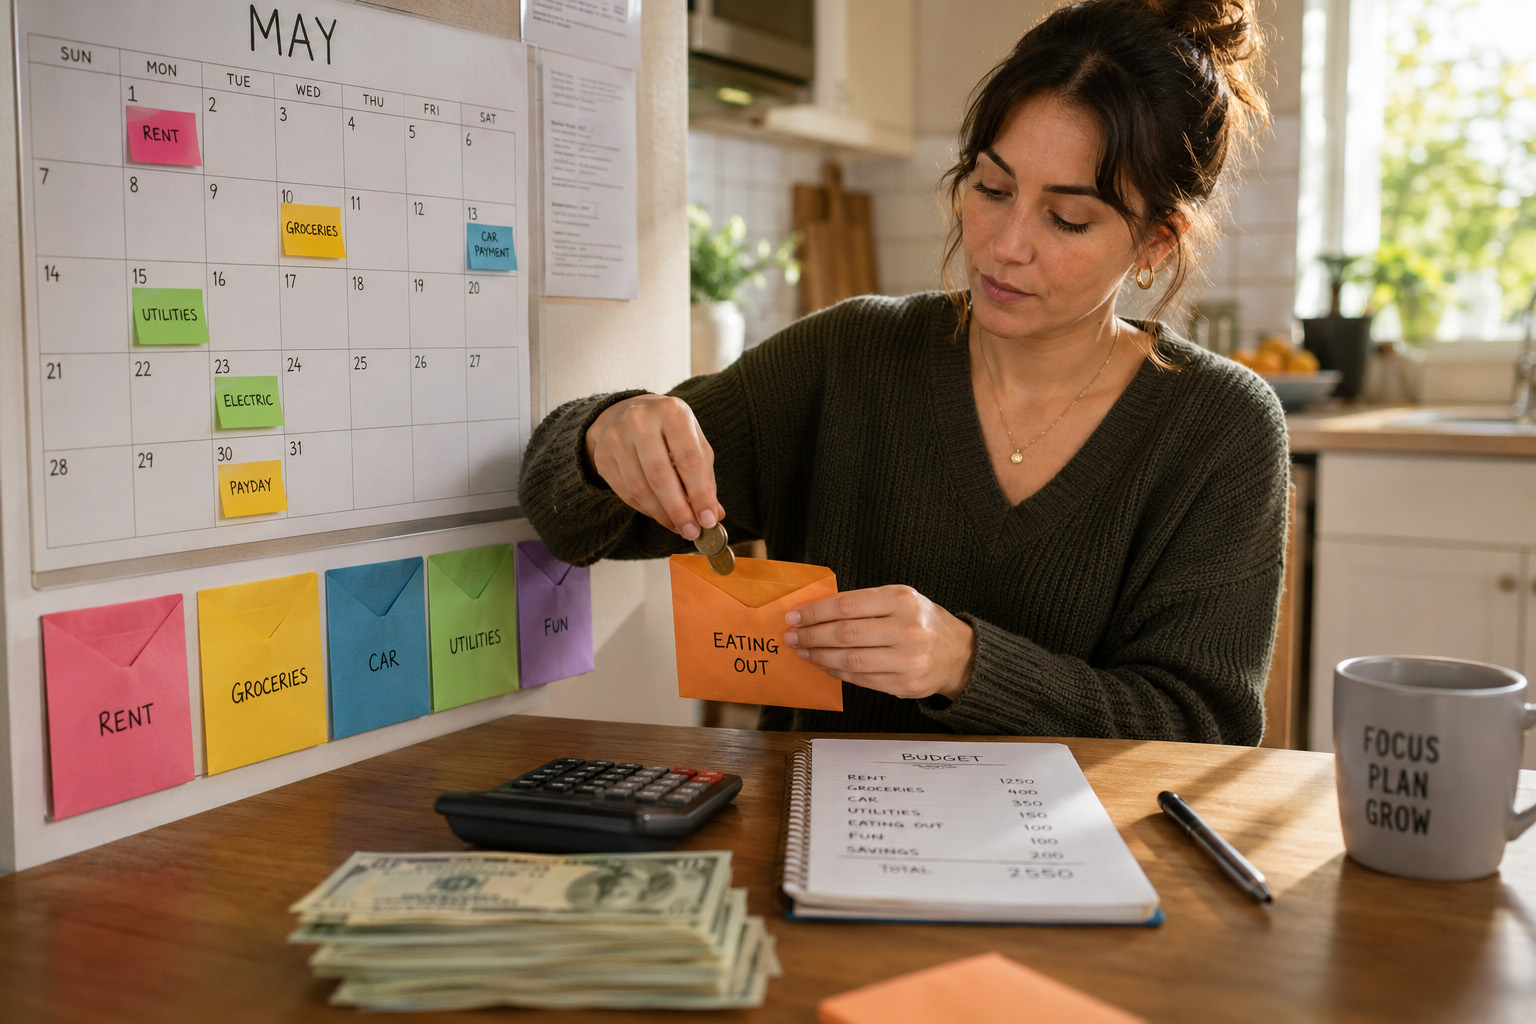
Start by listing all due payments and the dates they fall in the next 30–60 days, including fixed bills, minimum credit obligations, and essentials like groceries and transport. Note which items have late fees or service cutoffs and which vendors offer flexible payment arrangements. Estimating how much each cost would hurt your cash position if delayed helps clarify true priorities. This snapshot turns vague worry into an actionable short list.
With a mapped list you can see where a small adjustment will make the biggest difference. Keep the list visible as you make decisions.
Sequence Payments by Impact and Flexibility
Order payments by immediate consequence first: housing-related charges, utilities that affect basic functioning, and any obligations tied to safety or transportation. Next prioritize debts that generate outsized penalties or credit damage when missed, and then recurring costs that are inconvenient but reversible. Consider which payments can be delayed with low cost or moved to a payment plan. This method shifts focus from arbitrary categories to practical outcomes.
If a choice is close, pick the payment that preserves your ability to earn or reduces future costs. That simple rule helps prevent small shortfalls from becoming bigger problems.
Practical Short-Term Cuts and Communication
Look for temporary reductions you can make quickly: pause subscriptions, switch to lower-cost groceries, and limit discretionary purchases until the cash position improves. Contact service providers and lenders early; many will offer short-term hardship options or fee waivers if you ask before a deadline. Build a minimal buffer by moving any small, unneeded balances into a separate account or envelope to avoid accidental spending. These adjustments are meant to be temporary and reversible once your cash flow steadies.
Small changes plus honest communication buy breathing room and time to recover. Track what you pause so you can restore sensible services after the crunch.
Conclusion
Facing limited funds becomes manageable when you map obligations, sequence by impact, and take short, reversible cuts. Prioritize payments that protect your shelter, income, and credit, and ask for help before deadlines. A calm, organized approach stabilizes your cash flow and preserves options for the next pay period.