
Introduction
Irregular income creates a persistent planning challenge for many households, with timing differences often causing last-minute stress. A small set of repeatable systems reduces that friction and helps money decisions feel less reactive. This article outlines practical steps to map your cash rhythms, set clear priorities, and automate simple rules so your monthly needs are met more consistently. The goal is a lightweight process you can maintain without elaborate tracking or complex forecasts.
Map Your Pay and Expense Rhythms
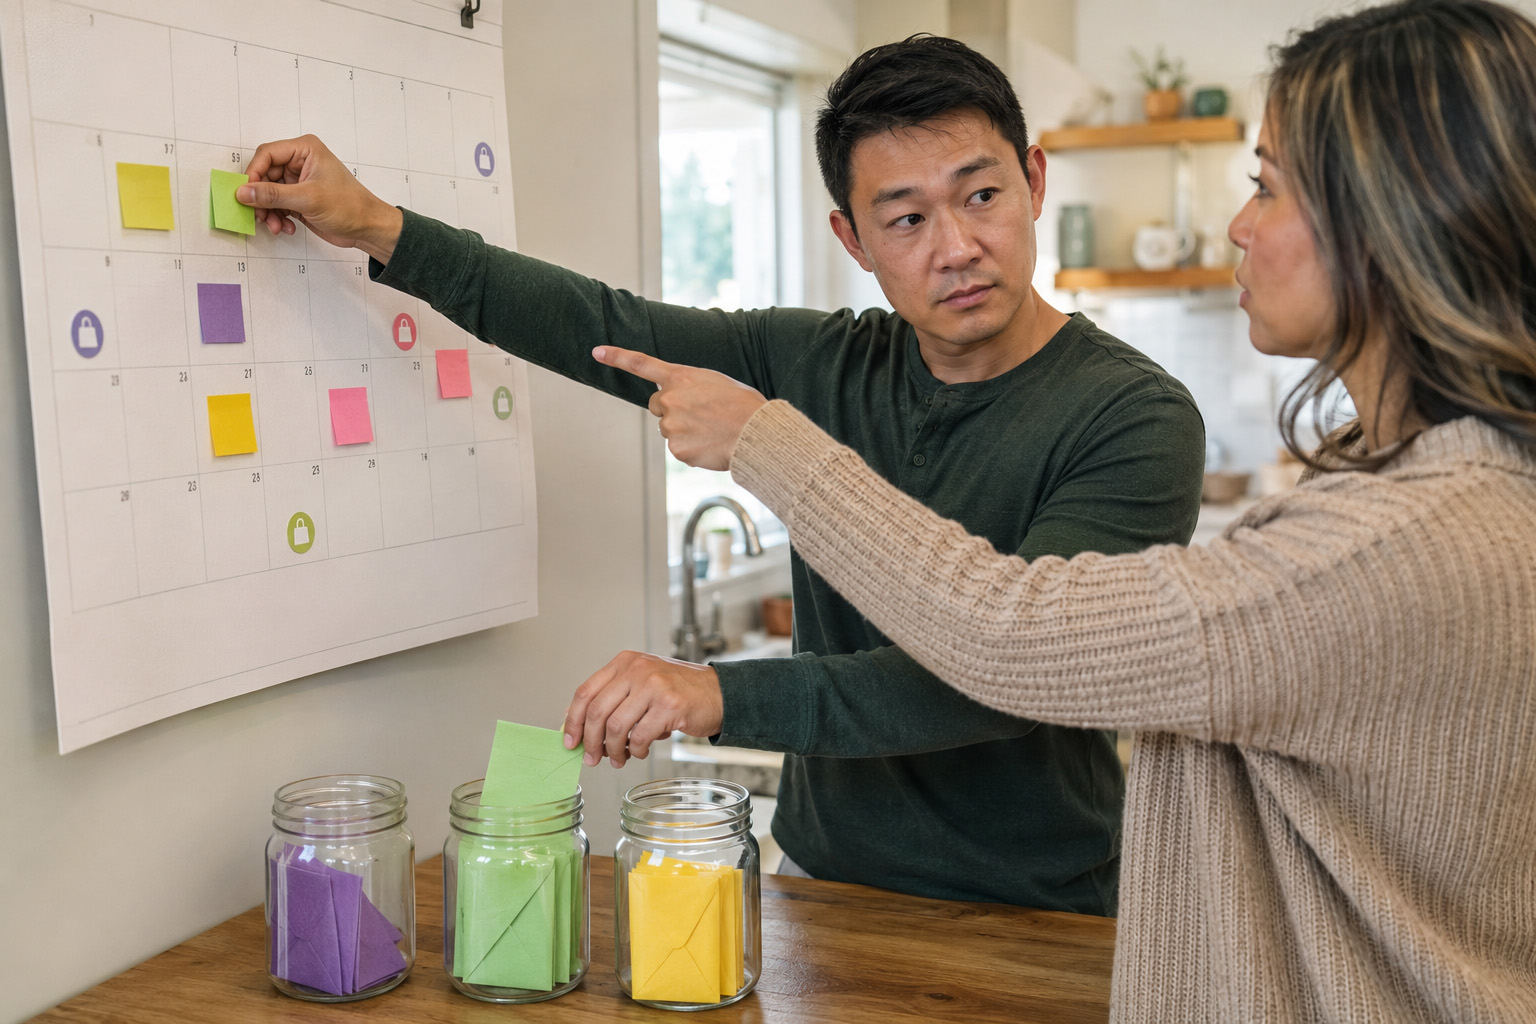
Begin by listing when money typically arrives and when major bills are due; focus on the next two to three months. Knowing which paychecks cover which expenses prevents scrambling and shows where shortfalls are most likely. Charting dates visually—on a calendar or a simple spreadsheet—reveals overlaps and gaps you can address with small timing adjustments. This map becomes the foundation for prioritizing payments and moving funds proactively.
Once you have the map, identify windows where a small reserve would bridge two close dates. Even a modest buffer assigned to a specific pay window reduces stress and avoids costly last-minute solutions. Treat the map as a living tool you revisit monthly.
Create Priority Buckets for Predictable Needs
Next, divide upcoming obligations into priority buckets that reflect necessity, risk, and timing. Buckets clarify what to pay first when cash is limited and make trade-offs explicit instead of emotional. Typical buckets include essentials, timing-sensitive obligations, and flexible spending; labeling these makes decision rules simple during tight periods. The goal is not to eliminate choices but to make them predictable so you act quickly and confidently.
- Essentials: rent/mortgage, utilities, food for household members.
- Timing-sensitive: loan minimums, insurance payments, claims that carry penalties.
- Flexible: subscriptions, nonessential purchases, discretionary transfers.
Using buckets reduces the mental load of day-to-day budgeting and helps you negotiate payment timing with creditors when needed. It also makes it easier to identify where temporary expense reduction will have the most impact.
Automate Small Rules and Review Weekly
Set simple automation rules: a small transfer to a bridge fund on payday, scheduled payments for true essentials, and alerts for upcoming large bills. Automation enforces the plan when attention is limited and prevents one-time errors from cascading into larger problems. Combine automation with a short weekly review to adjust amounts, note income changes, and reassign funds between buckets as needed. That weekly check is low-effort but high-impact for maintaining stability.
When income spikes, direct a portion to the bridge fund rather than immediately increasing spending. When it dips, follow your predetermined priority order so essential obligations remain covered without panic.
Conclusion
Simple mapping, clear priority buckets, and modest automation turn irregular pay into manageable cycles. These systems reduce reactive decisions and create breathing room without heavy tracking. Start with one small rule this week and build from there.