
Introduction
When cash feels tight for the coming month, a compact routine can give you control and reduce stress. Start by mapping income and unavoidable costs, then use simple rules to sequence spending and protect essentials. Small, deliberate actions over thirty days can rebuild breathing room without drastic cuts. This piece outlines a clear monthly routine you can follow whether income is stable or variable.
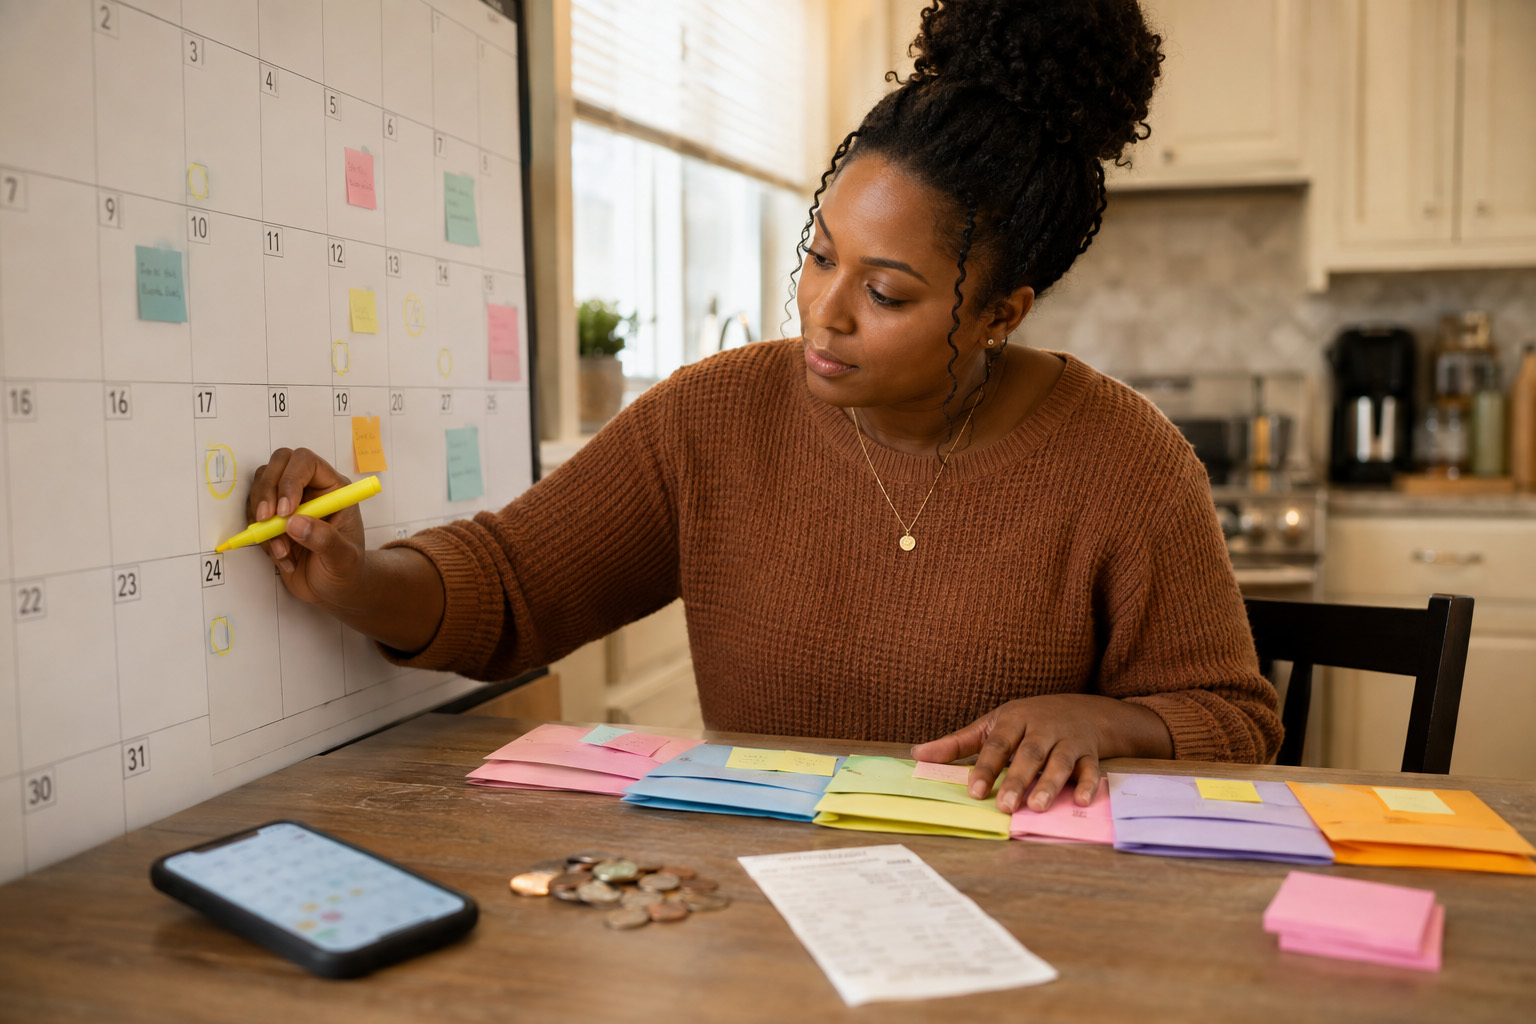
Map the month
Begin by listing every expected inflow and fixed outflow for the next 30 days. Include paydays, recurring bills, subscriptions, and any known one-off expenses so you can see where gaps will appear. Use a single sheet or a dedicated app to keep the view simple and avoid overlooking timing mismatches. Knowing exact dates and amounts is the foundation of any short-term cash plan.
Once those numbers are in place, mark which payments are time-sensitive and which can be shifted. This makes it easier to protect essentials and negotiate where possible.
Prioritize and reorder payments
Classify outgoings into tiers: essentials that avoid immediate harm, negotiables that can be delayed, and flexible items to pause or reduce. Essentials typically include housing, utilities, transportation, and basic food; these should be first in the payment sequence. For negotiables, contact providers proactively to request extensions, short-term plans, or alternative dates. Preparing a clear order removes the guesswork when cash arrives and improves decision speed.
- Tier 1: Shelter, utilities, essential transportation, groceries
- Tier 2: Minimum debt payments, insurance, necessary medical costs
- Tier 3: Subscriptions, discretionary spending, nonessential transfers
With a tiered list you can apply a simple rule: cover Tier 1 fully, satisfy minimums in Tier 2, and pause Tier 3 until stability returns.
Increase short-term cash and monitor
Look for small, fast ways to create extra room: sell or temporarily list unused items, pick up short shifts or gigs, and cut nonessential recurring charges for the month. Even modest inflows can prevent late fees and reduce stress. Use one weekly check-in to update the map, record any changes, and reallocate funds as needed. Regular monitoring helps you respond quickly to surprises without losing control.
- Quick actions: sell an item, delay a subscription, ask for a due-date change
- Weekly check-ins: 15–20 minutes to update and act
These small efforts add up and keep decisions calm and deliberate rather than reactive.
Conclusion
Follow a short, structured routine each month: map, prioritize, act, and monitor. Consistent small steps protect essentials and reduce stress while you rebuild a cushion. Over thirty days this approach creates clarity and momentum toward steadier cash flow.