
Introduction
Small shifts in when you receive pay can make bills feel impossible even when income is steady. Mismatched cycles — rent due the week before payday, or a car payment that lands mid-month — introduce stress and late fees. This piece looks at practical, low-friction steps to smooth that pinch and prevent scrambling. You don’t need to overhaul your life; a few targeted adjustments often buy enough breathing room to stop the cascade of missed payments. Read on for concrete tactics you can try this month.
How timing breaks a budget
When a pay date and a bill due date are out of sync, it creates artificial scarcity: money exists on paper but not when you need it. People then rely on credit cards, overdraft protection, or short-term loans that add costs and complicate the next cycle. The pattern repeats until the calendar, rather than cash flow, dictates decisions. Recognizing the mismatch is the first and most useful step toward fixing it.
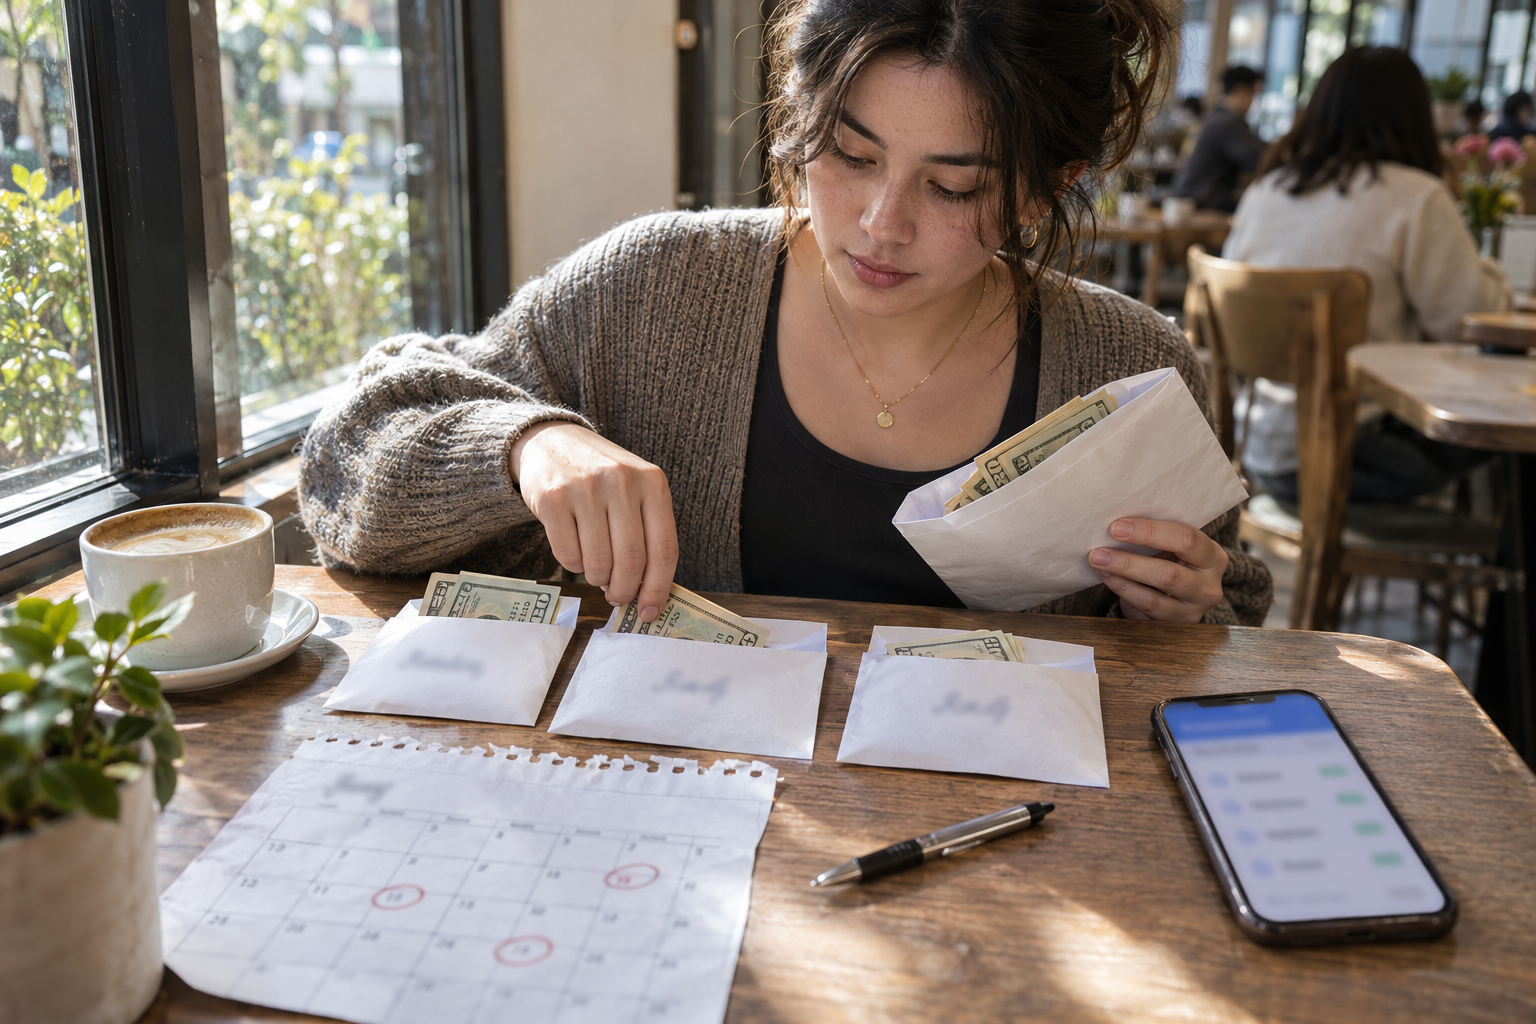
Start by mapping your pay dates against all fixed payments and highest-priority variable costs. That simple visibility will show a few obvious pressure points you can address.
Simple switching moves
You can often change nothing about your income and still stop the scramble by shifting due dates or payment methods. Ask lenders and service providers to move due dates a week or two; many utilities and loan servicers will adjust schedules on request. For subscriptions and auto-pay, a short swap can align payments with incoming funds. Small calendar edits create steady rhythms that reduce late fees and anxiety.
Also consider splitting an account: direct a portion of each paycheck into a bill account so funds are waiting when bills clear. That small habit prevents guessing games and keeps essentials covered.
Build a tiny timing buffer
An emergency cushion doesn’t have to be three months of expenses to help; even one or two paychecks’ worth of float changes behavior. Aim for a starter buffer equal to one rent or mortgage payment, built over several weeks with automated transfers. Use a separate ‘timing’ account so the money isn’t tempting for day-to-day spending. Keep the transfers small and consistent so they feel affordable.
- Shift one bill due date to the week after payday.
- Automate a $25–$100 weekly transfer to a timing account.
- Ask your employer about split deposits or an earlier pay date.
These tactics are lightweight and reversible if you need to tweak them. Try one change at a time and measure whether late fees and stress drop.
Conclusion
Small calendar and account changes solve more cash-flow headaches than complex budgets. Focus on aligning inflows with outflows and building a one-payment buffer. You may find fewer surprises and more control by next month.