
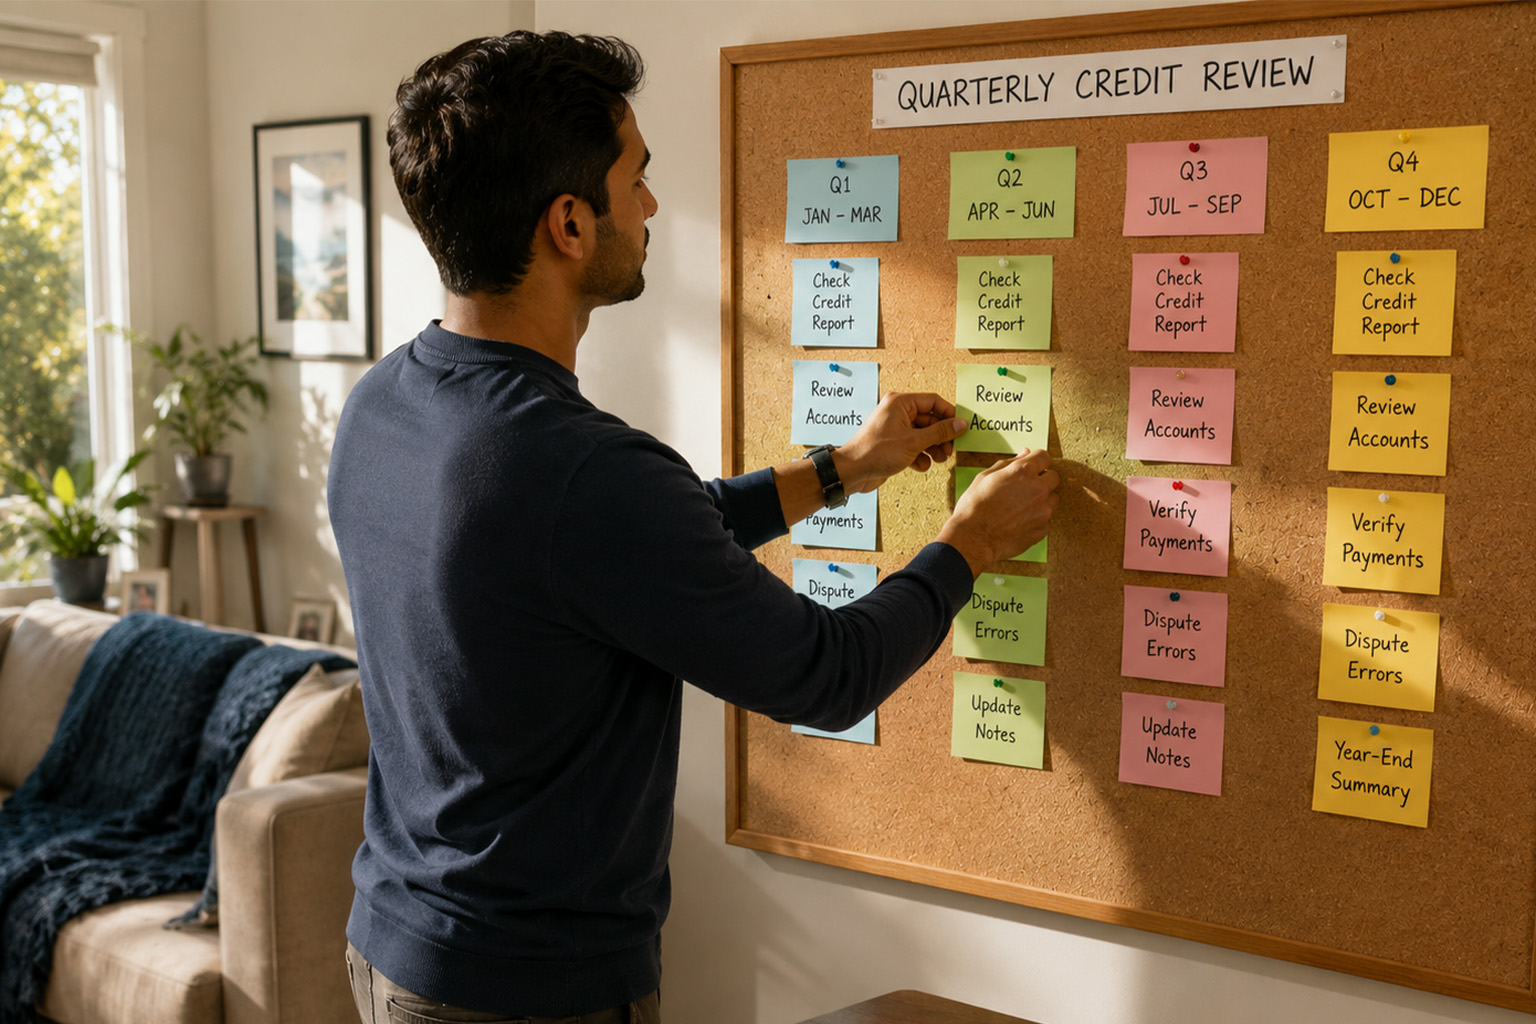
Introduction
Sticking to a quarterly review creates a manageable cadence for credit improvement.
By reviewing accounts every three months you catch errors and trends before they compound.
A predictable schedule reduces procrastination and helps prioritize the highest-impact actions.
This approach balances vigilance with time efficiency so you can make steady progress.
Regular checkpoints let data settle between reviews while keeping momentum toward goals.
Quarterly planning is less burdensome than monthly checks yet timely enough to respond to changes.
Why a Quarterly Routine Works
Credit files and scores fluctuate on a schedule tied to billing cycles and reporting dates, so a three-month interval gives meaningful updates without noise. Quarterly reviews reduce busywork: you avoid reacting to short-term swings while still detecting patterns. The cadence also aligns well with common financial tasks like refinancing, budget planning, and seasonal expenses. Over time, consistent quarterly attention compounds: small adjustments made regularly tend to deliver more reliable improvements than sporadic, intensive efforts.
Adopting this rhythm helps turn abstract goals into concrete checkpoints. It makes credit management part of your routine rather than an occasional emergency.
What to Check Each Quarter
Start with the fundamentals: verify payment history entries for accuracy and confirm there are no late payments recorded in error. Next, review balances and utilization across revolving accounts to understand trends and whether any accounts show unexpected spikes. Scan for new inquiries, collections, or unfamiliar accounts that could signal identity or reporting issues. Finally, note account age and mix so you can see the long-term factors that shape your profile.
- Payment status and recent delinquencies
- Current balances and utilization percentages
- New inquiries, collections, or unauthorized accounts
- Age of accounts and overall account mix
These checks give a clear picture of where to focus effort in the coming months. Keeping a short checklist makes the quarterly review quick and actionable.
How to Adjust Between Quarters
When a quarterly review highlights an issue, set simple, measurable actions to address it before the next check. Examples include scheduling automatic payments, targeting one or two balances for reduction, or initiating disputes on clear reporting errors. If you plan to add credit, time applications thoughtfully so inquiries and new accounts fit your broader timeline. Track small wins, update your checklist, and adjust priorities as your situation evolves.
Small, consistent adjustments between reviews prevent problems from growing and keep progress steady. Use each quarter as a moment to recalibrate rather than overhaul your strategy.
Conclusion
A quarterly routine is practical and sustainable for most people.
It provides timely insight without excessive effort.
Over time, steady attention produces meaningful, lasting improvements.