
Introduction
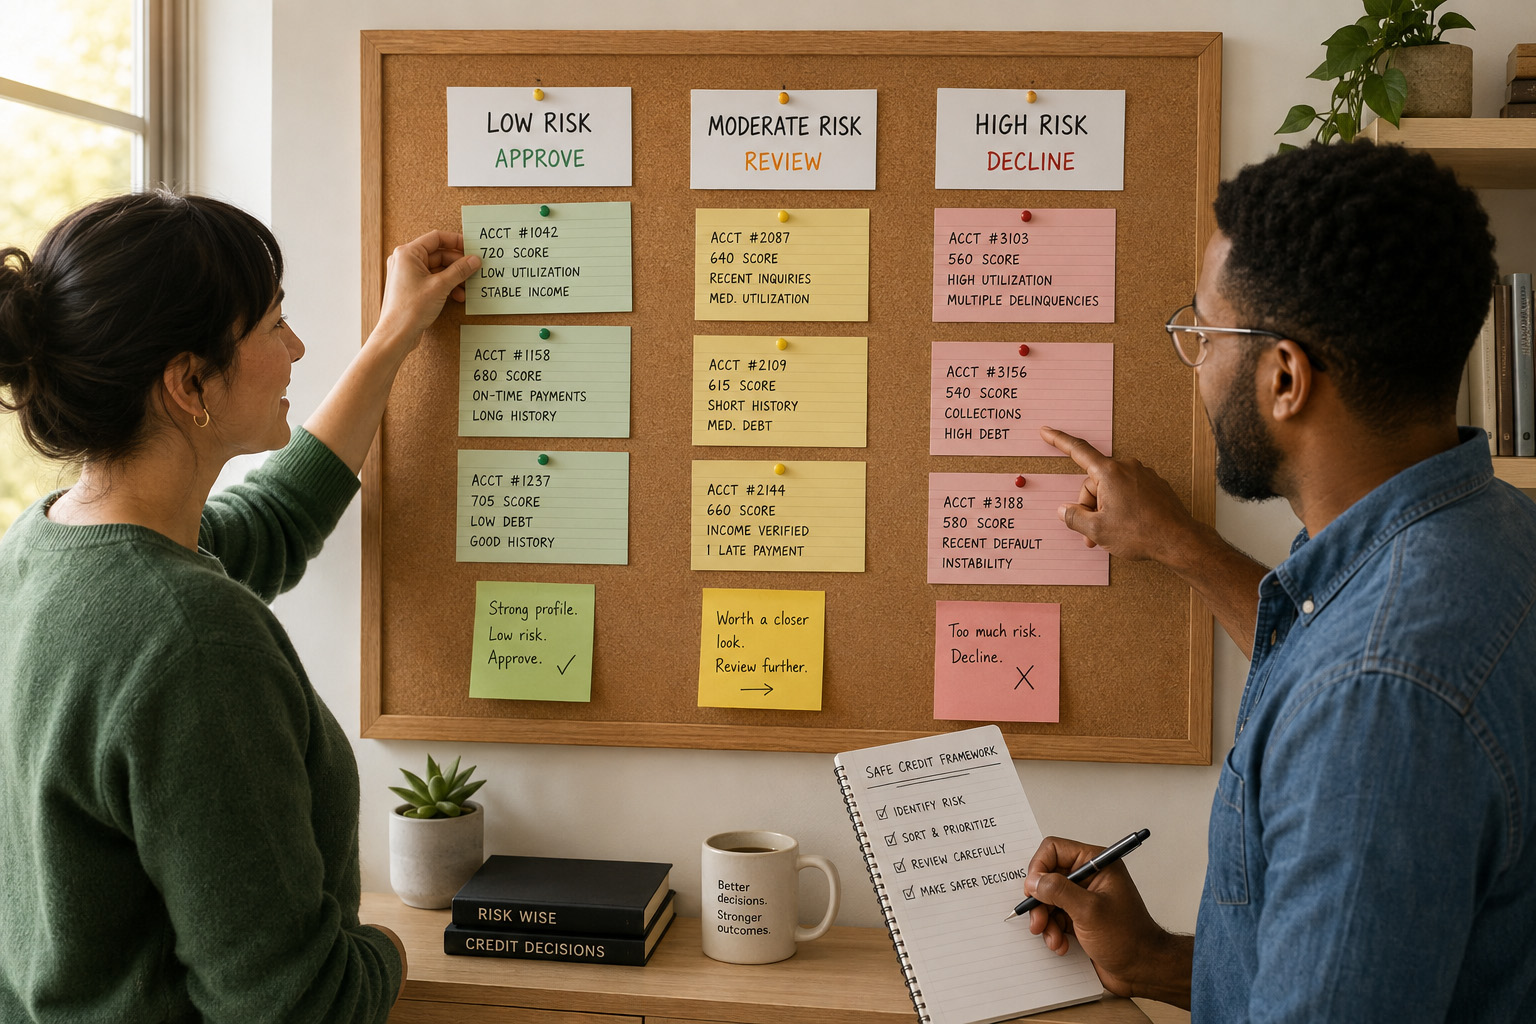
Making better credit decisions doesn’t require dramatic overhauls or risky maneuvers. Small, deliberate choices each month can reduce risk and produce measurable improvements over time. This piece outlines a clear framework you can adapt to your schedule and financial situation. Followable steps help you prioritize actions that matter most for score stability and long-term access to credit.
Start with a Clear Snapshot
Begin by gathering the facts: recent statements, balances, and the details on any accounts in collections or charge-offs. Understanding where you stand eliminates guesswork and highlights the highest-impact issues. A concise snapshot lets you focus on accounts that affect utilization and payment history most. Keep this summary updated monthly so decisions are based on current information.
- List active accounts with current balances and minimum payments.
- Flag missed payments and any accounts reporting derogatory information.
- Note open but unused credit lines and their limits.
Having a single, simple document reduces overwhelm and speeds decision-making. Use it to set short-term priorities that align with long-term goals.
Make Low-Risk, High-Impact Moves
Target actions that improve key score factors with minimal downside. Paying down revolving balances toward a lower utilization ratio often yields reliable benefits. Keeping payments on time and avoiding new hard inquiries are foundational and low risk. Small reallocations of payment priority can prevent larger problems and steadily improve your profile.
- Allocate extra funds to the card with the highest utilization rate.
- Set automatic payments for at least the minimum due on every account.
- Avoid opening unnecessary new credit unless it serves a clear purpose.
These moves balance immediate improvement with protection against new risk. Think of them as defensive steps that also produce forward momentum.
Track Progress and Adjust Tactically
Measure outcomes and be willing to tweak the plan based on what works. Check your snapshot monthly and compare balances, utilization, and any changes to reported payments. If a particular tactic stalls, reassess priority and reallocate resources toward the next highest-impact accounts. Incremental adjustments keep the plan realistic and responsive.
- Record one or two measurable goals each month, such as lowering utilization by a set percentage.
- Revisit automated payments and payoff targets quarterly.
Consistent measurement reduces surprises and helps maintain discipline. Regular review keeps the framework aligned with evolving needs.
Conclusion
Adopting a simple framework focuses effort on what actually moves a credit score. Small, consistent steps reduce risk while building progress over time. With regular tracking and tactical adjustments you can improve credit standing without stress.