
Introduction
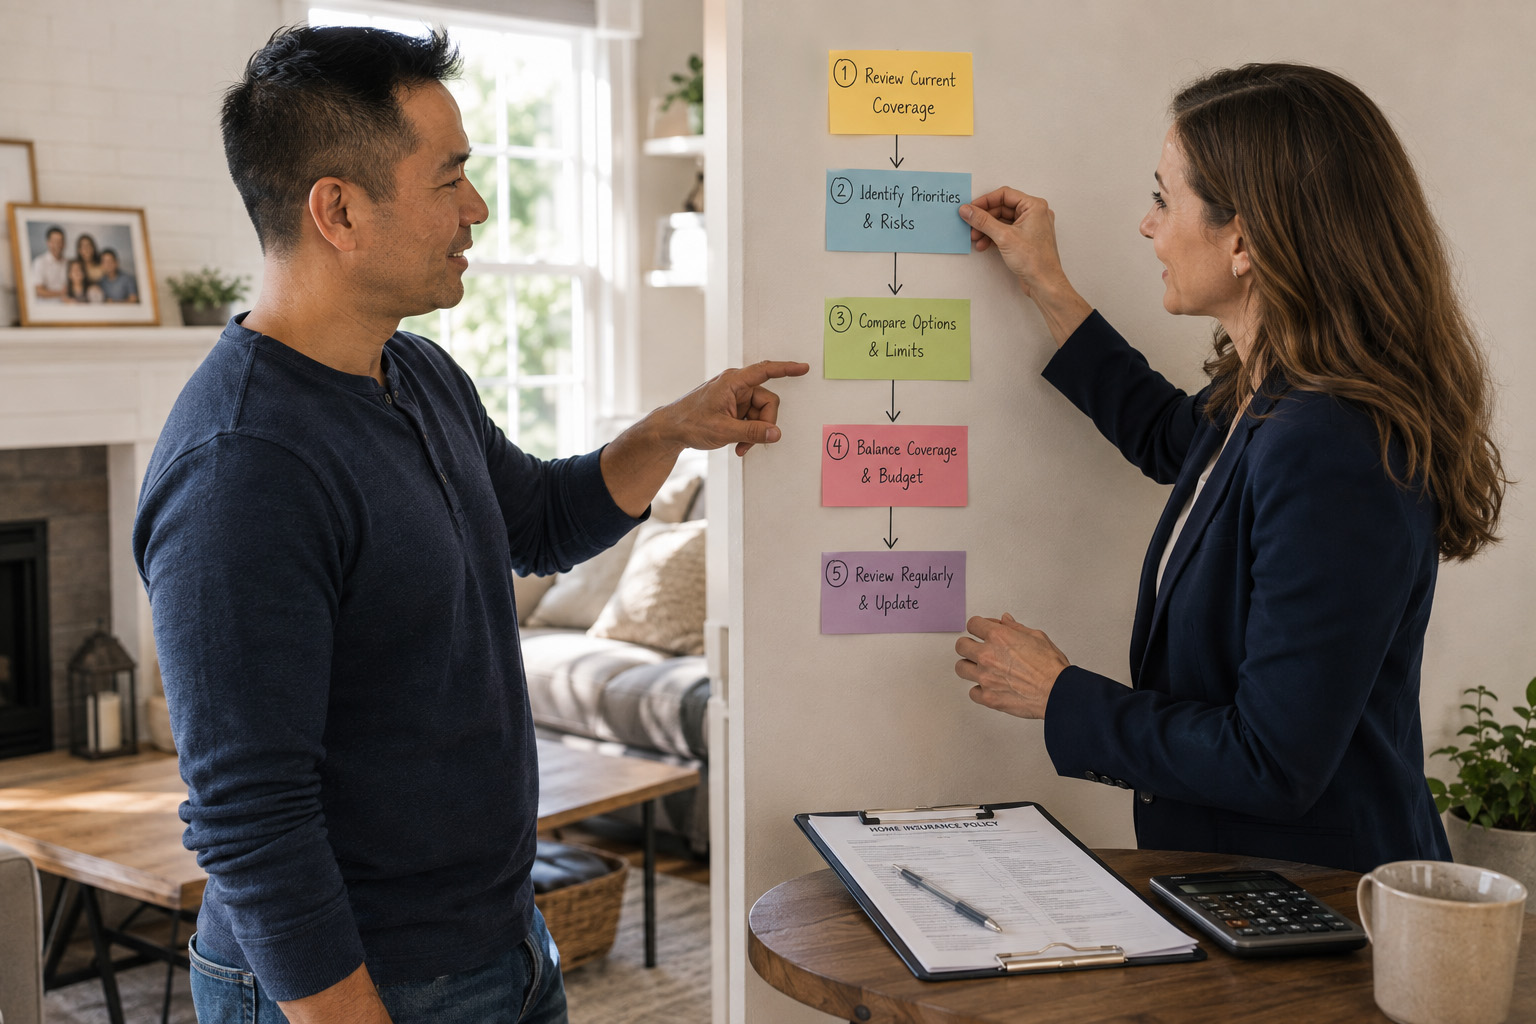
Making insurance choices can feel overwhelming, but a clear process turns uncertainty into manageable steps. Start by identifying the losses that would most disrupt daily life, then consider how quickly you could recover from each. Focus on the practical impacts: cash flow, housing, transportation, and essential services first. A disciplined sequence helps match premiums to real household priorities and reduces both cost and coverage gaps.
Assess Your Household’s Critical Functions
Begin by listing the things that must keep working after a loss: a place to live, income to pay bills, reliable transport if needed, and access to important services like childcare or medical care. For each item estimate how long you could cope without it and what replacement would cost, because frequency and impact drive sensible coverage choices. This assessment helps separate high-impact, low-frequency events you should insure from minor losses you can self-fund. Keep the analysis pragmatic and update it when major life changes occur, such as a move, career shift, or new dependent.
Rank these functions by time sensitivity and cost to restore so you have a prioritized list for coverage decisions. Use that list to guide whether to buy, raise limits, or accept higher deductibles on different policies.
Map Risks to Affordability and Policy Terms
Once priorities are clear, map each risk to available policy terms: covered perils, limits, deductibles, exclusions, and claim triggers. Compare the premium impact of modest limit increases against the potential out-of-pocket recovery cost; sometimes a slightly higher premium buys far faster repair or replacement. Don’t overlook policy details that affect recovery speed, such as replacement cost versus actual cash value, or additional living expense limits after a home loss. Align deductible choices with your emergency cash so you aren’t forced to file claims for small losses.
Document trade-offs in writing so renewals and agent conversations stay focused on restoring household function rather than reacting to fear-based sales pitches.
Sequence, Monitor, and Adjust Coverage
Sequence purchases to secure the top-ranked functions first, then layer secondary protections as budget allows; for many households that means prioritizing property and income replacement-related coverages. Review policies annually or after life events and when premiums rise significantly, and perform a simple claims-history check to decide if a deductible change is warranted. Consider bundling or multi-year discounts where they genuinely lower total cost without creating coverage gaps. Periodic monitoring prevents unpleasant surprises and keeps protection aligned with changing needs.
Maintain clear records of limits and renewal dates, and schedule a short coverage review each year to ensure priorities still match your life.
Conclusion
Adopting a stepwise insurance process reduces expense and improves recovery speed by matching coverage to what truly keeps your household running. Regular assessment, practical mapping of risks to policy terms, and disciplined sequencing make coverage decisions more predictable and defensible. Small, scheduled reviews ensure your plan stays current as circumstances change.