
Introduction
When your paycheck timing or size feels uncertain, a short-term cash playbook keeps choices clear and calm. This practical guide focuses on the next few weeks, helping you decide what to pay, what to pause, and where to tighten. It avoids long-term planning and instead offers a compact sequence of actions you can take now. The aim is to protect essentials while reducing stress and preserving optional spending.
Use these steps as a repeatable routine you can apply any time cash is constrained. They are designed to be simple, measurable, and easy to communicate to household members. Adopt one rule at a time so the change feels manageable and realistic.
Assess Your Immediate Obligations
Start by listing due dates and minimum amounts for the coming 30 days, focusing on housing, utilities, transportation, and food. Include essentials that, if missed, would create outsized problems such as eviction, service shutoffs, or delayed work. Note flexible costs that can be deferred with little consequence, like subscriptions, nonessential deliveries, or discretionary purchases. This snapshot gives you a clear view of fixed obligations and the timeline you must protect.
Keep this list short and updated; clarity reduces panic. Knowing exact amounts and dates lets you sequence payments rather than guessing.
Build a Simple Priority Sequence
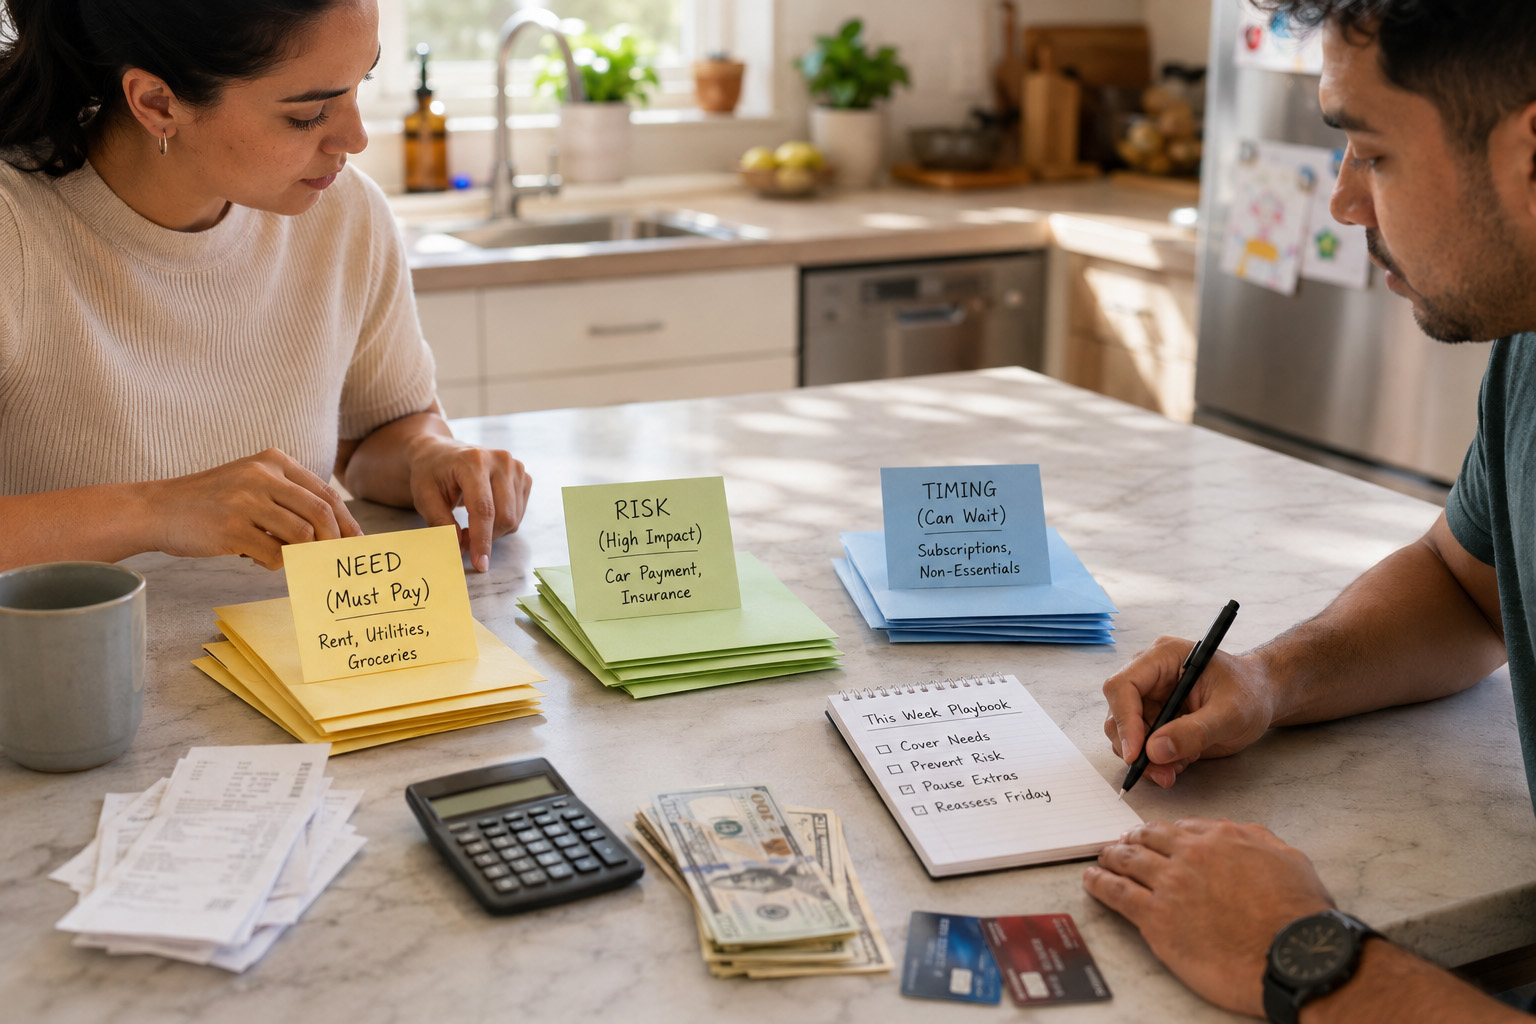
Create three priority tiers: critical, manageable, and deferrable. Critical covers items that threaten your stability if unpaid, manageable includes bills you can negotiate or pay partially, and deferrable holds costs you can pause until cash returns. Assign each item from your obligation list to one tier and record the next action for each, such as contacting a creditor, scheduling a partial payment, or canceling an optional service. This structured order helps avoid emotional decisions when funds arrive.
Stick to the tiers consistently; the method works best when repeated. Over time you’ll recognize patterns and refine what truly belongs in each tier.
Practical Moves to Stretch Available Funds
Once priorities are set, apply a few targeted moves to extend cash: negotiate due dates or minimums, shift payday timing if possible, and draw a short, prioritized spending list for the week. Lean on low-friction actions first, like pausing subscriptions or opting for lower-cost groceries. If you need to free more cash, consider small temporary trade-offs such as postponing nonessential subscriptions or reducing discretionary transport costs. Small adjustments add up quickly when they’re deliberate.
- Contact lenders to request a short-term accommodation.
- Use a prioritized shopping list to limit impulse buys.
- Temporarily pause nonessential recurring payments.
Apply these moves in the order of your priority tiers. They preserve essentials while minimizing long-term disruption.
Maintain Momentum and Review
Set brief weekly check-ins to update your obligation list and mark progress, and treat those reviews as commitments. Track every payment and any conversations with service providers so you can follow up if needed. When cash stabilizes, restore paused items thoughtfully and rebuild a small buffer to ease the next lean week. Consistent review keeps you responsive and reduces the chance that a temporary squeeze becomes a larger problem.
Small, regular habits prevent unnecessary stress and create predictable behavior. Celebrate the wins and adjust the playbook as circumstances change to keep it practical and useful.
Conclusion
Create a short, repeatable sequence: assess obligations, assign priorities, apply practical stretches, and review weekly. This compact playbook keeps essentials protected and decisions straightforward during tight weeks. With modest habits, you can reduce anxiety and reclaim control of short-term cash.