
Introduction
Insurance should do more than check a box; it should mirror the real costs your household faces each month and after a loss. Many people carry policies that are too large in one area and too small in another, creating gaps or wasted premium. Taking a systematic approach helps you buy only what you need and keeps your household running after an interruption. This article explains practical steps to align coverage with actual replacement, income, and cash-flow realities.
Document what you would actually replace
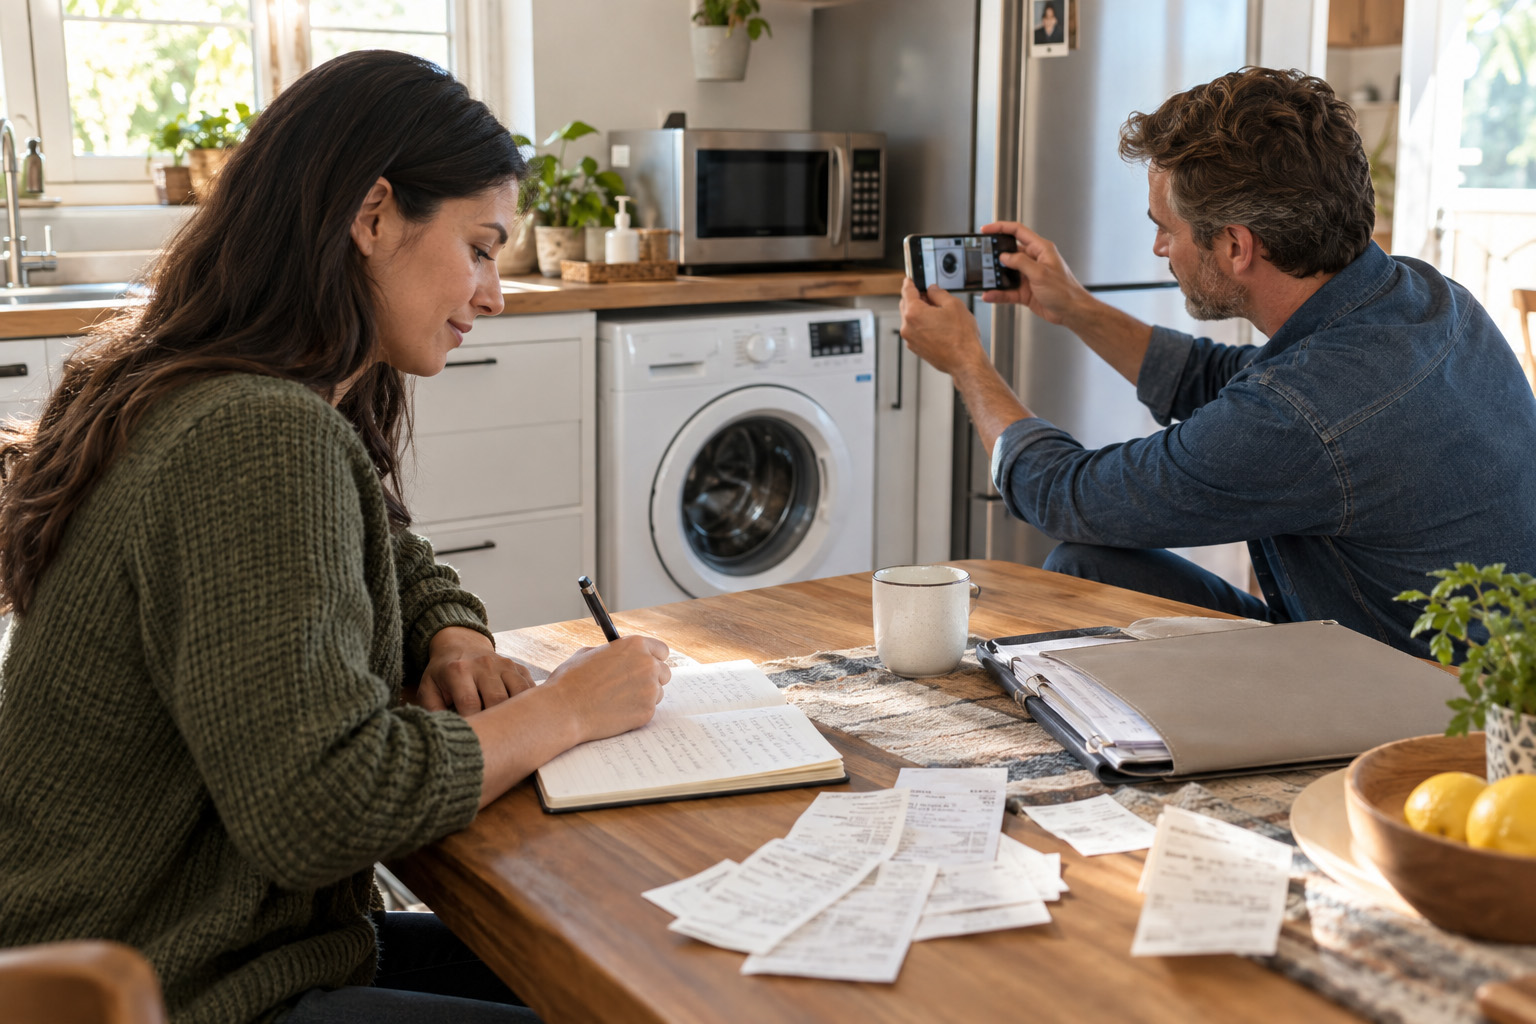
Begin by listing tangible items, recurring services, and repair priorities you would replace if damaged or lost. Count not just big-ticket items but smaller essentials that keep the household functioning, such as appliances, a single vehicle, or a home office setup. Estimate realistic replacement costs rather than sticker prices to avoid under- or over-insuring. Use receipts, photos, and online pricing to build a plain-language inventory that informs policy limits.
When you have a clear inventory, policy choices become less abstract and more measurable. That clarity reduces overlap and uncovers gaps you might otherwise miss.
Match policy limits to replacement and income needs
Coverage limits should reflect both the cost to replace property and any income you need to maintain lifestyle after a loss. For homeowners, replacement cost versus market value matters; for renters, focus on personal belongings and temporary housing. For income protection, calculate monthly obligations and the length of time you would need benefits to recover. Avoid formulaic limits; tailor amounts to the real dollar needs identified in your inventory and budget.
Customizing limits prevents surprises and reduces the temptation to file unnecessary claims that can raise premiums. It also ensures insurance pays what you truly require to restore normal life.
Set deductibles to match emergency savings strategy
Deductibles are a lever to control premiums, but they must align with accessible emergency funds. If your cash reserves can comfortably cover a higher deductible, you can reduce premiums and keep insurance for catastrophic losses. Conversely, if savings are thin, a lower deductible reduces out‑of‑pocket strain after a claim. Think of deductible choice as a partnership between your policy and your liquid savings.
Review both your deductible and short-term cash buffer together so a claim won’t force harmful borrowing or deferred maintenance.
Review policies on a predictable schedule
Household costs and priorities evolve, so a once‑a‑year policy review helps keep coverage aligned with current reality. Revisit your inventory, adjust limits after major purchases or life changes, and compare quotes periodically. Document decisions and renewal dates so you can act before gaps develop or unnecessary premiums persist.
A scheduled review makes small adjustments easier and avoids reactive choices after a loss.
Conclusion
Designing insurance around real household costs reduces waste and improves recovery. Regular inventory, matched limits, and deductible planning form a practical framework. Small, scheduled reviews keep your coverage aligned with changing needs.