
Introduction
Improving a credit score is rarely instantaneous, but a steady monthly routine can deliver clear, measurable gains. Establishing a short list of recurring tasks helps you focus on actions with the biggest impact, reduce surprises, and build momentum over time. This piece outlines practical monthly checkpoints that fit into a typical schedule and explains why each task matters. With consistent application, these steps make credit progress predictable and less stressful.
Set a Monthly Credit Checklist
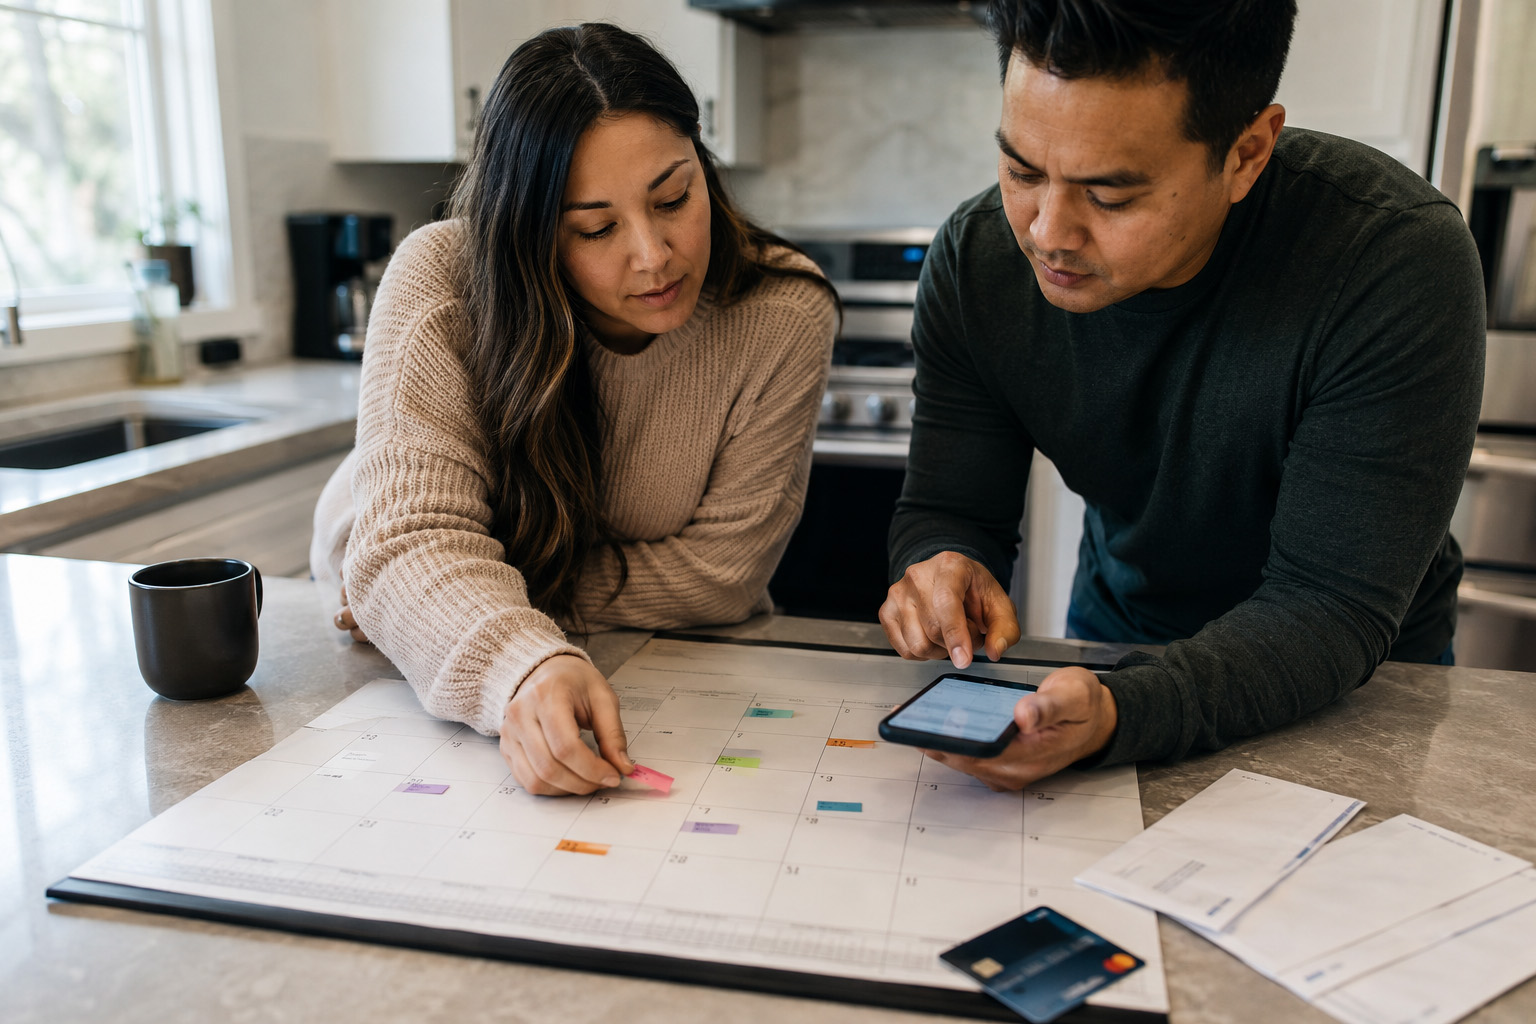
Begin each month by creating a concise checklist that integrates into your existing financial workflow, such as bill pay or budget reviews. Include items like confirming upcoming payments, noting due dates for all accounts, and flagging any new accounts opened in the past month. A checklist prevents missed tasks and helps prioritize high-impact actions, such as paying down near-limit balances. Keep the list short so it is quick to complete and easy to repeat every month.
Reviewing a checklist regularly turns proactive credit management into a habit rather than an occasional scramble. Over time you will reduce late payments and maintain a cleaner account history. Treat the checklist as the backbone of your monthly routine.
Manage Balances and Payment Timing
Track utilization ratios and aim to keep revolving balances well below their limits before statements close, not just by payment due dates. Paying down balances early in the statement cycle can lower the reported utilization that influences score calculations. Schedule at least one mid-cycle payment if you use cards heavily, and set autopay for minimums to avoid late payments while you work on larger reductions. Focus on consistent, on-time payments and gradual balance reduction instead of quick fixes that may not stick.
Payment timing and utilization are closely linked to short-term score movement, so small adjustments can produce visible benefits. Use reminders or calendar alerts to support these changes until they become automatic.
Review Reports and Dispute Errors
Once a month, pull a copy of your credit report or view your online score dashboard to check for new inquiries, unfamiliar accounts, or reporting mistakes. Errors may appear sporadically, and addressing inaccuracies promptly prevents unnecessary damage to your profile. If you find discrepancies, follow the reporting agency’s dispute process and keep records of communications. Regular review also reveals trends and opportunities, such as accounts approaching their age thresholds or changes in account status.
Timely discovery of errors limits the time negative items affect your score and speeds up recovery. Treat report review as both an early warning system and a planning tool.
Conclusion
Consistent monthly actions — a short checklist, smart payment timing, and regular report reviews — compound into measurable credit improvement. Small, repeatable tasks reduce risk and help you prioritize the highest-impact moves each month. Make these checkpoints part of your routine to build lasting credit resilience over time.