
Introduction
When cash feels tight, a short, clear plan reduces stress and keeps essentials covered.
Focus on what must be paid now, what can wait, and how to create breathing room quickly.
This piece outlines practical priorities and simple adjustments to protect your next pay periods.
Follow the steps below to stabilize cash flow and rebuild a small, reliable cushion.
Assess Immediate Obligations
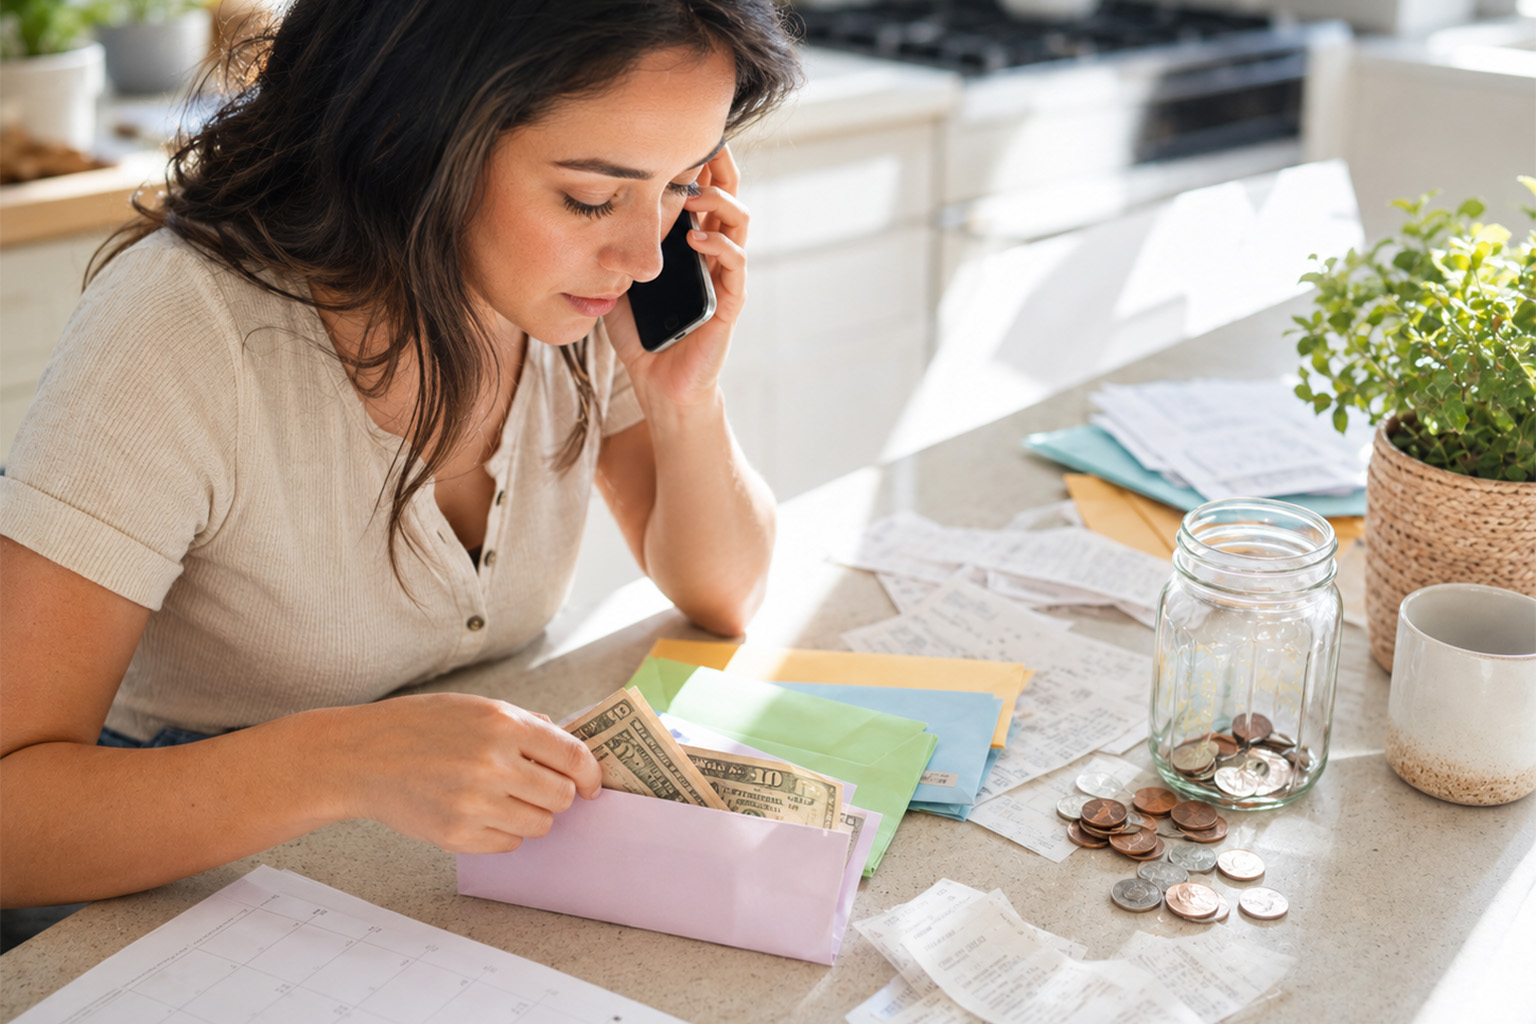
Start by listing all payments due in the coming weeks and mark them by priority. Essentials like housing, utilities, and basic groceries should be at the top because missed payments create bigger problems. Identify any bills with flexible due dates, hardship programs, or options to shift payment timing. Knowing exact totals and deadlines turns uncertainty into a manageable action plan.
Decide which obligations you can negotiate or delay without major consequences. Contact providers early to request short extensions or payment plans; a proactive call often prevents late fees. Keep clear records of any agreements.
Trim and Free Up Cash Quickly
Look for immediate, reversible spending cuts that preserve quality of life while freeing cash. Cancel or pause nonessential subscriptions, reduce discretionary purchases, and adjust grocery lists toward lower-cost staples. Small changes in transport, entertainment, and meal choices can release a meaningful amount within days. Combine trimming with quick one-time actions like selling unused items or shifting delivery schedules to save now.
Use a short checklist to ensure cuts are effective and temporary. Reassess these choices monthly so you reinstate valuable services when cash allows. Track savings to stay motivated.
Sequence Income and Rebuild a Small Buffer
If income arrives in multiple parts, sequence payments so essentials are covered first and small discretionary spends come later. Aim to hold back a modest portion of each incoming payment to form a buffer equal to one to two weeks of essentials. When possible, automate transfers into a separate account or envelope to prevent accidental spending. Even a small, consistent buffer reduces the need for reactive decisions.
Plan next month around the buffer so you don’t deplete it again. Treat the buffer as the priority until it reaches a comfortable level.
Conclusion
Prioritize essentials, trim reversible expenses, and secure a small buffer.
Proactive communication with creditors often eases immediate pressure.
These focused steps restore control and reduce stress over the coming weeks.