
Introduction
Insurance choices should help your household recover quickly after a loss. Focus on the losses that would most disrupt your finances and daily life. Prioritize policies that reduce repair or replacement time and protect ongoing income first. This recovery-focused view makes limited insurance dollars work more effectively.
Assess Your Primary Financial Exposures
Start by listing events that would force big, immediate spending or stop your household from earning. Examples include major medical events, loss of wages, significant home damage, and a totaled vehicle. Estimate both the cost to fix the problem and how long it would take to restore normal cash flow. That combination — cost plus recovery time — should drive the order in which you consider coverages.
Compare those exposures to your emergency savings and liquid assets to see how much you can self-insure. If a gap creates a long period without income or access to shelter, that exposure rises in priority. Use simple scenarios to test how quickly you could recover with and without each policy.
Match Coverages to Recovery Capacity and Priorities
Choose coverages that shorten recovery time for high-impact events rather than those that cover unlikely, low-impact losses. For many households this means ensuring income protection, landlord or homeowner policies that cover major repairs, and auto coverage that replaces a key vehicle quickly. Consider policy features that directly affect speed of recovery: replacement cost, loss-of-income riders, cash benefits, and preferred vendor access.
- Income protection (short- and long-term disability)
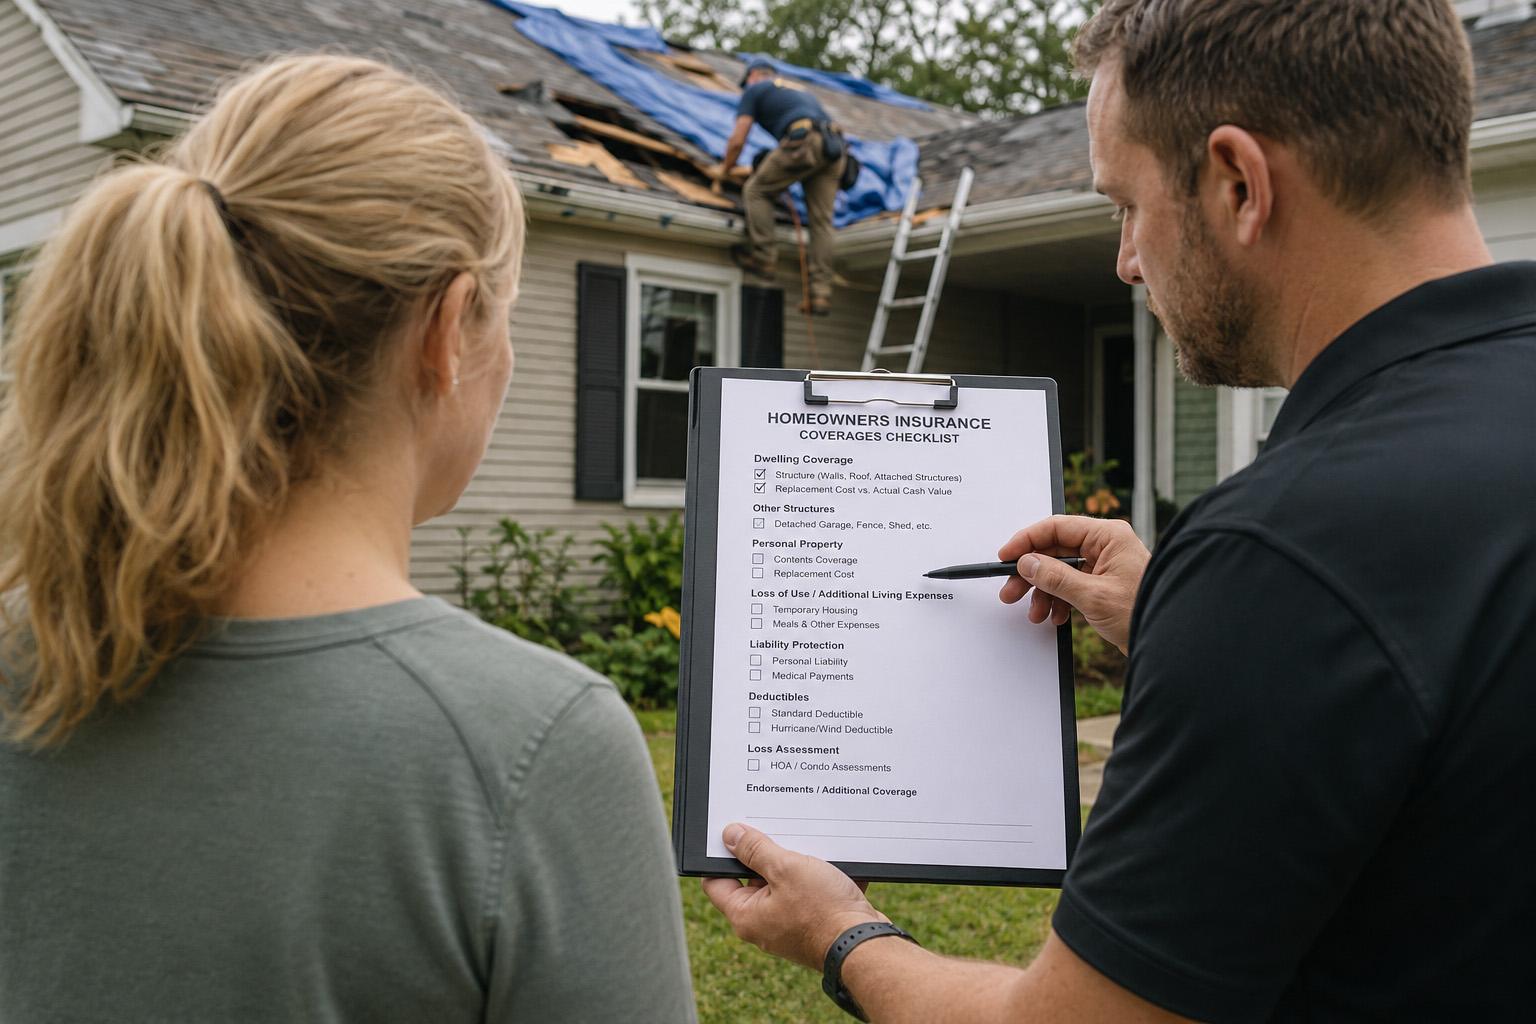
- Homeowners or renters with replacement cost and debris removal
- Auto coverages for collision and gap when a vehicle is essential
These choices are not static; as your assets and responsibilities change, realign coverage to maintain fast recovery for the most damaging events. Regularly revisit priorities after major life changes.
Manage Cost Without Sacrificing Recovery
Control premiums by adjusting deductibles and eliminating duplicate coverages, but avoid cutting coverages that materially extend recovery time. Higher deductibles can be appropriate for losses you can absorb quickly, while lower deductibles make sense when a payment would otherwise cripple recovery. Shop for bundling discounts and review policy limits to match, not exceed, realistic replacement needs.
Document decisions and the scenarios that informed them so you keep protection aligned with real risk. A clear plan prevents reactionary purchases and costly coverage gaps.
Conclusion
Prioritize insurance that shortens recovery time for your biggest financial shocks. Keep policies aligned with how quickly you must get back to normal. Reassess each year or after major life changes.