
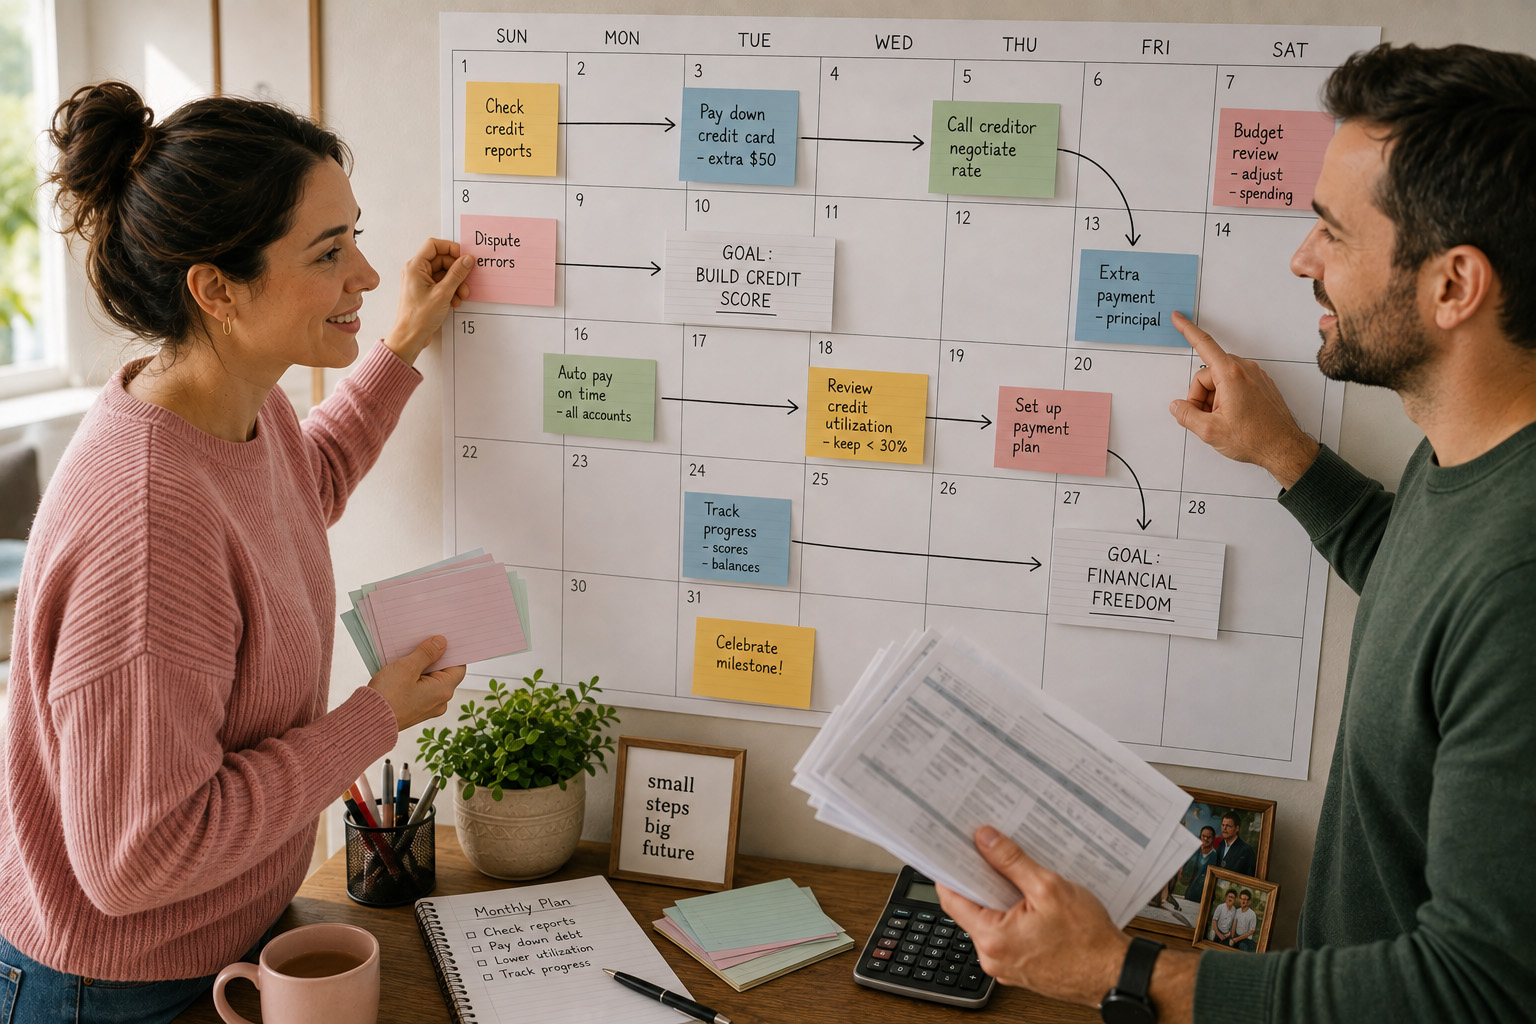
Introduction
A year-long credit plan turns scattershot fixes into steady progress.
By breaking targets into quarters and months you can focus effort where it matters most.
This approach reduces stress and helps prevent impulsive decisions that could harm your score.
A mapped plan also makes it easier to measure results and celebrate milestones along the way.
Below are practical steps to build a balanced, low-stress calendar that supports improved credit health.
Quarterly Goals and Checkpoints
Start by setting measurable quarterly goals such as lowering utilization, paying down specific accounts, or resolving disputes. Quarterly targets should be realistic and tied to data from recent reports so you can track meaningful change. Use the first quarter to stabilize habits, the second to address balances, and the third and fourth to refine and maintain gains. Keeping goals modest helps maintain momentum and reduces the risk of setbacks.
- Q1: Audit reports and automate essential payments.
- Q2: Reduce balances on high-utilization accounts.
- Q3: Diversify credit mix carefully and monitor inquiries.
Review progress at the end of each quarter and adjust targets for the next period. Small, consistent wins compound over a year.
Monthly Routines to Keep on Track
Monthly routines are the engine of a year-long plan and should be easy to sustain. Prioritize on-time payments, keep utilization under control, and check your reports for errors. Set calendar reminders or automation for regular tasks so they require minimal active effort. Even ten minutes a month can prevent common issues from becoming major problems.
Make one small, measurable change each month and track its impact. Consistency outperforms occasional big efforts.
How to Handle One-Off Credit Events
Plan responses for one-off events like applying for new credit, addressing delinquency, or disputing inaccuracies. Before opening an account, estimate its short-term and long-term effects so you avoid unnecessary inquiries. If a delinquency arises, prioritize communication with creditors and set a feasible repayment arrangement. Careful handling of these events prevents long recovery periods and protects the progress you’ve built.
- Before applying: pause other applications and reassess timing.
- If disputing: gather documentation and expect a 30–45 day resolution window.
Treat unexpected events as planned deviations rather than failures. Adaptation keeps the year-long plan resilient.
Tracking and Adjusting Your Plan
Use simple trackers to log balances, utilization rates, and score changes each month. Visual progress helps identify what is working and where to reallocate effort. Quarterly reviews should compare outcomes to targets and surface any recurring obstacles. Based on those insights, tweak automation, payment strategies, or goal timelines as needed.
Regular tracking turns vague intentions into measurable habits. Adjustments ensure the plan remains aligned with changing financial circumstances.
Conclusion
Map your credit improvements across a year with modest, measurable goals.
Combine monthly routines with quarterly reviews to preserve momentum and course-correct when needed.
Steady, deliberate actions yield stronger credit health over time.