
Introduction
Choosing the right insurance strategy starts with clear priorities and realistic expectations. Knowing what you want to protect and how much risk you can absorb guides every decision. This article outlines practical steps to assess needs, compare options, and keep a plan current over time. Use these ideas to make choices that fit your situation and budget.
Assessing Your Coverage Needs
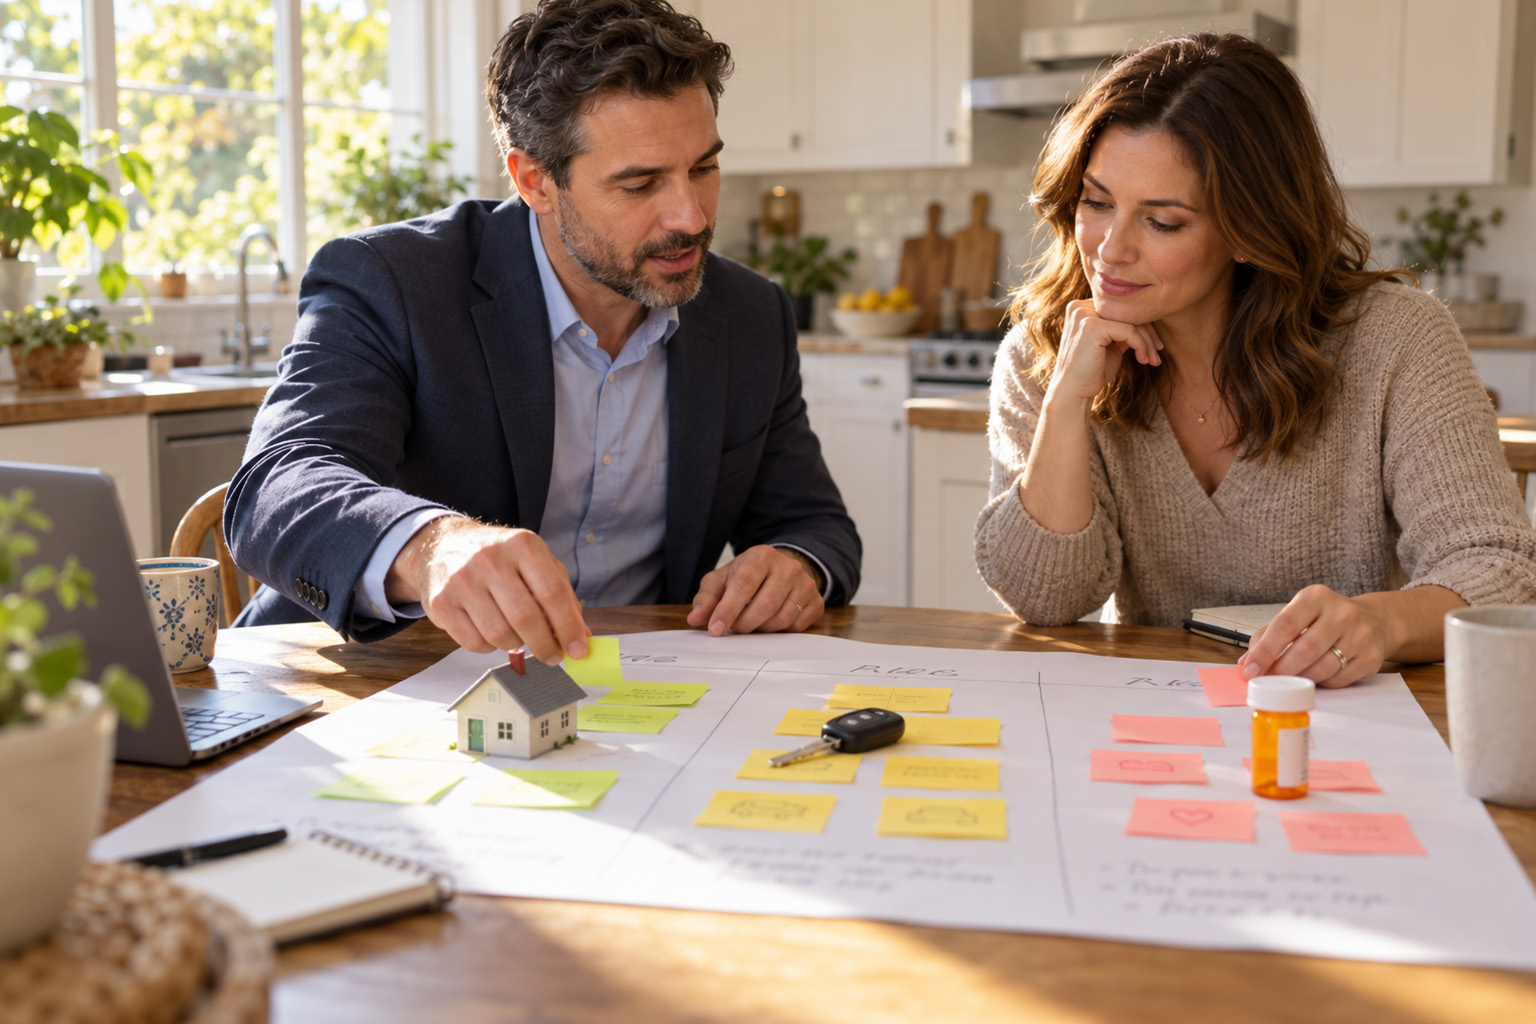
Start by listing assets, liabilities, and the people who depend on your income. Consider scenarios such as a temporary disability, property damage, or an extended illness to estimate realistic costs. Prioritize coverages that would cause financial hardship if left uninsured. Be honest about your risk tolerance and the value of peace of mind.
Gather documents such as pay stubs, mortgage statements, and existing policies to quantify exposures. This makes comparing offers faster and more accurate.
Comparing Policy Features and Costs
Price matters but don’t let it be the only factor. Examine deductibles, limits, exclusions, and how claims are handled to understand real value. Look at the insurer’s financial strength and customer service reputation as these affect long term satisfaction. Pay attention to bundling discounts, loyalty reductions, and any riders that address specific exposures.
Request clear illustrations of coverage scenarios and ask questions until terms are understandable. A slightly higher premium can be worthwhile if it reduces meaningful gaps.
Maintaining and Updating Your Plan
Insurance needs change with life events such as marriage, home purchase, career shifts, and retirement planning. Schedule an annual review to confirm coverage still matches exposures and to capture any new discounts or policy improvements. When you make major purchases or renovations, notify your carrier to avoid unexpected denials. Keep a summary document with policy numbers, agent contacts, and claim procedures for quick access in emergencies.
Small adjustments now can prevent costly gaps later. Make decisions based on documented scenarios rather than assumptions.
Working with an Advisor and Documentation
An experienced advisor can explain nuanced differences between policies and highlight discounts you might miss. Ask for written comparisons and sample policy language to avoid surprises during a claim. Verify any recommendations by reviewing the actual policy terms and not just summaries. Keep digital and printed copies of key documents so you can access them quickly when needed.
Clear documentation simplifies claims and renewals. Choose an advisor whose communication style and fees align with your preferences.
Conclusion
A clear insurance approach combines honest needs assessment, careful comparison, and regular maintenance. Prioritize protections that prevent severe financial disruption while keeping premiums sustainable. Review your plan annually and after major life changes to stay confident in your coverage.