
Introduction
Small, consistent actions each month are the most reliable way to improve your credit score over time. By focusing on a handful of repeatable habits you reduce risk and create measurable progress. This article outlines practical monthly practices that target the key drivers of most scoring models. The goal is steady momentum, not sudden moves that carry extra cost or risk.
Focus on payment consistency
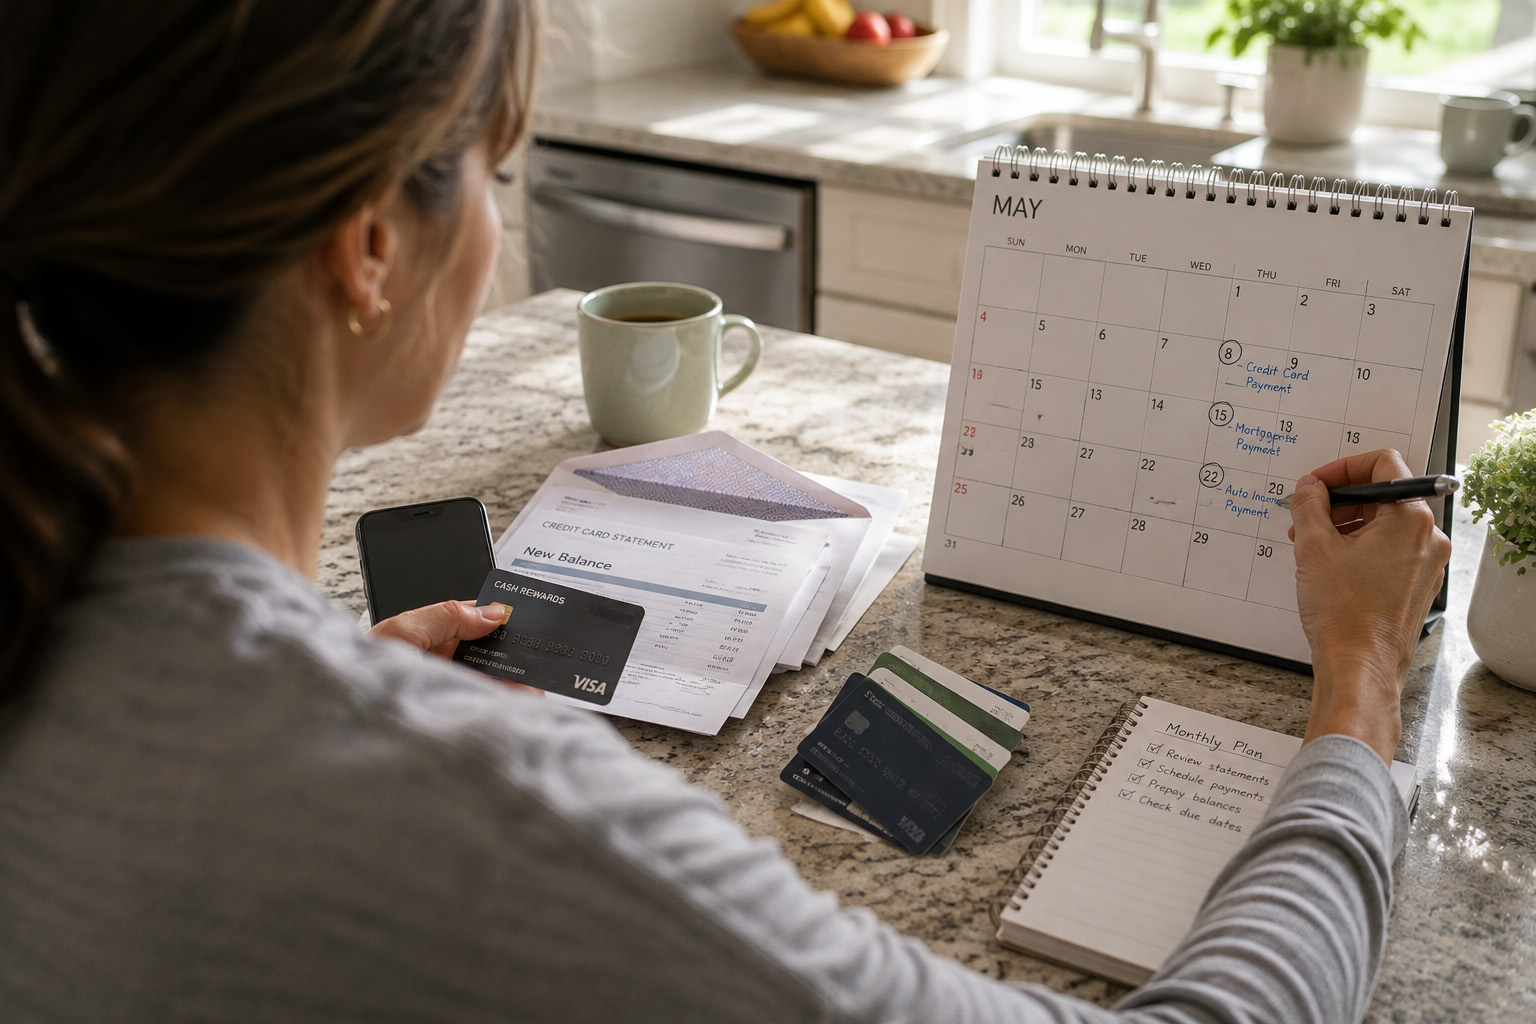
On-time payments account for a large portion of typical credit scores, so the first priority is consistency. Set up automatic payments for at least the minimum due on every account, and then target full balances where possible to minimize interest and keep utilization low. If dates are misaligned, consider asking creditors to change due dates so you can align payments with your pay cycle. Maintaining a reliable payment history reduces volatility and builds long-term trust in your file.
Automations and calendar reminders are practical tools to sustain this habit. They remove emotion from payments and prevent accidental late marks. Review statements monthly to ensure amounts are accurate and authorized.
Manage utilization with simple rules
Credit utilization—the ratio of balances to limits—can swing scores more quickly than age of accounts. Aim to keep reported utilization under a conservative threshold, like 10–30 percent, depending on your situation. If your cards report mid-cycle, a small prepayment before the statement closes can lower the reported balance without changing spending. Avoid repeatedly maxing out cards, and spread charges across accounts when possible to keep each utilization low.
- Track statement closing dates.
- Make a mid-cycle payment if needed.
- Ask for a credit limit increase selectively.
Simple utilization rules are easy to maintain and often produce visible score improvements within a month or two. Consistency matters more than perfection.
Avoid risky account moves and tidy your reports
Hard inquiries, rapid new accounts, and closing old cards can all have unintended effects on your score. Limit new credit applications to necessary situations and try not to close long-standing accounts that contribute age and available credit. Each month, pull a monitored copy of your credit report to check for errors, unauthorized accounts, or incorrect balances. Disputing clear mistakes promptly prevents small issues from becoming larger score drags.
Keeping an eye on your reports also helps you notice identity issues early. A little preventive care reduces surprises and preserves momentum.
Conclusion
Adopt a few repeatable monthly practices—consistent payments, controlled utilization, and regular report checks—to build reliable credit momentum. Small actions accumulated over months create measurable score gains with minimal risk. Focus on steady habits rather than quick fixes to sustain progress.