
Introduction
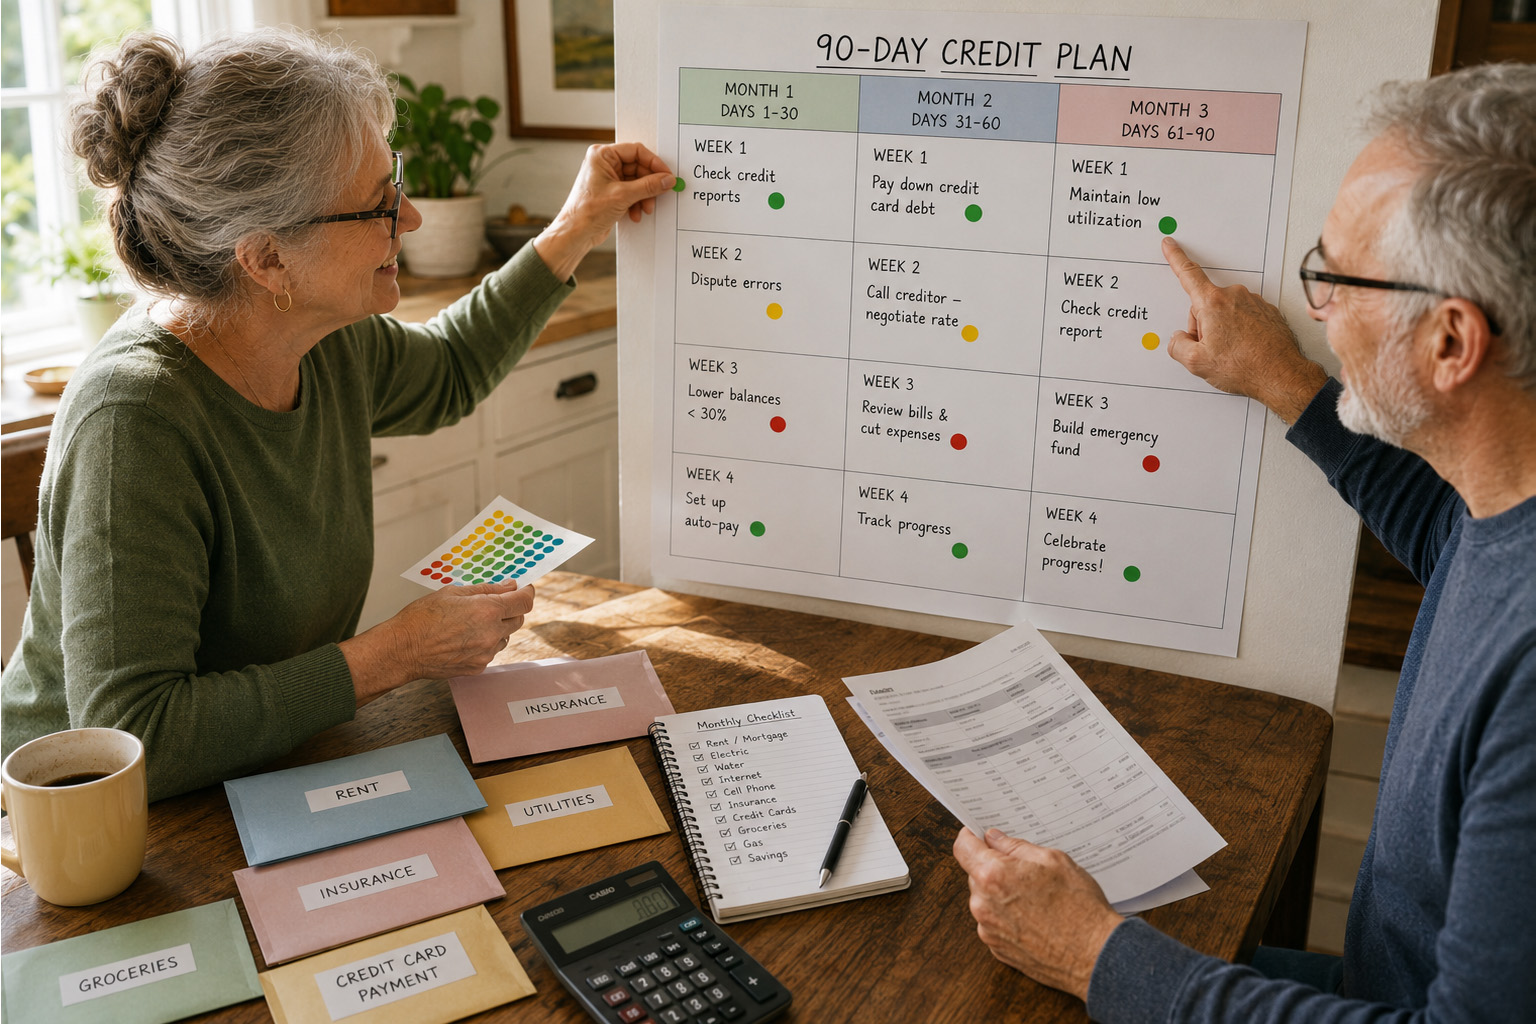
Improving your credit score can feel overwhelming, but a focused 90-day plan creates measurable momentum without drastic changes. This short window is long enough to correct errors, stabilize key behaviors, and set up systems that keep progress steady. By breaking the work into weekly priorities, you avoid burnout and target the actions that matter most to scoring models. The result is a clear, maintainable path that builds both score and confidence.
Start by committing to small, consistent steps and tracking progress each week. Keep expectations realistic: major jumps are rare, but steady gains are achievable. Focus on payment timing, utilization, and reporting accuracy as primary levers.
Why a 90-Day Focus Works
A 90-day period aligns well with billing cycles and reporting schedules for most accounts, making it possible to influence what lenders see in a single quarter. Improvements like resolving a reported error, making a few on-time payments, or lowering utilization can appear on credit files quickly. Short-term plans also foster accountability without requiring a complete financial overhaul. That combination increases the chance of measurable outcomes and sustainable habit formation.
Use this period to set routines that will continue beyond day 90. The goal is not a sprint but a foundation for ongoing improvement.
Weeks 1–4: Stabilize Payments and Correct Errors
In the first month, focus on bringing every account current and disputing any inaccuracies on your credit report. Review each report line item, gather supporting documents, and file disputes or creditor inquiries where necessary. Set up automatic payments or calendar reminders so you don’t miss due dates going forward. Prioritizing on-time payments establishes the single most important signal to scoring systems.
Completing these steps reduces risk and makes subsequent optimizations more effective. Create a basic checklist to ensure nothing is missed.
Weeks 5–8: Lower Utilization and Optimize Accounts
During the middle month, concentrate on reducing credit utilization and managing active accounts wisely. Pay down balances on cards with the highest utilization percentages and consider strategic payment timing before statement closing dates. Avoid closing older accounts that benefit your length of credit history, and be cautious about opening new lines unless they add clear value. Small balance transfers or targeted repayments can shift reported ratios favorably.
- Pay balances above 30% down to under 10–30% where possible.
- Request credit line increases only when it makes sense.
These adjustments improve utilization and preserve the positive account attributes you’ve built.
Weeks 9–12: Build Positive History and Review Progress
The final month is for reinforcing good habits and monitoring results. Continue making on-time payments, keep utilization low, and consider adding a small, well-managed installment or secured product if a credit mix boost is appropriate. Pull updated reports to confirm that disputes were resolved and that reporting reflects your actions. Use this review to plan the next 90 days of maintenance and growth.
Track score changes and note which steps had the most impact. That insight guides ongoing priorities without unnecessary effort.
Conclusion
A 90-day plan concentrates effort into meaningful, measurable actions that influence credit profiles. Small, consistent steps—on-time payments, lower utilization, and clean reporting—combine to produce noticeable improvement. Maintain the routines you build during this period to keep momentum going long term.