
Introduction
Insurance is most useful when it shortens the time between a loss and getting life back to normal. Choosing what to buy and what to self-insure should be driven by how quickly each coverage helps you recover. This article outlines a practical way to order policies by recovery potential, cost, and likelihood. It focuses on clear decisions that fit typical household budgets and priorities.
Assess Immediate Recovery Needs
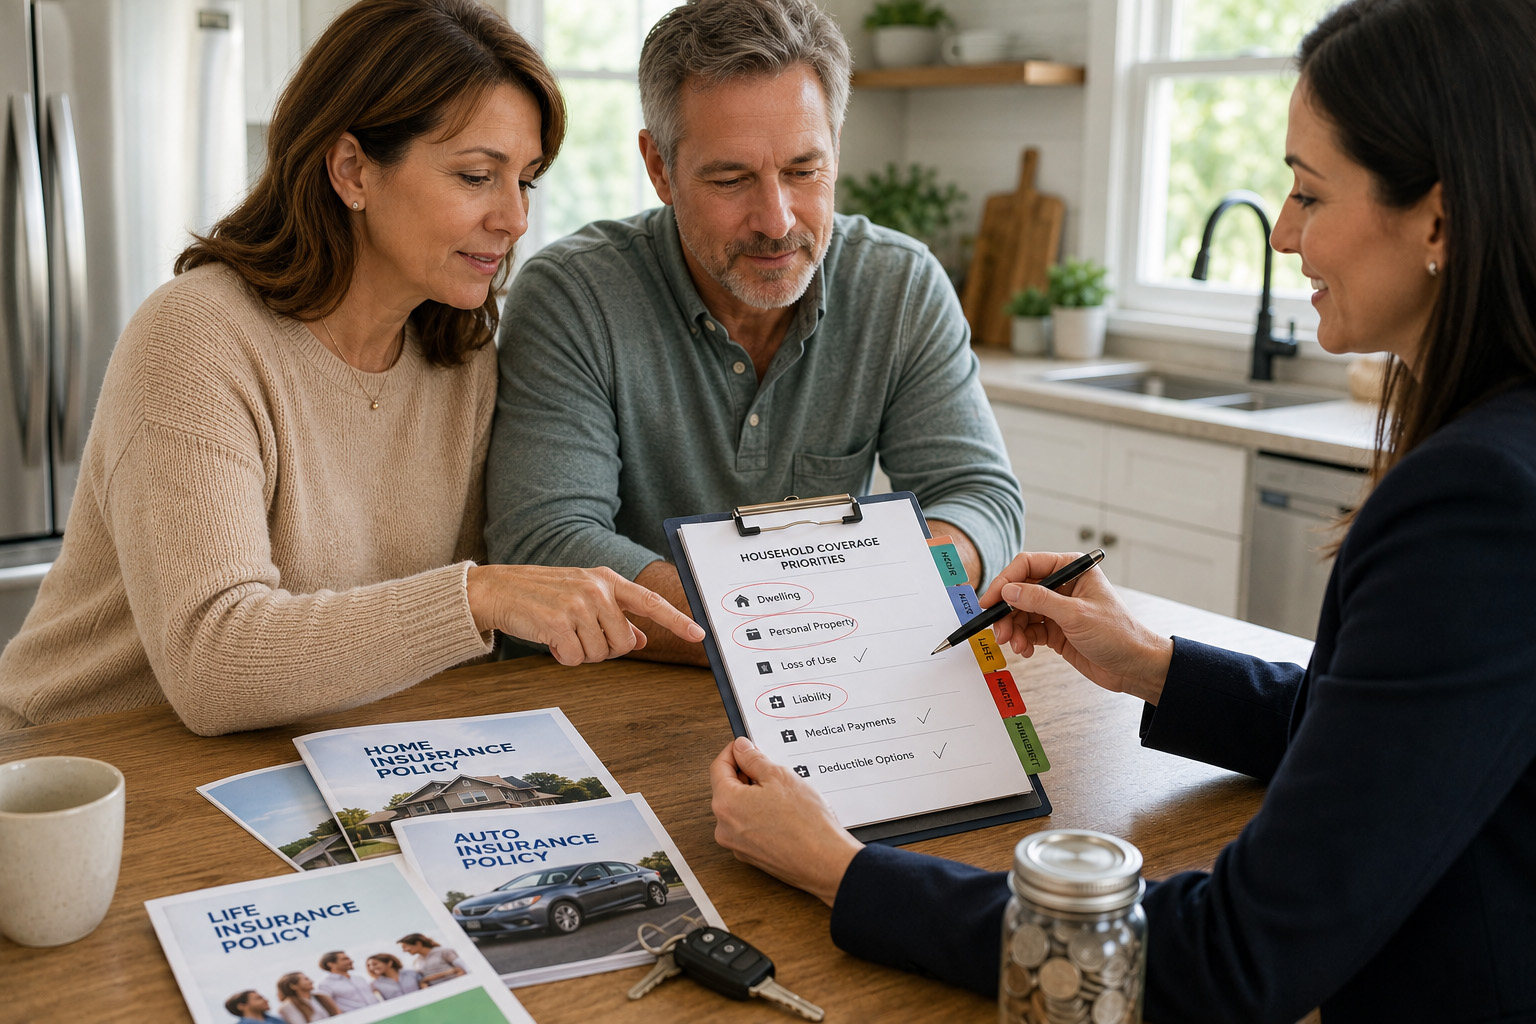
Begin by listing the losses that would stop your household from functioning day to day: lost income, primary residence damage, or urgent medical care. For each item estimate how long you could manage without external help and how much it would cost to restore basic operations. Coverages that remove major time or cash barriers deserve higher priority because they prevent cascading harm. This approach reframes insurance from abstract protection to a tool that preserves routine and cash flow.
Prioritizing by recovery time helps you focus on policies that keep life moving. It also makes tradeoffs easier when budgets are tight.
Balance Probability and Impact
Not every risk needs the same level of insurance: combine likelihood with potential severity when setting priorities. A low-probability but catastrophic event may still require protection if recovery costs would be ruinous. Conversely, frequent minor losses might be cheaper to self-insure through emergency savings and higher deductibles. Ranking risks this way helps allocate premium dollars where they reduce the most disruption.
Use simple scoring to compare risks and decide which policies to buy or expand. That method keeps decisions objective and repeatable over time.
Optimize Deductibles and Limits
Adjusting deductibles and coverage limits is one of the most effective ways to control cost without sacrificing key protections. Higher deductibles reduce premiums but increase the cash you must have ready after a loss, so match them to your emergency liquidity. Likewise, set liability and replacement limits to cover likely recovery costs rather than insuring to theoretical maximums. Thoughtful trimming can free premium dollars to strengthen higher-priority policies.
Maintain enough coverage to avoid catastrophic shortfalls while using gaps where acceptable. Periodically revisit choices as incomes and savings change.
Streamline Policies to Reduce Friction
Complex portfolios increase the chance of gaps, duplicate coverage, or missed renewals, which slow recovery after loss. Consolidate where it reduces cost and administrative burden, and document claim processes for key policies. Simplifying also makes annual reviews faster and more actionable, helping you keep coverage aligned with life changes. Good organization turns insurance into a practical recovery system rather than a confusing expense.
Make a short checklist of contact numbers, claim thresholds, and preferred vendors. That small effort speeds recovery when time matters most.
Conclusion
Focus on what restores your household fastest when choosing and adjusting coverage. Prioritize policies that prevent long interruptions and allocate premiums toward those recovery levers. Regular reviews keep priorities aligned with changing finances and responsibilities.