
Introduction
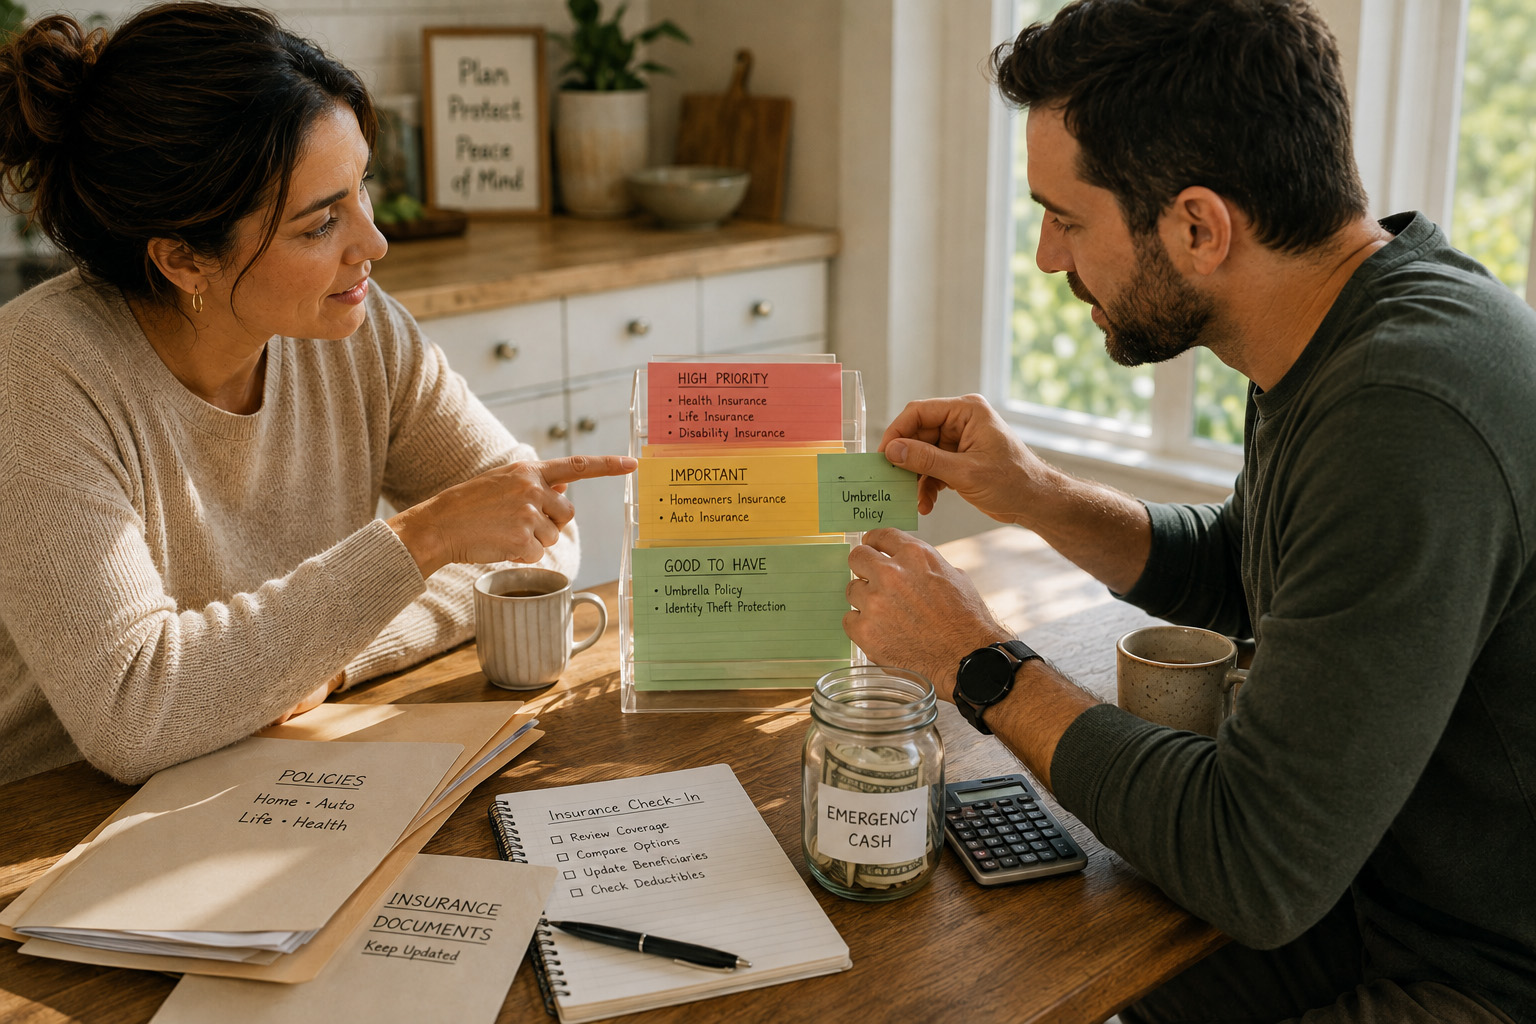
Insurance can feel overwhelming when budgets are tight and risks vary across daily life. A simple triage approach helps you focus on coverages that restore function quickly after a loss. This article outlines how to rank protections by impact, likelihood, and recovery cost. Use these ideas to build a clearer, more resilient household plan.
Assess Household Risks
Start by listing the losses that would most disrupt your household routine or finances. Consider events that would stop work, damage your home, or force major out-of-pocket repairs. Estimate how long recovery would realistically take and what immediate cash flow is required. This assessment turns abstract fears into prioritized, actionable risks.
With a short, ranked list you can target insurance where it actually speeds recovery. Focus first on risks that create long downtime or catastrophic expense.
Sequence Coverages by Recovery Needs
Order coverages by how quickly they get you back to normal rather than by emotional worry. For many households, income protection, liability that threatens savings, and home policies that pay for repairs or temporary living costs come first. Lower-priority items cover minor losses you can absorb with savings. Thinking in terms of speed of recovery clarifies which premiums buy the most practical value.
When you sequence coverages this way you avoid paying more for low-impact fears. It also highlights where higher deductibles make sense and where limits should be increased.
Balance Deductibles and Emergency Savings
Deductibles are a way to trade premium cost for short-term self-insurance. Choose deductibles that align with your emergency fund and cash flow resilience. If your savings cover a higher deductible comfortably, you can lower premiums and keep coverage for major losses. If cash reserves are thin, a lower deductible may be the prudent choice even at higher premium cost.
Make this decision with a clear number in mind: how much can you pay today without disrupting essentials. Regularly revisit the choice as savings grow or expenses change.
Practical Steps to Implement
Start small: update one policy at a time based on your ranked risks and recovery goals. Compare quotes focusing on coverages that matter most, and avoid paying for redundant protections. Document claim triggers, limits, and contacts so decisions are quick during stress. Use a quarterly review to adjust priorities after major life or financial changes.
- Rank three highest-impact risks for your household.
- Confirm coverages that shorten downtime first.
- Adjust deductibles to match emergency savings.
These actionable steps make insurance an intentional part of household resilience. Implementing them reduces cost without sacrificing the protections that keep life moving.
Conclusion
Prioritize policies that speed financial recovery and maintain day-to-day function. Match deductibles to your real cash reserves and review coverage regularly. A focused, practical triage keeps protection effective and affordable.