
Introduction
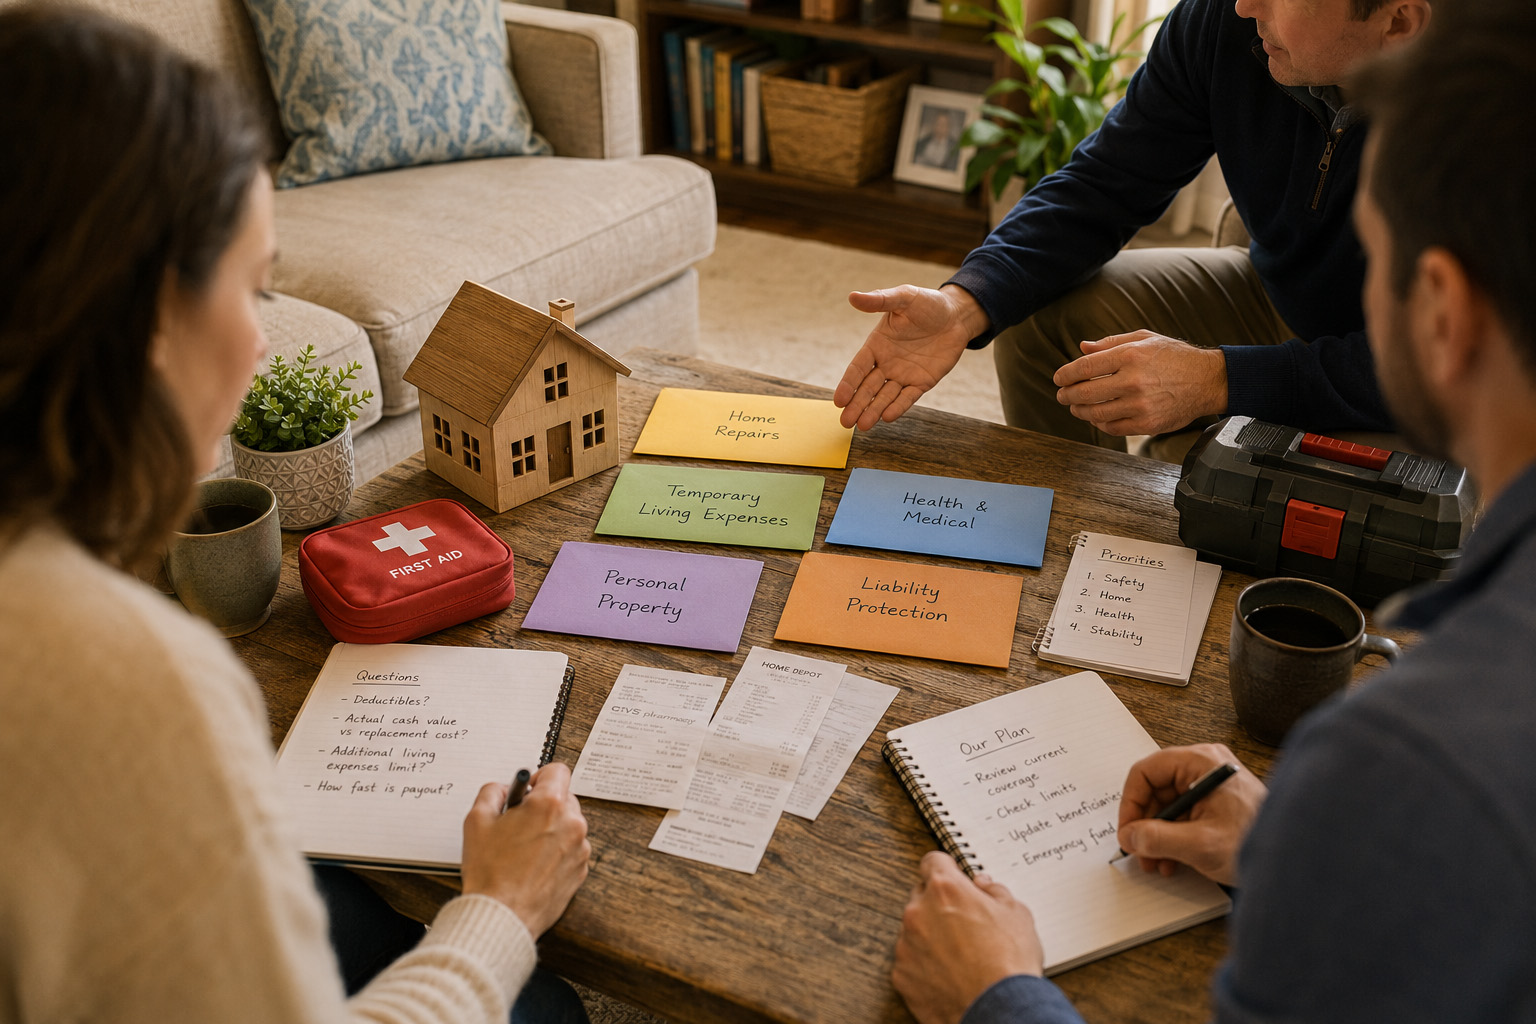
Building an insurance plan is about managing recoverability rather than buying every possible policy. Start by understanding which losses would derail your finances and which you could reasonably absorb. This practical approach helps align coverages with real-life responsibilities and budget constraints. The goal is to speed recovery and protect what matters most over time.
Assess Your Risks and Recoverability
Begin with a clear inventory of assets, income sources, and liabilities, noting dependencies and replacement costs. Consider how quickly you could recover from common events like property damage, medical bills, or loss of income. Distinguish between high-probability low-impact events and low-probability high-impact catastrophes. That assessment guides whether to self-insure, buy primary coverage, or add specialized policies.
- How long could you cover living expenses?
- What assets would be impossible to replace quickly?
- Who depends on your income?
These questions create a practical risk map you can compare to existing policies. They also reveal coverage gaps that matter in day-to-day recovery.
Prioritize Coverages by Impact and Cost
Focus first on coverages that protect immediate financial stability: liability limits, homeowner or renter policy basics, and income protection where relevant. Next consider coverages that address catastrophic drains that could otherwise deplete savings, such as adequate liability umbrella limits or replacement-cost property coverage. Balance the premium cost against the likely recovery timeline if a loss occurs. Prioritization helps you allocate limited dollars toward the protections that shorten recovery the most.
Set target limits that fit your financial plan and revisit them after big life changes. Priorities change over time, so make coverage a periodic checklist.
Reduce Costs Without Sacrificing Core Protection
Shop within a narrow set of priorities to avoid under- or over-insuring. Use higher deductibles for less likely losses if you have sufficient emergency funds, and bundle policies when discounts align with needs. Review exclusions, overlapping coverages, and potential gaps to avoid paying twice for the same protection. Use riders or targeted endorsements rather than blanket upgrades when specific risks require attention.
Small changes in deductible or limits can materially lower premiums without exposing you to unacceptable risk. Keep documentation and compare renewal offers annually.
Conclusion
A resilient personal insurance plan starts with realistic risk assessment and clear prioritization. Focus protection on recoverability and the assets that would be hardest to restore on your own. Regular reviews and targeted cost controls keep coverage effective and affordable long-term.