
Introduction
Short-term money shortfalls are stressful but solvable with a deliberate approach.
This plan focuses on immediate priorities you can act on in days, not months.
It combines quick triage, temporary pauses, and a short rebuild phase to restore stability.
Follow the steps below to protect essentials and buy breathing room.
Assess the gap
Start by quantifying the exact shortfall and its timing so decisions are based on facts rather than worry. Add up upcoming income, scheduled bills, and unavoidable living costs to create a clear cash map for the next 30 to 60 days. Identifying the most urgent payments and those that can be deferred makes sequencing easier. This rapid assessment keeps choices focused and actionable.
Keep the numbers simple and revisit them after any change in income or expense. Small updates will prevent surprises and help you adjust priorities quickly.
Prioritize payments
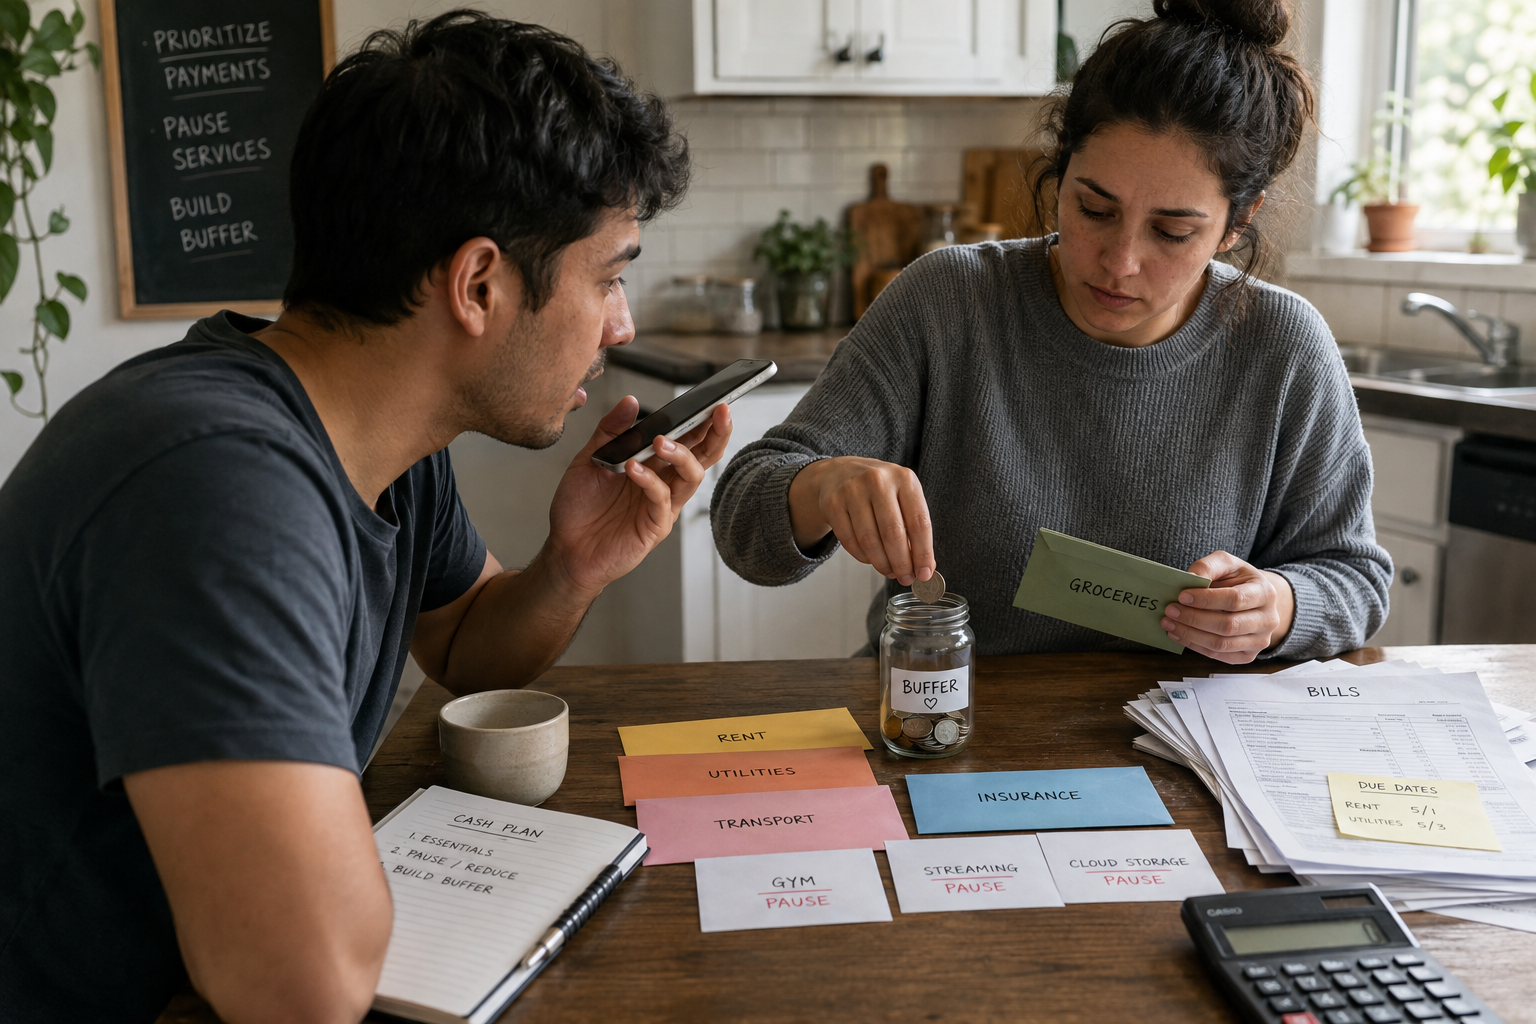
Order your obligations by immediate risk and essential need rather than treating every bill equally. Put housing, utilities that can be shut off, essential transportation, and immediate medical needs at the top of your list. Lower-priority items include discretionary subscriptions, nonessential services, and savings contributions that can be temporarily reduced. A clear priority ladder reduces decision fatigue and targets limited cash where it matters most.
Document the priority list so you can execute payments deterministically during the tight period. That reduces errors and conserves time.
Immediate pause and trimming actions
Act quickly to free up cash by pausing optional payments, calling providers to negotiate due dates, and suspending noncritical spending. Cancel or pause streaming and membership services you can live without for a month or two, and switch to lower-cost alternatives for essentials where possible. Contact lenders and utilities to request hardship plans or short deferrals which often protect credit while easing timing pressures. Small, temporary adjustments add up fast when combined.
Use a temporary spending cap for daily expenses to prevent creep and track each purchase. Transparency in small choices steadies the whole plan.
Rebuild the buffer
Once the immediate window is stable, focus on rebuilding a modest cash cushion to reduce future stress and give you flexibility for the next cycle. Set a reachable short-term savings target and funnel any extra income or reduced expenses toward it until you reach one or two weeks of covered essentials. Treat this buffer as a priority until it can be expanded into a larger emergency fund. Regularly review and modestly automate contributions to maintain momentum over time.
Small, consistent deposits are more effective than sporadic large ones when restoring stability. Celebrate progress to stay motivated.
Conclusion
Act fast to map the gap and rank essentials so scarce cash covers the highest risks.
Pause nonessentials and negotiate timing where possible to buy breathing room.
Then rebuild a modest buffer with consistent, small contributions to reduce future shocks.