
Introduction
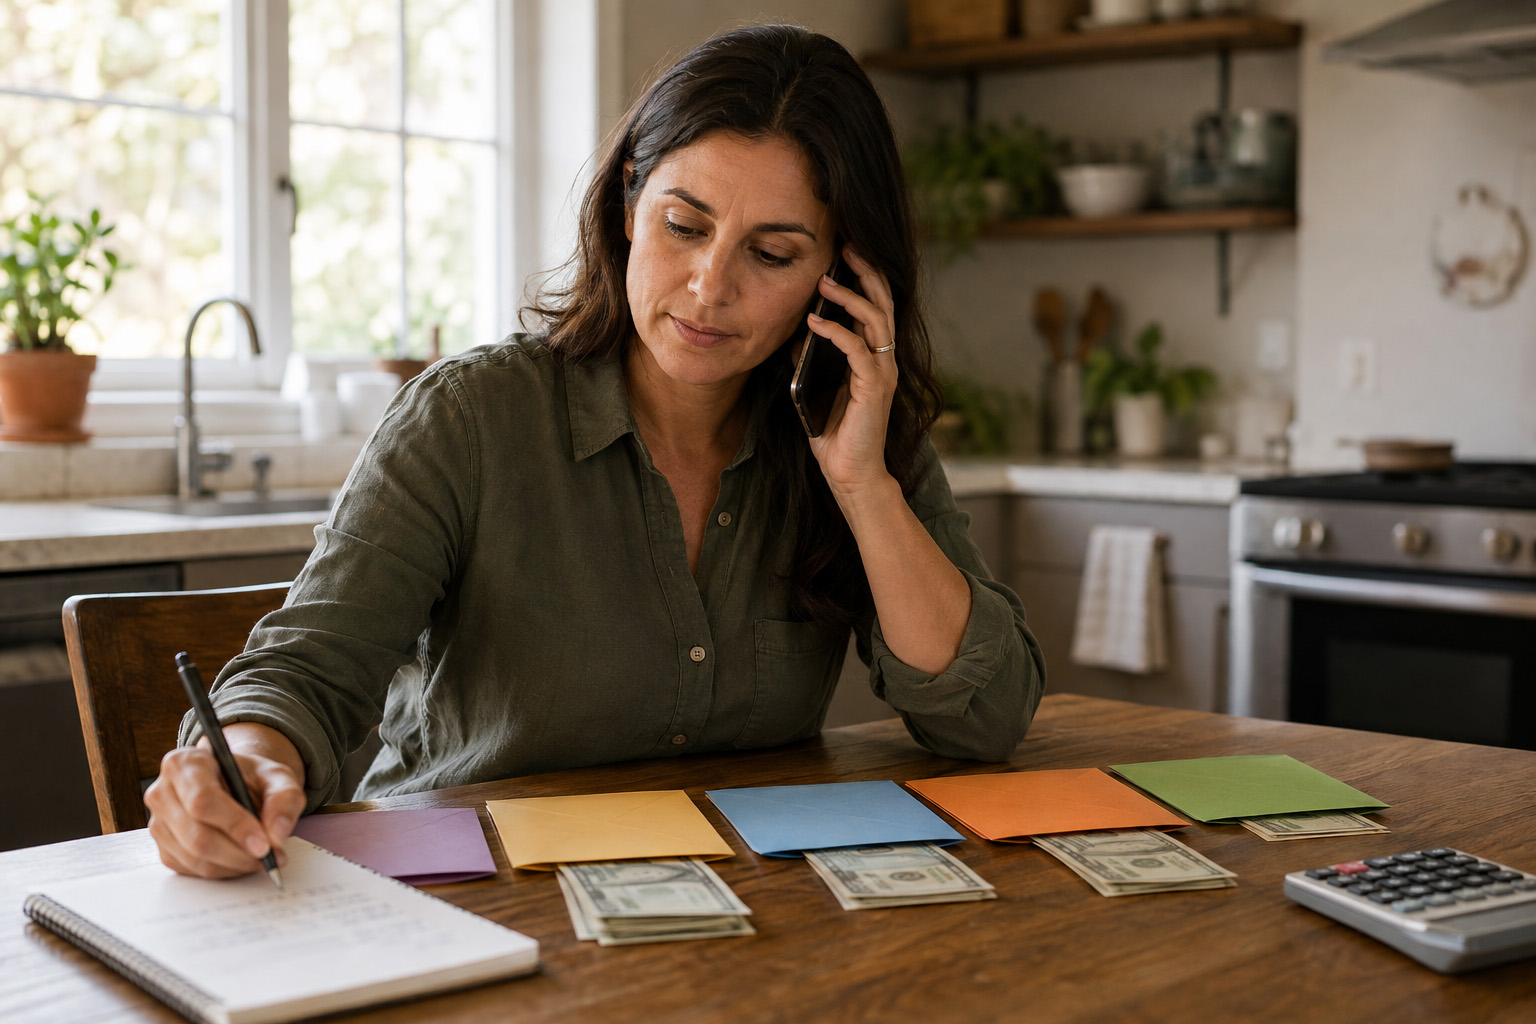
When money feels tight for a few weeks, the order you pay things in matters more than trying to cut everything at once. Sequencing spending is a simple framework that helps you protect essentials, reduce risk, and keep basic services active while you stabilize cash. This article lays out a practical checklist for the next one to two pay periods so you can act with calm and clarity. Use these steps to prioritize payments, communicate with creditors, and create a small buffer that prevents compounding problems.
Assess Essentials
Start by listing fixed obligations and immediate essentials that have high consequences if missed. Focus on housing, utilities needed for basic living, insurance required for important coverage, and food for the household. Identify due dates and the minimum amounts required to avoid penalties or service interruptions over the coming weeks. Knowing exactly what is critical narrows choices and reduces anxiety when funds are limited.
- Housing: rent or mortgage minimums and late fee dates.
- Utilities: heat, water, electricity, and communication for work or school.
- Insurance and transportation necessary to maintain income.
With essentials mapped, you can see discretionary areas that can be paused or reduced. This clarity helps you prioritize available cash with confidence.
Trim Discretionary Spending
Next, identify recurring outlays and nonessential purchases that can be paused immediately. Subscriptions, streaming services, dining out, and nonurgent deliveries are typical quick wins to free up cash. Redirect those amounts toward the essentials list and any overdue minimums that carry high risk. Make temporary changes explicit so you know what to restart later.
Small daily adjustments add up quickly and make the difference between covering critical bills and falling behind. Treat this as a temporary reallocation rather than a permanent sacrifice.
Reschedule and Communicate
Contact service providers and lenders to explain a short-term tight period and request a simple accommodation. Many companies offer brief grace periods, adjusted payment dates, or small payment plans when you ask proactively. Prioritize calls where missed payments create outsized consequences, and document any agreements in writing. Communication reduces late fees, protects credit, and buys you time to rebuild.
Keep a list of who you contacted and the new terms you negotiated. That record prevents surprises and supports follow-through when funds arrive.
Rebuild a Small Buffer and Track
Once the immediate cycle stabilizes, aim to set aside a modest buffer equal to a few days’ essential spending. Even a small emergency cushion prevents rollover stress and reduces the need to reorder priorities each month. Track inflows and outflows during this period so your next sequencing decisions are informed by real numbers rather than assumptions.
Consistent monitoring makes sequencing easier over time and helps you spot patterns that deserve longer-term adjustments. Treat the buffer as a short-term project with measurable steps.
Conclusion
Sequencing spending gives a clear, low-friction path through short tight periods by protecting essentials, pausing nonessentials, and communicating with creditors. A few focused decisions today can prevent larger problems tomorrow and create breathing room for rebuilding. Use this checklist to act deliberately and regain financial control within a couple of pay cycles.