
Introduction
Keeping credit healthy doesn’t require a complex plan; a few clear workflows deliver more reliable results. By standardizing the small, repeatable actions you take each month—like reconciling balances and confirming scheduled payments—you reduce mistakes and create measurable momentum toward better scores. This article outlines a simplified approach to monitoring accounts, managing utilization, handling errors efficiently, and setting realistic targets that match your cash flow. Use these steps as a base and adapt them to the cadence that fits your priorities so progress stays achievable and sustainable.
Why simplify your credit workflow
Complex credit systems are often abandoned because they feel overwhelming and time consuming, which undermines long-term results. A streamlined process focuses on a few high-impact tasks and sets them on a predictable schedule so actions happen without daily decisions. Identify the two or three account behaviors that move the needle for your score—on-time payments, utilization limits, and accurate reporting—and prioritize those. A repeatable cycle reduces decision fatigue, helps you spot anomalies more quickly, and makes progress easier to measure.
Start small and document what works; consistency builds credibility with lenders and your own finances. Treat the workflow as an experiment you refine quarterly rather than a one-time fix.
A monthly checklist to keep habits consistent
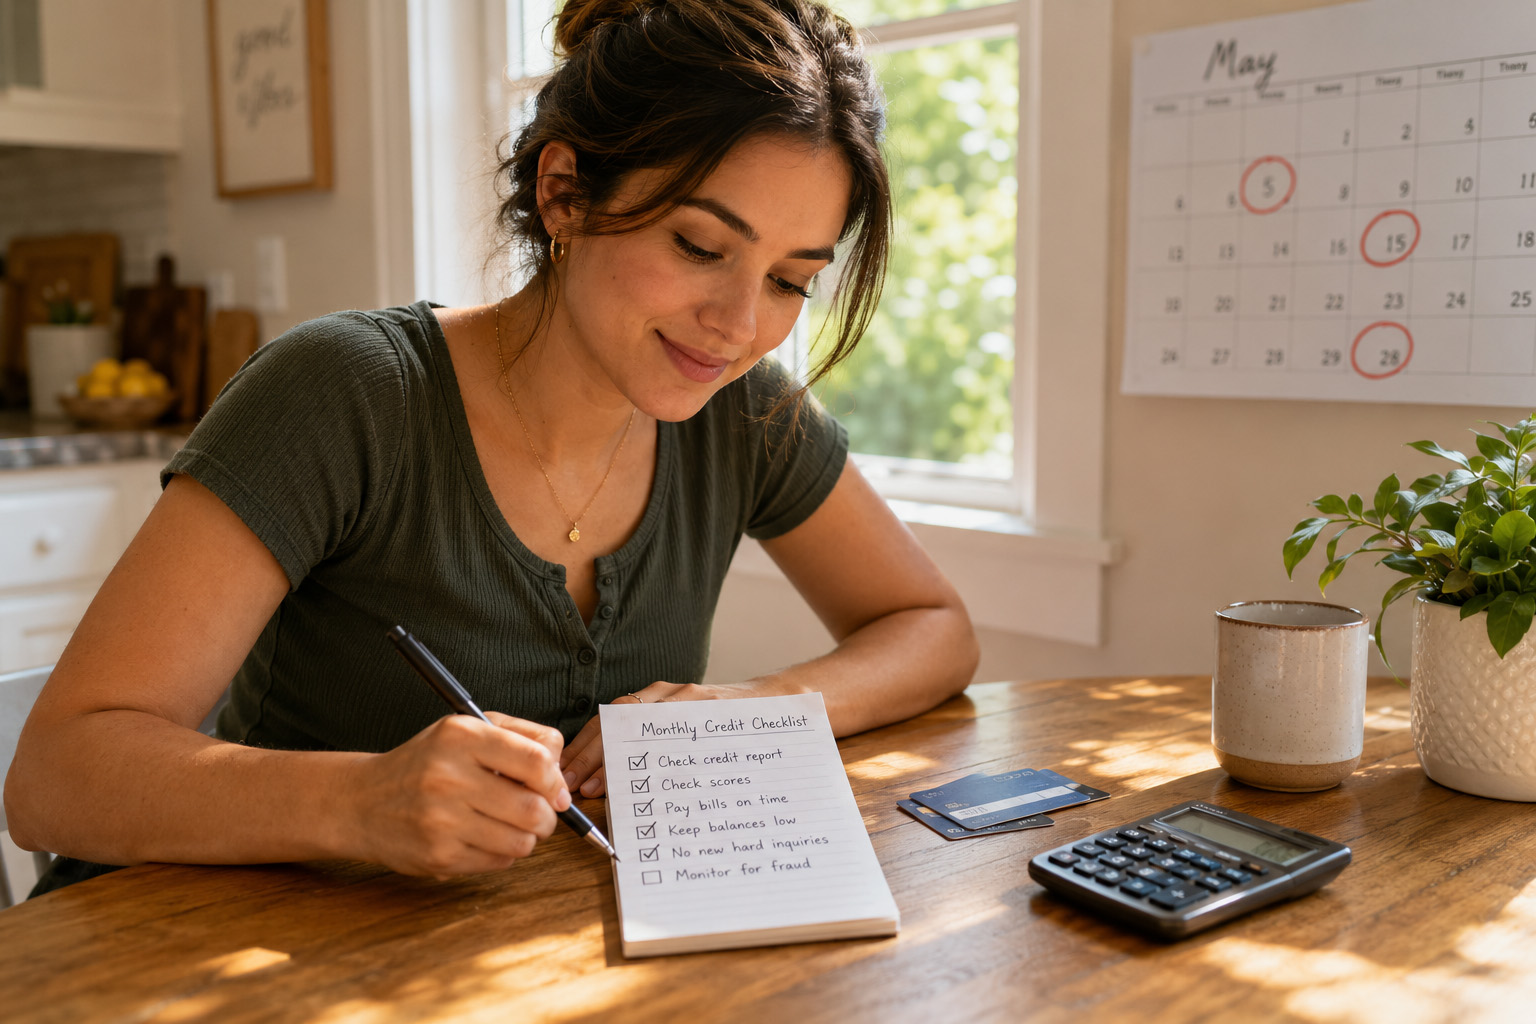
A concise monthly checklist turns vague intentions into exact actions you can complete in under an hour. Include tasks such as verifying automatic payments, reviewing statement balances, calculating utilization by card and overall, and scanning credit reports for unfamiliar activity. Automate reminders, use calendar prompts, and consider low-cost monitoring tools that send soft alerts for changes so you stay informed without overchecking. Keeping everything in one place—a spreadsheet or secure notes app—lets you compare month-to-month progress and spot trends.
- Verify on-time payments and autopay settings before due dates.
- Calculate utilization and adjust statement timing.
- Flag new inquiries, unfamiliar accounts, or unexpected balance increases.
- Log any disputes, creditor communications, and expected resolution dates.
Completing this short routine consistently prevents surprises and turns maintenance into a habit rather than a chore. Over time, small corrections compound into measurable score improvement.
Responding to problems without derailing progress
When setbacks occur, the response matters more than the setback itself; a calm, documented approach limits damage. Dispute inaccuracies promptly using proper reporting channels, but continue prioritizing current payments to avoid new late marks. If cash flow becomes tight, contact creditors to discuss hardship options that may limit reporting harm, and keep records of any agreements. Use setbacks to refine your workflow so the next month is smoother and less risky.
Treat problems as learning opportunities and adjust the checklist to prevent repeats. Maintain momentum by celebrating consistent on-time payments and reduced utilization milestones.
Conclusion
Keep workflows simple, scheduled, and measurable to make consistent progress without burnout. Small monthly habits and timely responses to issues compound into meaningful credit improvements. Start with one change and build from there.