
Introduction
Improving your credit score is less about dramatic fixes and more about consistent habits you can maintain. Small, reliable actions reduce risk while producing measurable results over months. This approach focuses on payment routines, balance management, and smart account use. The goal is steady progress that supports long-term financial options.
Start with a Reliable Payment Rhythm
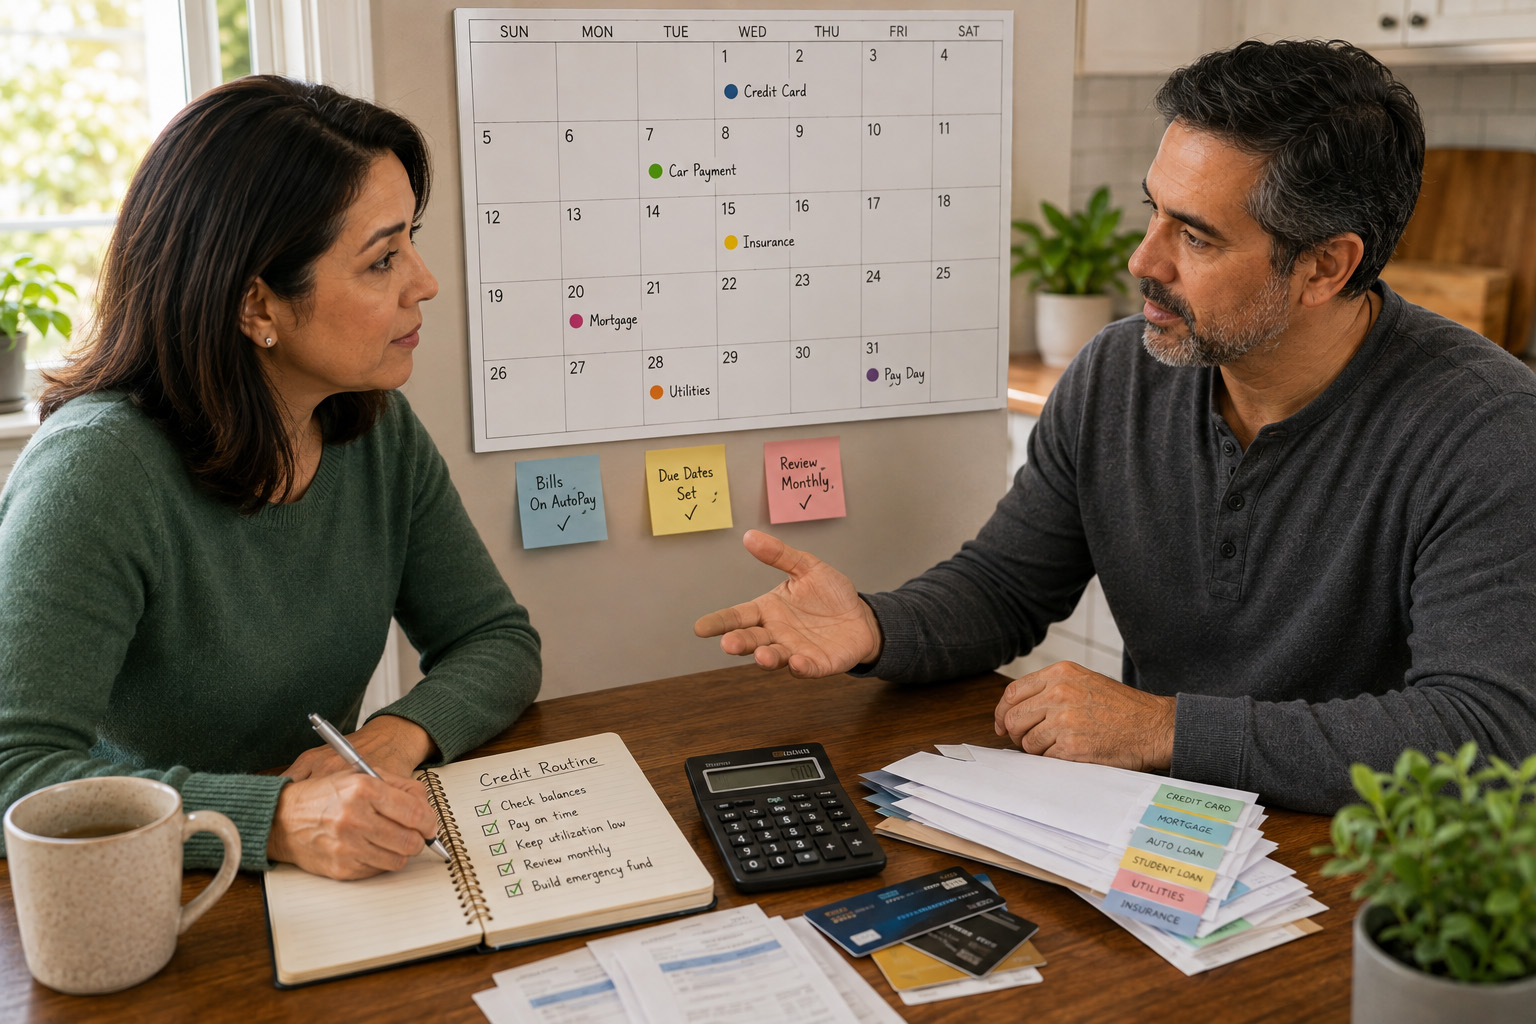
Timely payments are the foundation of credit health and typically carry the most weight in scoring models. Set up automated payments for at least the minimum amount and align due dates with your cash flow to avoid missed bills. If automation feels risky, create calendar reminders and check statements weekly to confirm activity. Treat on-time payments as a nonnegotiable part of your monthly routine.
Consistent payment behavior signals stability to lenders and reduces late fees. Even small late occurrences can linger on reports, so prevention is far more efficient than repair. Make this step your baseline before pursuing riskier strategies.
Manage Balances and Utilization
Credit utilization — the ratio of balances to available limits — is a key lever you can control quickly. Aim to keep utilization below commonly recommended thresholds by paying down high balances and redistributing charges across cards when appropriate. Monitor statement balances and consider mid-cycle payments if balances spike. Reducing utilization can produce visible score improvements without new credit inquiries.
Prioritize paying down accounts with the highest utilization or highest interest rates to both lift scores and reduce cost. Small, regular payments often outperform infrequent large ones because they keep reported balances lower consistently.
Use Accounts Strategically and Monitor Reports
Maintaining a mix of older, well-managed accounts supports credit history depth, while selective new credit can help when timed correctly. Avoid closing old accounts without considering the impact on average account age and available credit. Regularly review your credit reports for errors or unfamiliar accounts and dispute inaccuracies promptly. Monitoring helps you catch identity issues early and keeps your strategy aligned with what the scoring models actually see.
Consider tools that provide alerts for hard inquiries, large balance changes, or new accounts so you can respond quickly. Strategic account use combined with vigilant monitoring protects progress and allows small course corrections before problems grow.
Conclusion
Building credit strength is a long game built on reliable, repeatable behaviors. Prioritize on-time payments, sensible balance control, and careful account management to create steady gains. Over time, these habits compound into more favorable borrowing options and financial flexibility.