
Introduction
Improving credit is less about dramatic moves and more about steady, sustainable choices. Small commitments repeated over time build a cushion of reliability that scores reward. This article outlines practical daily and monthly habits to protect and grow credit standing. Use these ideas to create a manageable routine that fits your finances and goals.
Start by picking a few actions you can maintain, then layer additional practices as they become comfortable. Consistency matters more than perfection, and modest improvements compound into measurable progress.
Why consistent small habits matter
Credit scoring models favor predictable, responsible behavior, so regular habits create clear signals of stability. Making on-time payments, keeping balances low, and avoiding frequent account openings all contribute to a more resilient profile. Each small action reduces volatility and lowers the chance of sudden score drops. Over time these behaviors become your financial fingerprint, attracting better borrowing options and lower costs.
View habits as insurance: they protect against setbacks and create opportunities for gradual improvement. Commitments that cost little effort can yield outsized benefits when repeated consistently.
Payments, utilization, and the basics
Timely payments are the single most important routine to maintain, followed closely by managing credit utilization. Aim to pay at least the full statement balance when possible, or set up automated minimums to avoid late marks. Keep revolving balances below about 30% of available limits, and lower still for faster gains. Small overpayments during busy months reduce balances and ease future payment pressure.
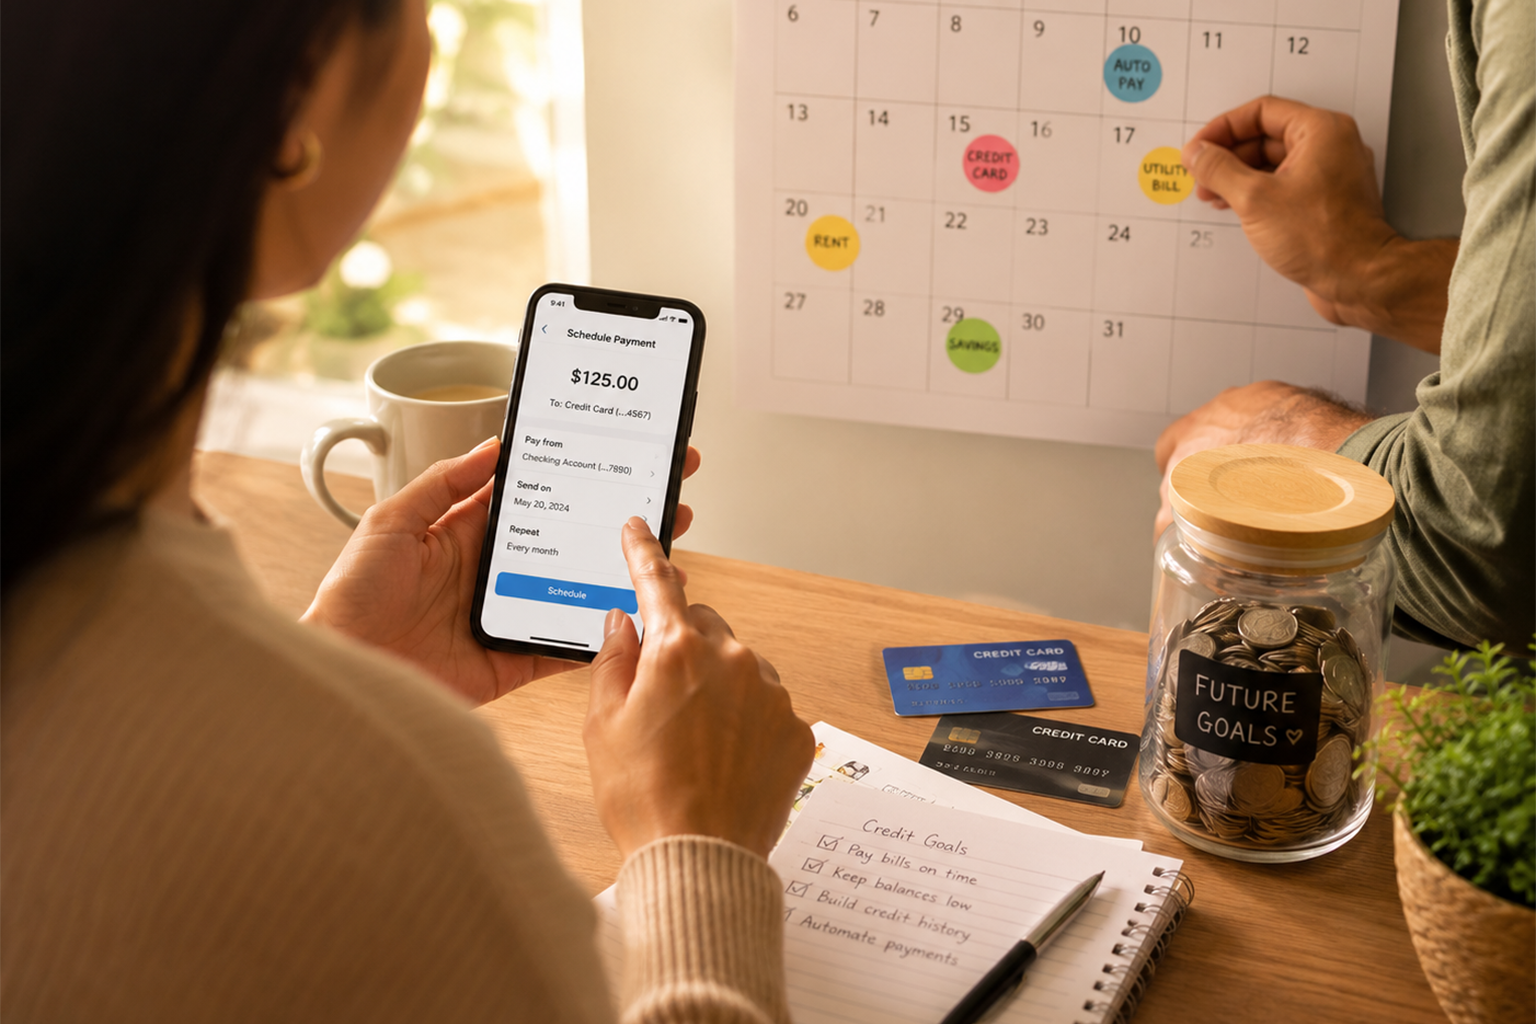
- Set calendar reminders or autopay for due dates.
- Make multiple small payments each month to lower reported utilization.
Simple tweaks to how and when you pay can shift reported metrics in your favor. Focus on consistency before complexity.
Account management and credit mix
Maintaining a manageable set of accounts for different needs reduces risk and supports a healthy age-of-credit history. Keep older, well-behaved accounts open rather than closing them, which preserves length of history. Use installment and revolving products responsibly to show balanced credit use without overextending. Thoughtful diversification, not rapid expansion, is the goal.
When considering new credit, evaluate necessity and timing carefully. Adding accounts can help over time but should align with broader financial plans.
Monitor, recover, and adapt after setbacks
Regular monitoring catches errors and unexpected changes early, letting you respond before small issues become large problems. Dispute inaccuracies quickly and prioritize curing delinquencies to limit long-term damage. If recovery is needed, focus on affordable, consistent progress rather than score-chasing tactics. Rebuilding takes time but is predictable with steady effort.
Create a short recovery plan with monthly targets and celebrate incremental wins. Persistence and adaptive tweaks keep momentum going through the process.
Conclusion
Small, repeatable commitments protect and gradually build credit resilience. Prioritize timely payments, low utilization, and mindful account management as core habits. Over months and years, those modest routines deliver meaningful, lasting improvement.