
Introduction
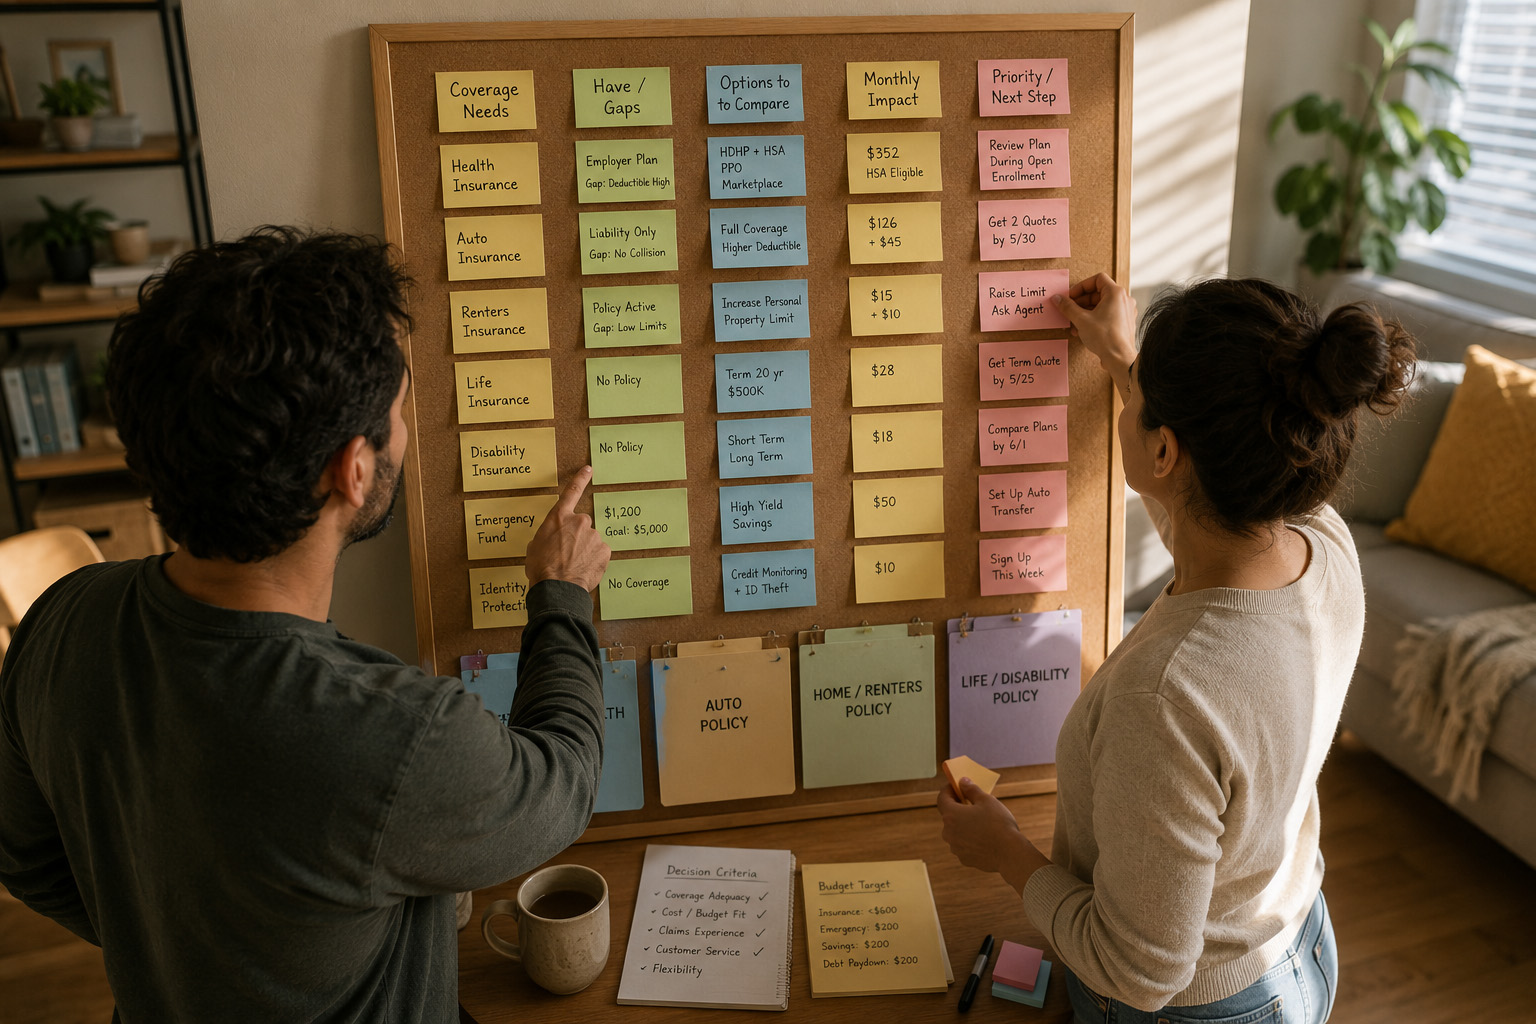
Insurance choices can feel overwhelming when budgets and risks compete for attention. A clear, repeatable method to evaluate needs helps you make confident policy decisions. This article outlines a practical approach that balances probability, impact, and recovery costs. Use these steps to focus coverage where it will matter most every time.
Evaluate Your Exposure
Start by mapping the risks you face and the potential financial consequences of each. Consider likelihood and severity: small frequent losses differ from rare catastrophic events. Also note shared household exposures like property, vehicles, health, and income sources. Quantifying worst-case costs helps set logical priorities rather than emotional reactions.
A concise risk inventory becomes the foundation for policy choices. Keep it updated as life changes and needs evolve.
Rank Coverages by Impact and Recoverability
With exposures listed, rank coverages by how much a loss would disrupt finances and how hard it would be to recover without insurance. Prioritize protections that would cause long-term harm or bankruptcy, such as income replacement or liability that could wipe savings. Lower-priority items are those you could self-insure or replace over time. This ranking steers limited premiums to the largest risks.
The ranking is a decision tool, not a mandate; individual tolerance matters. Revisit the order when major life events occur.
Practical Budgeting and Trade-offs
Translate priorities into a realistic premium budget and explore trade-offs like higher deductibles, limited riders, or bundling discounts. Consider how much you can self-insure — for instance keeping an emergency fund to cover minor home repairs instead of paying premium for full replacement. Use limits and endorsements to tailor coverage rather than buying blanket policies. Comparing policies on price and claims service helps avoid false savings.
Document the choices and expected out-of-pocket costs for transparency. This makes it easier to justify changes during renewals.
Implementing Changes and Regular Review
Once priorities and budget choices are clear, adjust policies in a controlled way: increase limits where risk is highest, add specific riders for uncovered exposures, or consolidate providers for simplicity. Always check exclusion language and waiting periods before making changes. After implementing, track premiums and any claims experience to validate decisions. Set a recurring review schedule tied to life events or annual renewals.
Small, periodic adjustments usually outperform occasional sweeping overhauls. Keep records to show why choices were made.
Conclusion
A practical, repeatable approach to insurance helps you protect what would hurt most financially. By evaluating exposure, ranking by impact, and aligning premiums with your budget, you can make informed trade-offs. Regular reviews ensure your protection keeps pace with life.