
Introduction
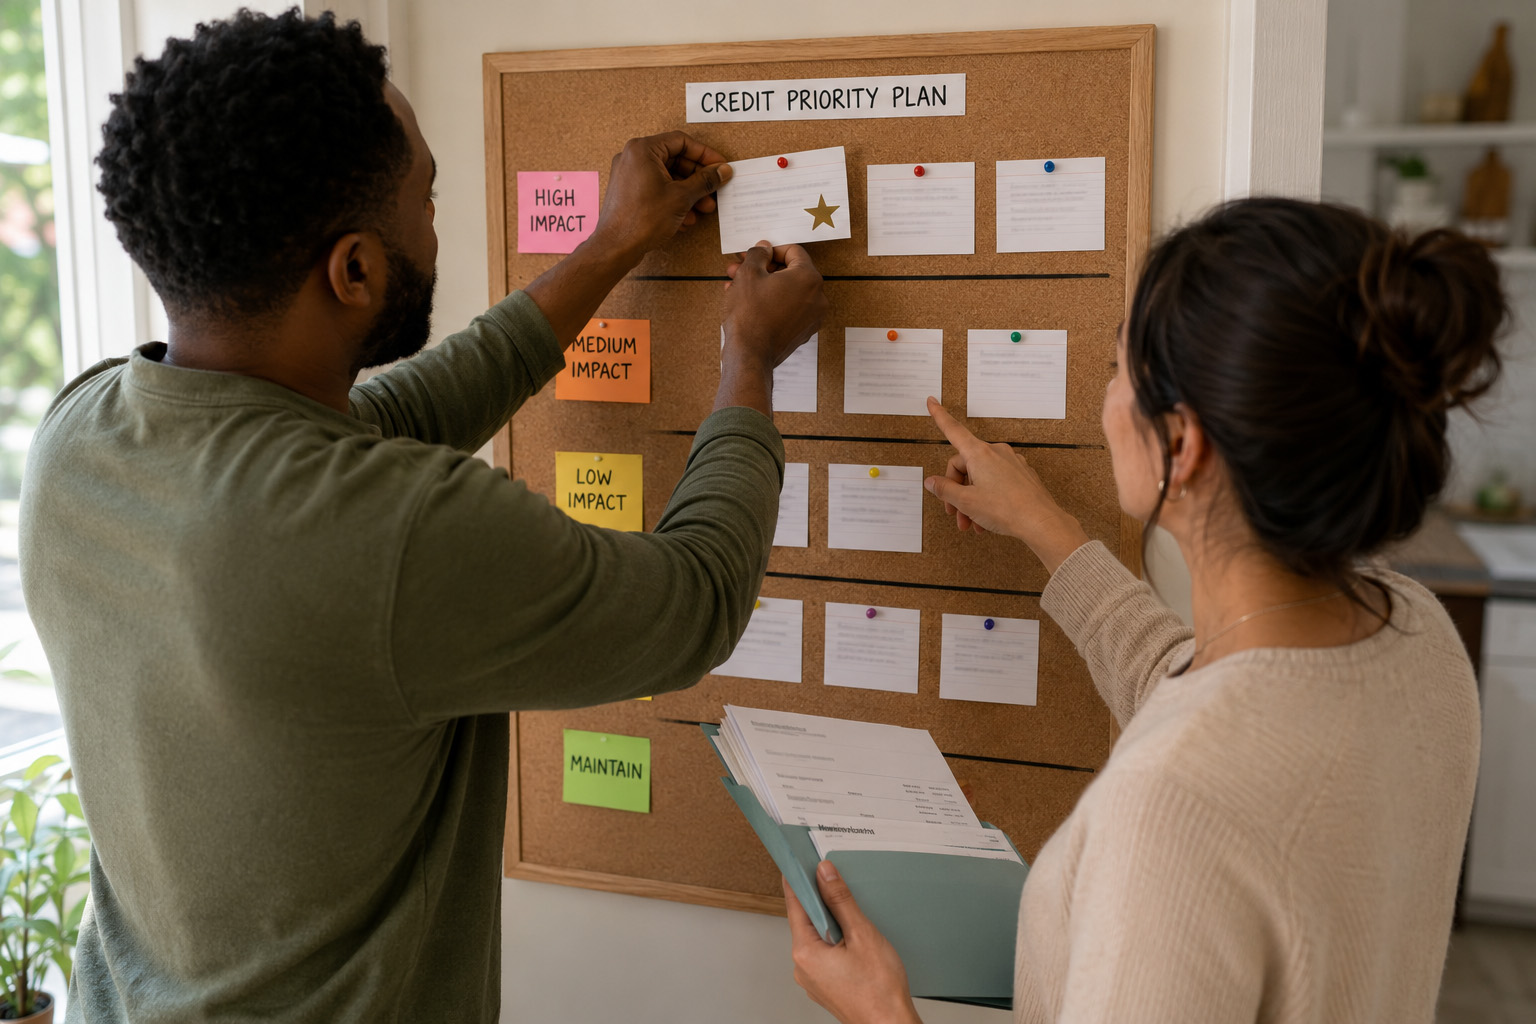
Improving a credit score can feel overwhelming when multiple accounts, balances, and disputes compete for attention. This article offers an impact-first framework to help you choose which credit tasks to tackle first and why they matter. By focusing on actions that deliver the largest measurable effect, you can make steady progress without chasing every metric at once. The goal is a clear, prioritized plan that fits into regular financial habits.
Assess Account Impact
Start by reviewing your credit reports and identifying items that carry the most weight: payment history, utilization, and recent derogatory marks. Look for accounts with high balances relative to limits and any recent missed payments that can be brought current. Also flag errors or identity concerns that could be corrected through a dispute, since a single correction can change multiple score models. Prioritizing by potential score impact helps prevent spending time on low-value adjustments.
Focus first on the few accounts that create the largest negative effect. Addressing a past-due major installment or lowering a credit card balance usually offers faster gains than opening new credit. Keep documentation organized for any disputes and follow up on corrections promptly.
Build an Impact-First Action Plan
Create a short list of high-impact tasks and assign a realistic timeline and owner for each item. Typical high-impact moves include bringing accounts current, reducing utilization on cards with the highest ratios, and negotiating pay-for-delete or goodwill adjustments for recent late payments. Small, consistent changes—like setting autopay for key due dates—reduce the chance of new negatives and reinforce positive payment history. Treat the plan as a practical checklist rather than an exhaustive overhaul.
Sequence actions so that fixes likely to change a score within a month come first, while longer-term strategies like establishing a small installment loan follow. This sequencing keeps momentum and provides measurable wins to sustain the effort.
Monitor Progress and Adjust
Track updates on your credit reports and watch key metrics monthly to confirm which actions are producing results. Regular monitoring helps you detect new issues early and reallocates effort if an action underperforms. Use free or low-cost monitoring tools to receive alerts and to measure utilization and payment behavior trends. Avoid making frequent hard inquiries that could counteract positive progress.
Set quarterly reviews to reassess priorities and add or remove tasks based on measurable changes. Continuous monitoring ensures the plan remains focused on the highest-impact opportunities.
Conclusion
Prioritizing credit tasks by potential impact turns an intimidating problem into manageable steps. A short, sequenced action plan with regular monitoring delivers consistent results. Stick to prioritized moves and review progress to maintain momentum and steady improvement.