
Introduction
Improving your credit score is a process that rewards consistency and planning. Small, well-targeted actions layered over several months produce measurable improvement. Focusing on key drivers such as payment history, credit utilization, and account mix helps prioritize effort. This article outlines a repeatable routine you can use to make steady progress toward a healthier credit profile.
Assess Your Current Credit Position
Begin by pulling your credit reports and a recent score from a reliable source so you understand the starting point. Look for negative items, incorrect balances, and accounts you no longer use; these often reveal the highest-impact opportunities. Track recent inquiries and note the oldest account dates to estimate your credit age and stability. A clear assessment lets you set realistic short-term targets and a timeline for actions.
Once you have a baseline, prioritize issues that will move your score fastest. Address errors and dispute inaccuracies first because removing a reporting mistake can boost your score quickly. Next, list accounts with high utilization or late payments that require immediate attention. This prioritized task list becomes the foundation of your routine.
Make Targeted Payment and Utilization Moves
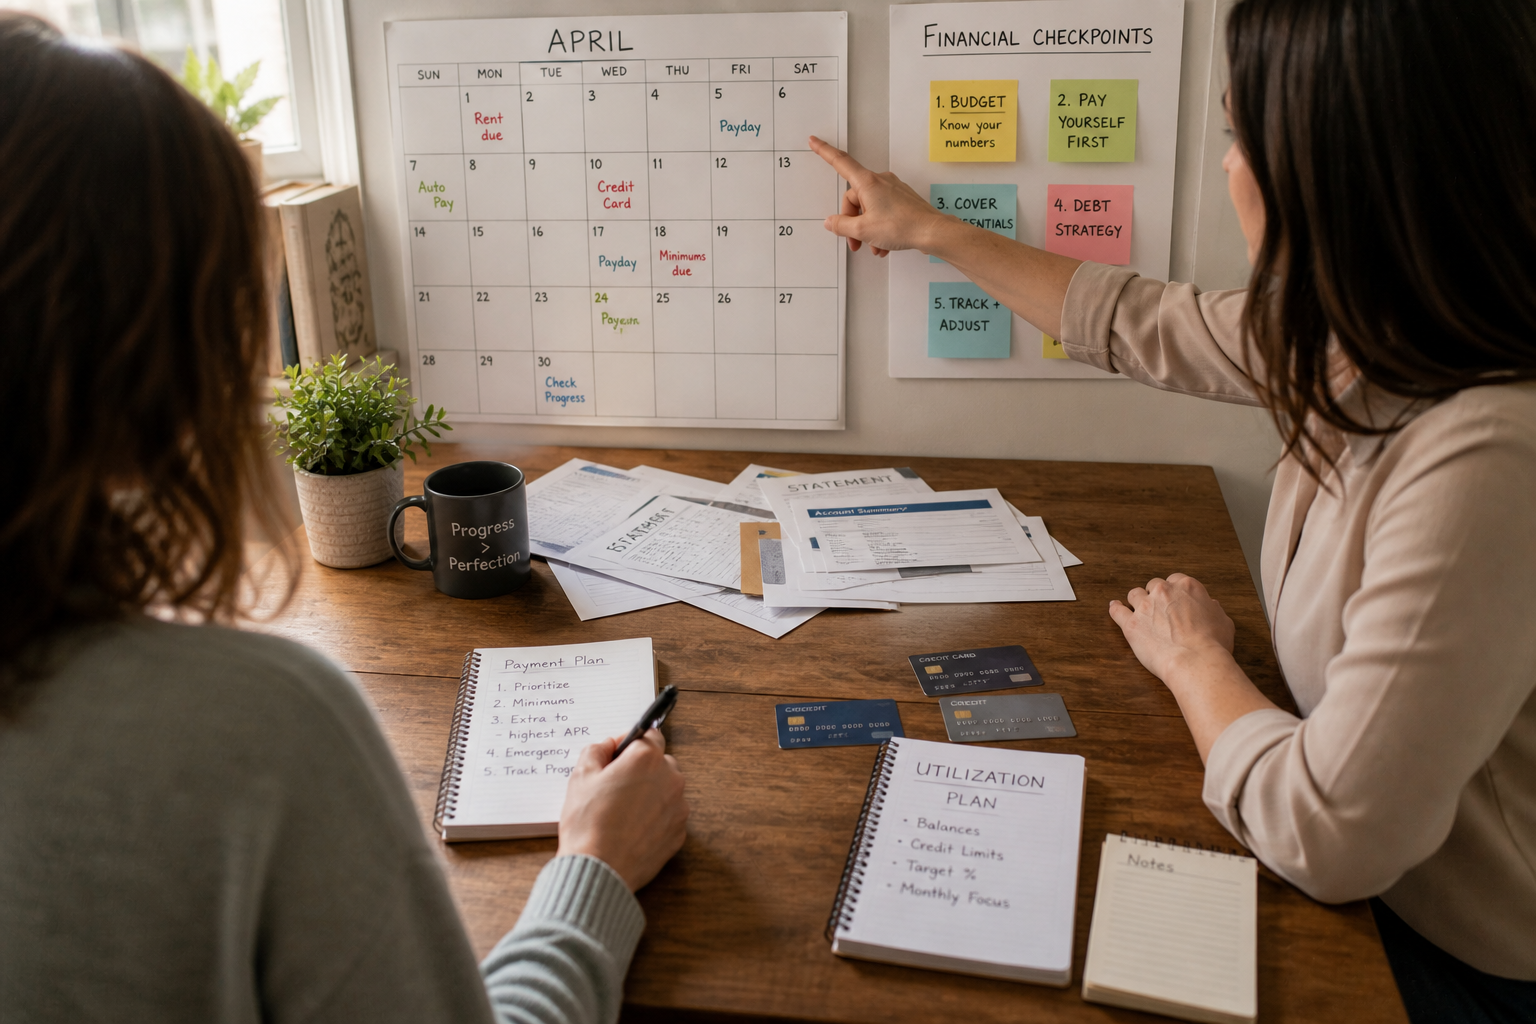
Payment history and how much of your available credit you use are two of the most influential factors in scoring models. Aim to pay all bills on time and, when possible, pay down balances before the statement closing date to reduce reported utilization. If you have multiple cards, consider moving balances or using a small portion of available credit strategically to keep utilization per card below 30 percent. Regularly reducing balances over several cycles signals better risk to lenders.
- Set up automatic payments for at least the minimum due.
- Schedule extra payments before statement dates when feasible.
- Consider targeted balance transfers to lower-rate accounts cautiously.
Consistent payment behavior and lower reported utilization will generally yield steady score improvement. Avoid opening unnecessary new accounts that could generate hard inquiries and shorten your average account age. Small discipline in these areas compounds into meaningful gains.
Maintain Momentum With Monitoring and Habits
Monitoring your credit regularly keeps you aware of changes and helps detect identity issues quickly. Use alerts for new inquiries or changes to key accounts and review your progress against the targets you set in the assessment phase. Build simple habits: reconcile statements weekly, schedule monthly credit-check sessions, and keep a running list of upcoming due dates. These routines make good credit behavior automatic rather than episodic.
Over time, broaden focus to include credit mix and demonstrating diverse, responsible use of credit where appropriate. Revisit your plan quarterly and adjust targets as balances, income, or goals change. A sustainable routine balances proactive actions with patience for scores to reflect long-term improvement.
Conclusion
Adopting a strategic, repeatable routine gives clear steps you can follow to improve credit over months rather than days. Prioritize fixing errors, paying on time, and managing utilization while monitoring progress consistently. Small, steady actions build a stronger credit profile and more financial options over time.