
Introduction
Insurance choices become clearer when you prioritize by real-world consequences instead of product names or sales pitches. Start by identifying what losses would most disrupt your household finances, work capacity, or shelter and then order protections around those exposures. An impact-based ordering method highlights essential coverages, reduces overlap, and channels limited premium dollars where they matter most. This practical stance keeps protection responsive as circumstances change.
Assess risks by likelihood and impact
Begin with a compact inventory of assets, income sources, dependents, and potential liabilities so you understand what’s exposed. For each item, judge two dimensions: how likely an incident is and how severe the financial consequences would be. Use simple, measurable proxies—months of lost income, replacement cost of property, or estimated medical bills—to rank exposures objectively. That ranked list becomes the foundation for which policies to buy first and which gaps can be tolerated temporarily.
Revisit this assessment after major events such as job changes or moving. Maintaining an up-to-date ranking prevents misplaced spending and supports clear insurance decisions.
Secure core protections first
Core protections address losses that are both reasonably likely and potentially ruinous, so they sit at the top of the ordering. These typically include income protection, primary health coverage basics, and sufficient homeowners or auto limits tied to your most valuable assets. Pay attention to policy limits, exclusions, and incident definitions to ensure those protections actually cover the prioritized exposures. Avoid buying numerous small add-ons before securing adequate core limits that would prevent catastrophic shortfalls.
By locking in these essentials, you reduce the odds of an event leading to long-term financial hardship. This approach also clarifies where higher expenditure would be unproductive.
Layer secondary coverages strategically
After core items are covered, add secondary layers for less frequent but meaningful risks; do so only when the incremental cost aligns with the potential payoff. Examples include umbrella liability, excess replacement-cost endorsements, or supplemental disability for specific income risks. Compare premium cost against plausible out-of-pocket exposure to choose wisely between buying coverage or self-insuring. Small regular premiums can be a cost-effective hedge when recovery without insurance would be slow or impossible.
- Umbrella policies for liability above primary limits.
- Replacement-cost endorsements for valuable home contents.
- Top-up disability or critical illness riders tied to income gaps.
Treat these layers as adjustable rather than permanent. Increase protection when exposure grows and reduce it when you have robust reserves.
Implement and review a clear ordering process
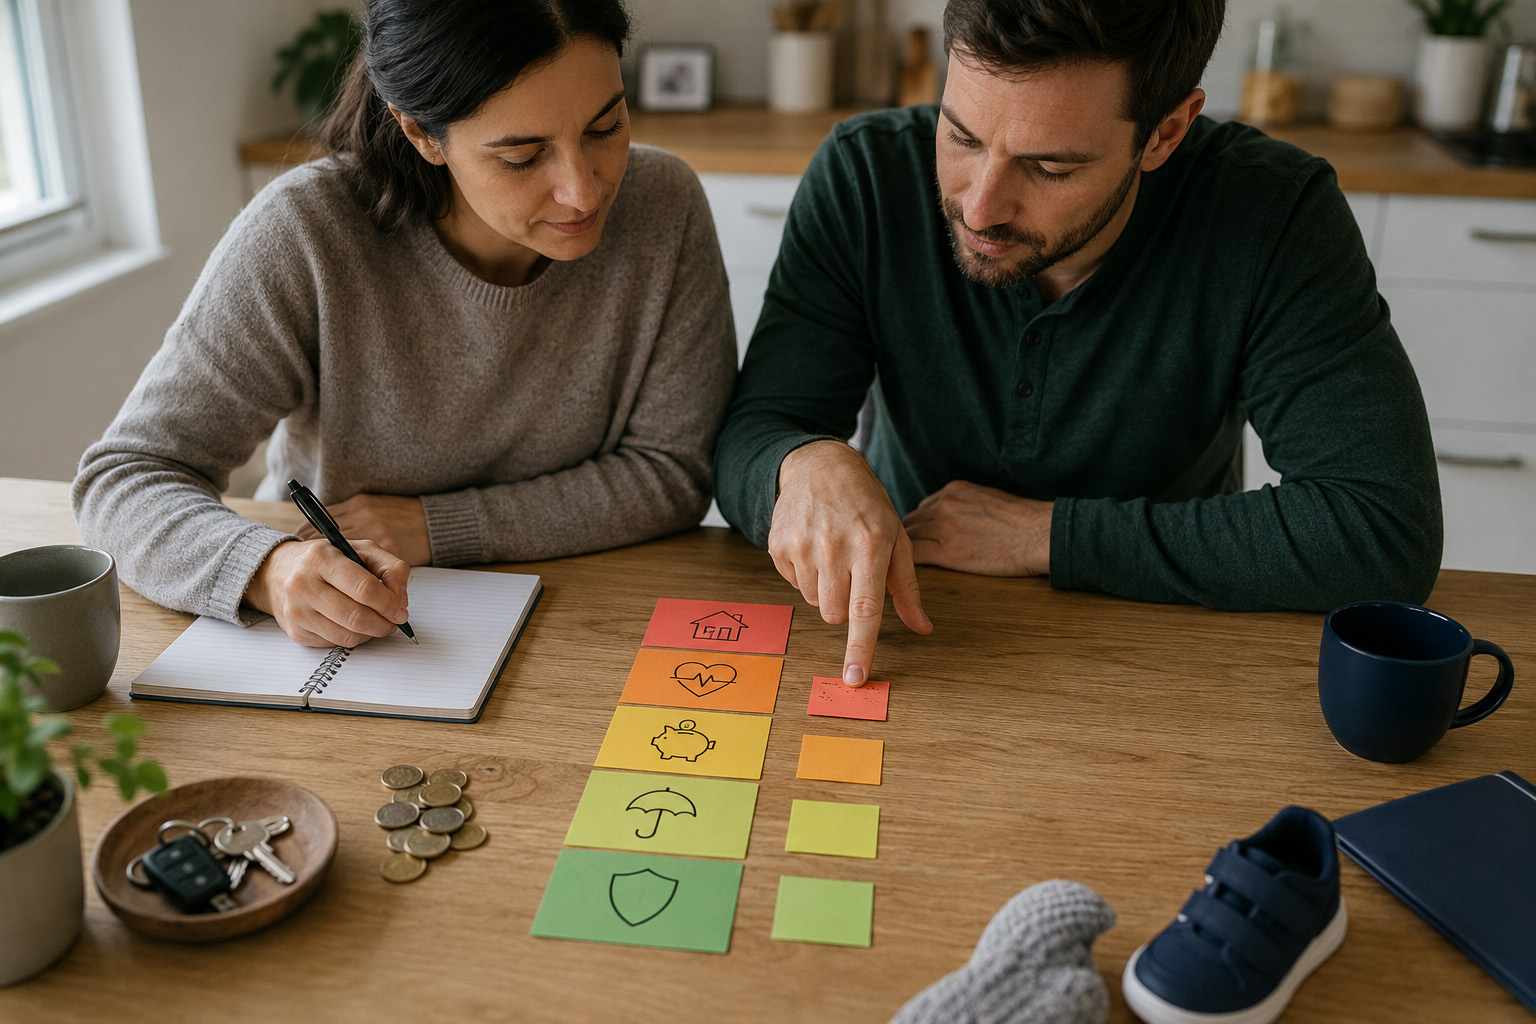
Translate your prioritized list into an actionable plan with target limits, preferred deductibles, and calendar review dates so choices remain intentional. Assign simple tasks: update asset values, confirm beneficiaries, and compare renewal quotes at predictable intervals or after life changes. Use the ordering to allocate budget—cover top-ranked items first, then direct remaining premium capacity toward secondary layers or higher limits. Keeping the plan compact and documented reduces renewal friction and accidental overlap.
- Create a one-page priorities list tied to specific policy thresholds.
- Set an annual review on your calendar and trigger reviews after major events.
- Track premiums against priority tiers when budgeting insurance spend.
Small, regular reviews make the ordering resilient and practical. Over time the process will save money and reduce coverage surprises.
Conclusion
An impact-based ordering lets you protect what would truly derail finances first, then add sensible layers for lower-probability events. Implementing a clear list, target thresholds, and scheduled reviews keeps insurance purposeful and cost-effective. Regular adjustments ensure the plan continues to match your real risks and household priorities.