
Introduction
Unexpected due dates and uneven income are common stressors for everyday finances.
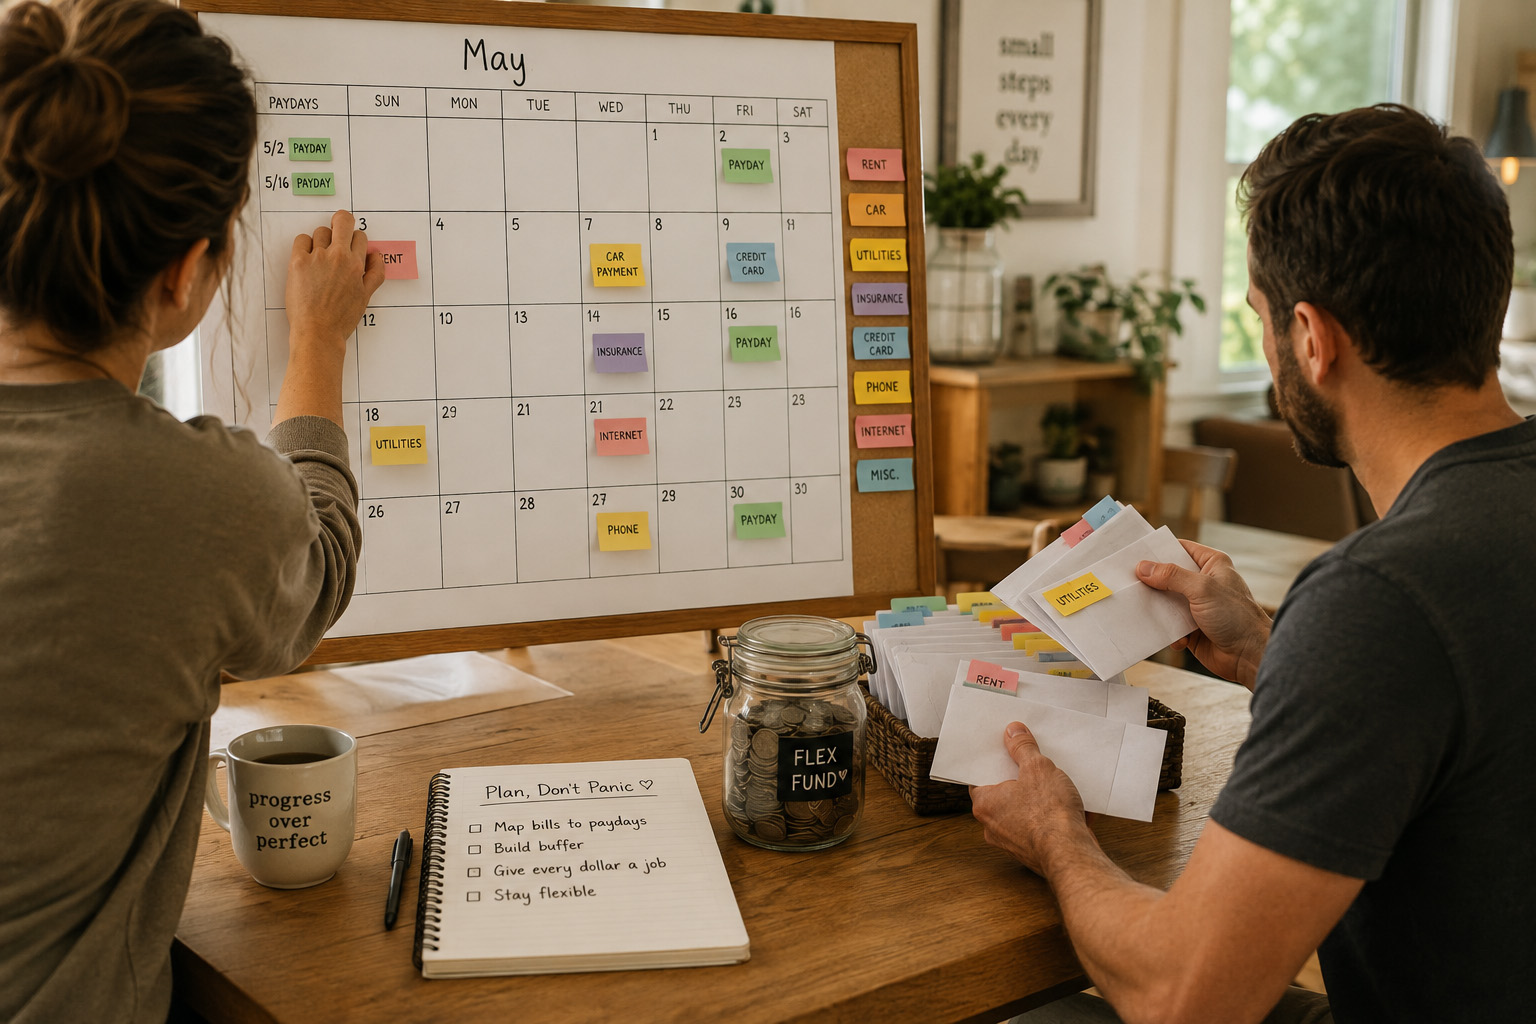
A flexible bill calendar helps you match payment timing to cash flow without complex spreadsheets.
This approach focuses on sequencing, small buffers, and predictable categories for bills.
You can create one in under an hour and adapt it month to month.
Below are practical steps to design and use your calendar effectively.
Why a Flexible Bill Calendar Works
Many people treat bills as fixed deadlines and react when money is short. A calendar that maps bills to your income cycles creates visibility and prevents surprises. It turns reactive scrambling into a predictable routine and reduces late fees and stress. Because it emphasizes timing over elimination, it keeps essentials covered while you adjust discretionary spending.
Adopting a calendar also exposes small mismatches between paydays and due dates that are easy to fix. These small fixes compound into steadier months with less emergency borrowing.
Designing a Simple Calendar
Start by listing recurring bills and their usual due dates, then note your income dates. Shift payment dates where possible and group similar expenses near each income event. Add a modest buffer—aim for one to two days of fixed expenses saved per pay cycle to absorb small timing gaps. Keep the calendar on a single visible page or app so you consult it before spending.
Focus on predictable categories first: housing, utilities, insurance, and basic transportation. Once those align, layer in subscription and variable costs.
Using the Calendar During Tight Weeks
When a week looks tight, consult the calendar before authorizing discretionary charges. Consider short, reversible moves like delaying nonessential subscriptions or pausing automatic transfers to discretionary accounts. Communicate proactively with creditors if alignment still leaves a gap; many providers offer one-time date adjustments or hardship options. Use the modest buffer to smooth the gap while you implement these changes.
Small, timely adjustments prevent cascading problems and keep essential services uninterrupted. The calendar makes those choices less stressful because you can see the trade-offs clearly.
Maintaining and Adjusting the System
Review the calendar monthly and after any income change or major expense. Smooth seasonal variations by increasing the buffer before high-cost months and by prepaying smaller obligations when extra cash arrives. Keep the system simple: one document, regular review, and quick tweaks. Simplicity improves long-term use and prevents the calendar from becoming another neglected tool.
Over time the calendar also reveals opportunities to consolidate dates or negotiate more convenient terms. Small refinements add stability without big sacrifices.
Conclusion
Implement a flexible bill calendar as a low-effort way to reduce surprise shortfalls.
It preserves essentials and gives you time to respond when income varies.
Start small, review monthly, and let the system protect your months.