
Introduction
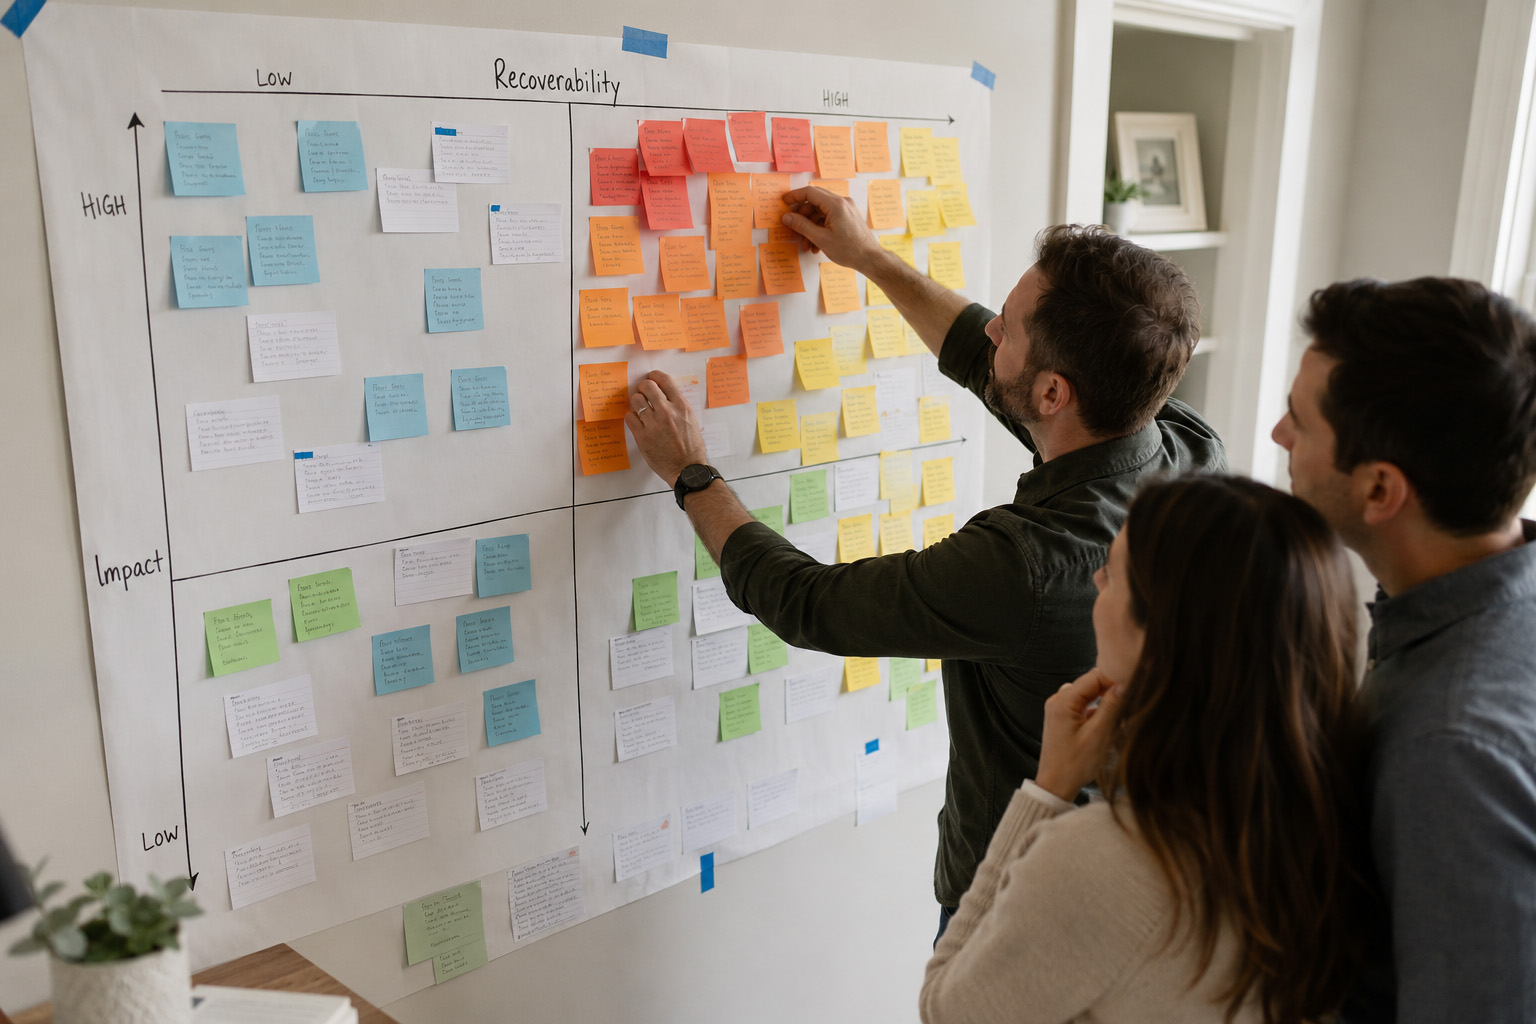
When deciding which insurance policies to buy first, thinking in terms of recoverability and impact helps make clearer choices. Recoverability means how easily you or your household can absorb a loss without insurance, while impact measures the severity of that loss on your finances and wellbeing. Prioritizing coverage that addresses high-impact, low-recoverability events delivers the most protection per dollar. This mindset reduces overlap, focuses spending on real vulnerabilities, and supports a more resilient financial plan.
Define Recoverability and Impact for Your Situation
Start by listing typical risks and asking two questions for each: how likely is this event, and how quickly could you recover financially? Consider savings, emergency funds, access to credit, and community support as elements of recoverability. For impact, estimate the direct costs and related consequences such as lost income or long-term health effects. Combining these perspectives creates a simple matrix to rank priorities instead of relying on sales pitches or policy checklists.
Framing risks this way helps separate true insurance needs from optional conveniences. It also clarifies when self-insurance is reasonable and when transferring risk is essential. Use the matrix as a living document that changes with family size, career stage, and assets.
Prioritize Coverages by Severity and Repair Cost
Policies that protect against catastrophic outcomes with limited personal recovery options should generally come first. Examples include disability or critical illness protection when earnings are the primary asset, and certain liability coverages if an adverse event could wipe out savings. Property insurance becomes more critical as replacement costs rise beyond what you could cover out of pocket. Health-related coverages also rank high when out-of-pocket medical bills could cause long-term financial harm.
This ordering is not universal; it depends on individual exposure and buffers. Review each policy’s limits against plausible worst-case scenarios to see where gaps remain. Priorities shift as you build reserves or pay down concentrated risks.
Use Deductibles and Limits to Balance Cost and Protection
Choosing higher deductibles can lower premiums and is sensible where recoverability is strong. Conversely, for low-recoverability, low-deductible options reduce immediate financial risk. Limit selections should reflect the realistic costs of recovery, not arbitrary figures from marketing materials. Consider umbrella policies or riders to fill gaps efficiently without buying redundant coverage.
Regularly model worst-case scenarios and compare the cost of premiums versus potential out-of-pocket exposure. Small adjustments in deductibles or limits can free budget for higher-priority protections.
Review and Adjust as Circumstances Change
Insurance priorities evolve with changes in income, assets, family composition, and health. Schedule an annual review to update your recoverability assessment and re-rank exposures. Use life events—home purchase, career changes, or dependents’ arrival—as triggers for a deeper reassessment. Keep documentation of decisions so updates remain consistent over time.
Routine reviews prevent drift into overinsurance or dangerous underinsurance. They also make premium increases and market changes easier to absorb strategically.
Conclusion
Prioritize coverages that protect against high-impact losses you cannot recover from easily. Balance cost and protection by adjusting deductibles and limits based on your recoverability. Reassess regularly so your insurance reflects what truly matters to your financial resilience.