
Introduction
Improving a credit score rarely happens overnight; it grows through steady, intentional choices. Small adjustments to how you pay, borrow, and monitor accounts can compound into meaningful gains over months. By focusing on a few measurable behaviors you can reduce risk and produce predictable improvements. This article outlines practical steps you can use on a regular basis to move your score in the right direction.
Assess Your Starting Point
Begin with a clear snapshot of your credit profile and recent payment history. Pull a current credit report and note any late payments, collection accounts, and overall balances compared with available limits. Identify which accounts contribute most to utilization and whether any inaccurate items need dispute. A focused assessment helps you prioritize actions with the highest potential impact.
Once you know where issues live, set two short-term priorities: stop new damaging behaviors and plan targeted fixes. Those priorities create a practical roadmap for the next three months.
Focus on Payments and Utilization
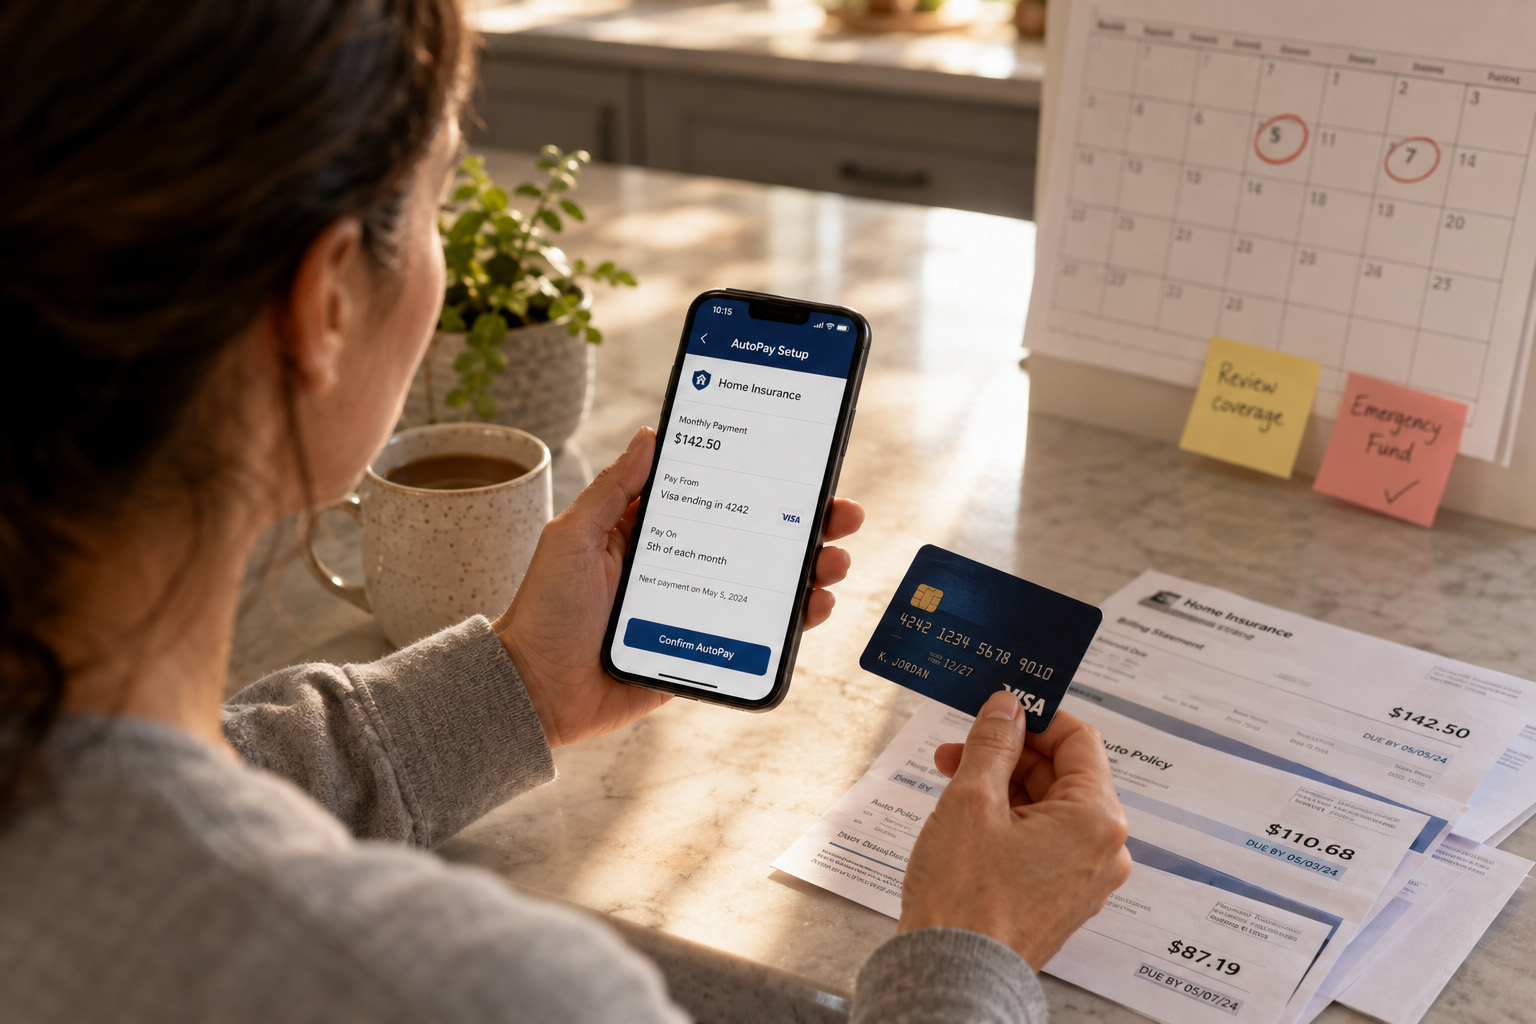
Payment history and credit utilization are among the most influential factors for most scoring models. Make on-time payments nonnegotiable by automating due dates and, if needed, adjusting payment schedules to match income timing. Lower balances relative to limits by paying down cards with the highest utilization first or making multiple payments each month to keep reported balances lower.
- Automate at least the minimum payment to avoid late marks.
- Target credit card balances under 30% of each limit; lower is better.
- Consider small extra payments mid-cycle to reduce reported utilization.
Consistent payment timing and modest reductions in utilization can produce measurable score improvements in a few reporting cycles. Keep tracking progress to reinforce the habit.
Tackle Errors and Build Responsible Diversity
Disputing inaccuracies on your report is often a fast way to remove unjust negatives that drag scores down. File disputes for incorrect late payments or balances and follow up until resolved. At the same time, consider responsibly adding a different account type if your profile lacks variety, such as a small installment loan or a secured account if necessary.
Balancing correction and careful account additions helps both clean and strengthen your profile. Stay patient—credit models reward steady, verified behavior over time.
Conclusion
Small, consistent adjustments to payments, utilization, and reporting habits create reliable credit progress. Prioritize clarity at the start, automate what you can, and correct errors promptly to maintain momentum. Over months, these steady actions add up to sustainable score improvement.