
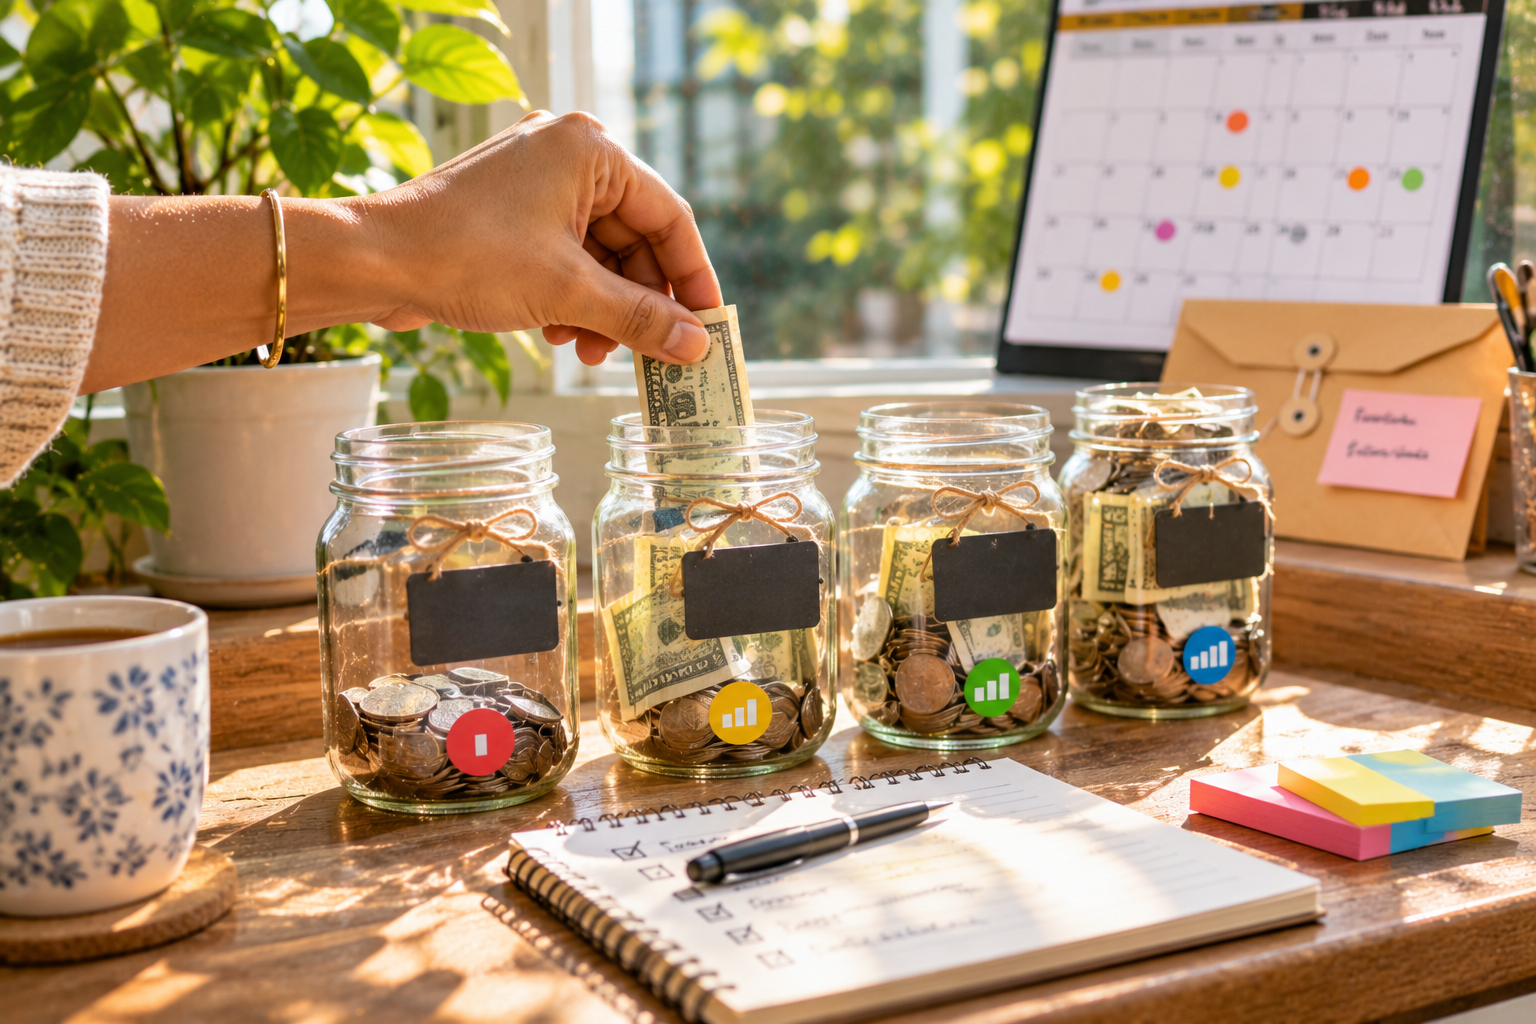
Holding a handful of separate cash buckets makes saving feel less like a single uphill climb and more like small, manageable projects. Each bucket is a named purpose — a short-term bill, a planned purchase, or a tiny surprise fund — and that clarity changes how you spend and save. When you see money earmarked, it’s easier to resist impulse pulls and celebrate incremental progress. This piece lays out a practical approach to create, fund, and keep those buckets working for you.
Why splitting cash into buckets works
Psychologically, labeled savings reduce decision friction: when money is assigned, it stops competing with everyday spending. Financially, buckets help you avoid the trap of scraping from an emergency pile for predictable costs, so surprises don’t wipe out planned expenses. Operationally, a few targeted buckets let you prioritize without juggling dozens of accounts or apps. You’ll get clearer visibility into what’s coming due and where small changes can speed progress.
Keeping goals concrete also makes tracking simple; you know exactly how close each bucket is to its target. That visibility turns abstract willpower into specific actions you can adjust weekly or monthly.
How to choose the right buckets
Start with three to five buckets that match your calendar: an upcoming bill or subscription, quarterly or annual expenses like insurance or registration, an appliance or home repair fund, and a small discretionary buffer. Give each bucket a clear name and a target amount so contributions feel purposeful rather than vague. For timing, set deadlines or rhythms — for example, fund a vacation bucket monthly and a repair bucket whenever you have spare cash.
Keep bucket goals realistic and revisit them quarterly to avoid overcomplication. If a bucket sits idle for months, consolidate it with another or change its purpose.
Simple ways to fund and maintain buckets
Automate where possible: schedule small transfers after payday or round up purchases into a savings app if you use one. When automation isn’t available, treat transfers like bills by adding them to your monthly checklist. Use windfalls — tax refunds, bonuses, gifts — to accelerate bucket targets rather than entirely reworking your budget. And allow a small flexible bucket for miscellaneous shortfalls so your system can absorb surprises without collapsing.
Review balances monthly and tweak contribution amounts incrementally instead of making abrupt changes. Over time, this steady attention keeps the system useful and stress-free.
Conclusion
Purposeful buckets stop saving from feeling nebulous and turn goals into achievable steps. Start small, automate contributions, and keep routines simple so the system fits your life. With regular reviews you’ll maintain momentum and protect both planned expenses and unexpected needs.