
Introduction
Reading your credit report carefully is the first practical step toward improving your credit standing. Many consumers overlook small inaccuracies that can quietly lower scores or limit borrowing options. This article explains how to interpret common entries, identify errors, and take effective steps to correct them. With a focused approach you can turn a confusing report into a clear action plan.
What a Credit Report Shows
A credit report compiles account histories, payment records, balances, public records, and inquiries from lenders. Each section contributes differently to your score: payment history and balances typically carry the most weight. Understanding which entries are factual and which are summaries helps you spot what matters. Learn where to find account numbers, dates, and the reporting lender for faster follow-up.
Checking the structure of the report makes disputes simpler and faster. When you know what each line item means, you can prioritize the entries that most affect your score.
Spotting Common Errors
Common mistakes include wrong balances, accounts that aren’t yours, duplicate entries, outdated negative marks, and incorrect personal information. Identity mix-ups and data entry errors often lead to accounts appearing under the wrong name or social details. Even small formatting errors can delay resolution if they obscure the core issue during a dispute. Regularly comparing statements and lender records to the report will expose inconsistencies quickly.
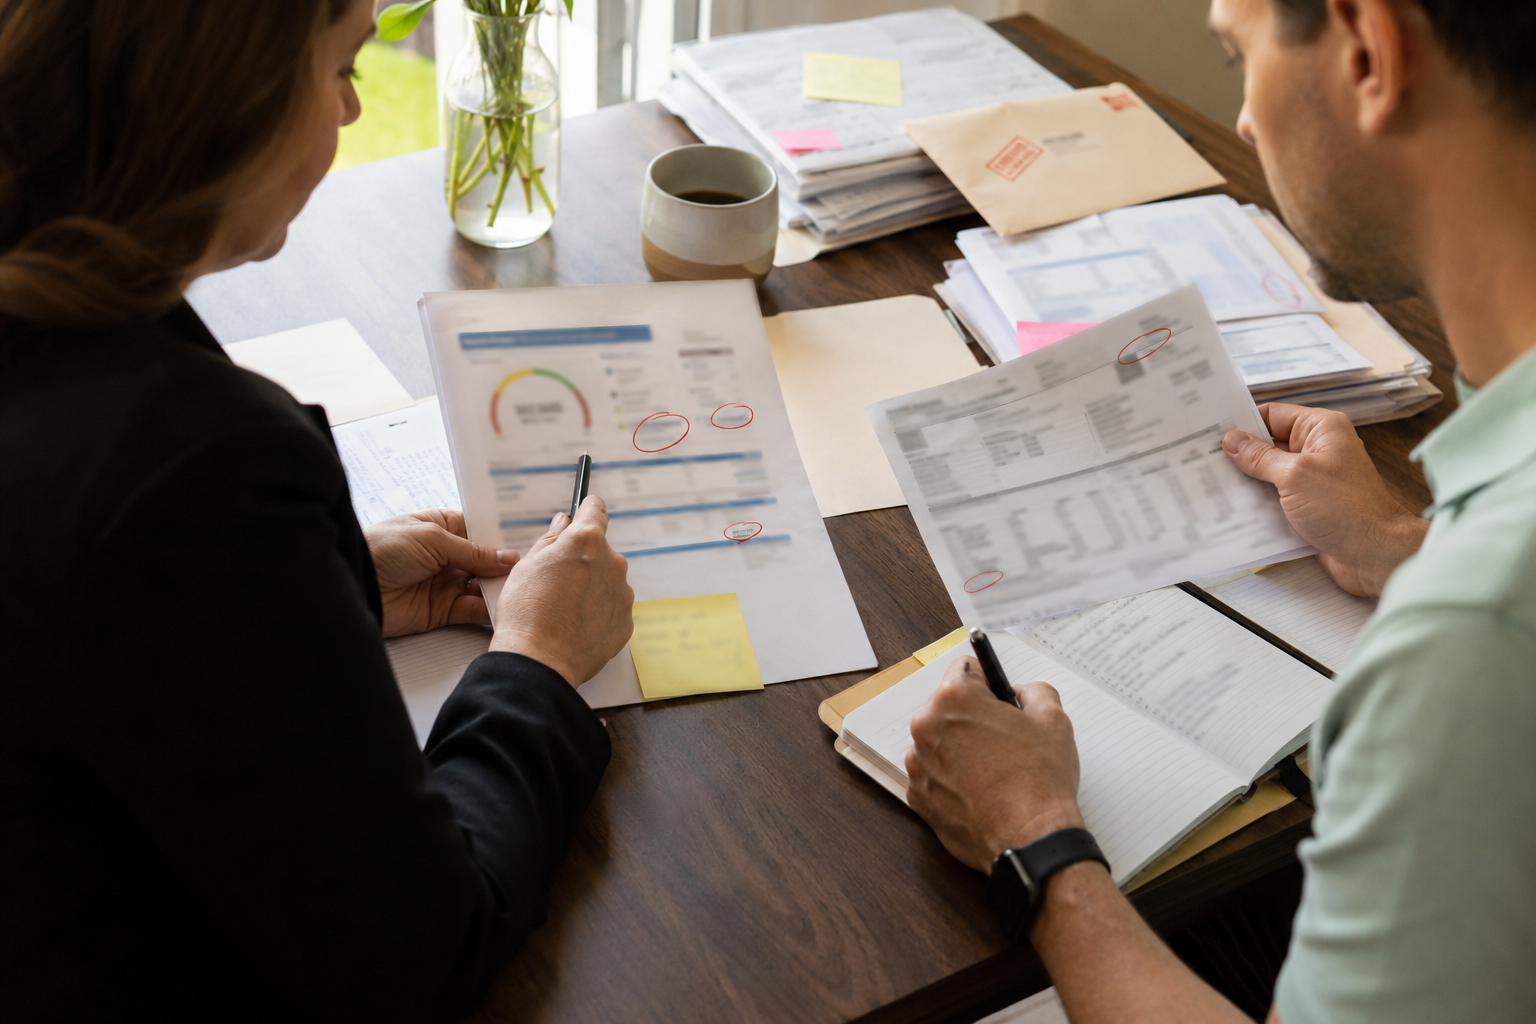
Taking notes about discrepancies and copying supporting documentation makes your case stronger. Accurate documentation reduces back-and-forth and speeds up corrections.
How to Dispute and Correct Errors
Prepare a clear dispute that identifies the exact error, explains why it’s incorrect, and cites supporting evidence such as billing statements or identity documents. Submit disputes online or by certified mail to the reporting agency and the creditor that provided the information. Keep records of each communication, including dates, agent names, and confirmation numbers.
- List the disputed items and attach copies of supporting documents.
- Send disputes to both the credit bureau and the creditor for faster resolution.
- Follow up if there is no response within the expected timeframe.
Most disputes are resolved within a few weeks, but persistent or complex issues may take longer. Staying organized and patient helps ensure corrections are applied properly.
Building from a Clean Report
After resolving errors, focus on consistent on-time payments, sensible credit utilization, and maintaining a mix of accounts. Regular monitoring helps catch new issues early and prevents small mistakes from becoming lasting problems. Use alerts and annual reviews to stay proactive without obsessing over daily fluctuations. A clean report makes it easier to pursue favorable loan terms and financial opportunities.
Routine reviews and measured credit habits will sustain improvements over time. Treat a corrected report as the foundation for stronger long-term credit health.
Conclusion
Careful review of your credit report reveals actionable errors that you can dispute and correct. Maintaining documentation and following up keeps the process moving efficiently. Once corrected, steady credit habits help preserve those gains into the future.