
Introduction
Make Insurance Decisions Around Repairing Life Quickly
Insurance often feels theoretical until a disruption forces you to rebuild daily routines and finances. Many people choose policies based on price, anecdotes, or broad coverage lists that do not reflect what actually speeds recovery. Thinking first about the things you must repair fast — housing, income, transportation, or essential health care — changes how you rank options and set deductibles. This recovery-first perspective helps you prioritize coverage that restores stability rather than merely reducing abstract risk.
Assess Immediate Recovery Needs
Start by listing what must be fixed within days or weeks after a loss, and estimate the time and cost to restore each item. Consider scenarios such as a house repair, a car replacement, temporary lodging, or replacing lost income while recovering from illness. Compare those repair amounts against your emergency savings to see where insurance is needed to avoid deep financial strain. Quantifying timelines and costs makes it easier to decide which policies shorten downtime most effectively.
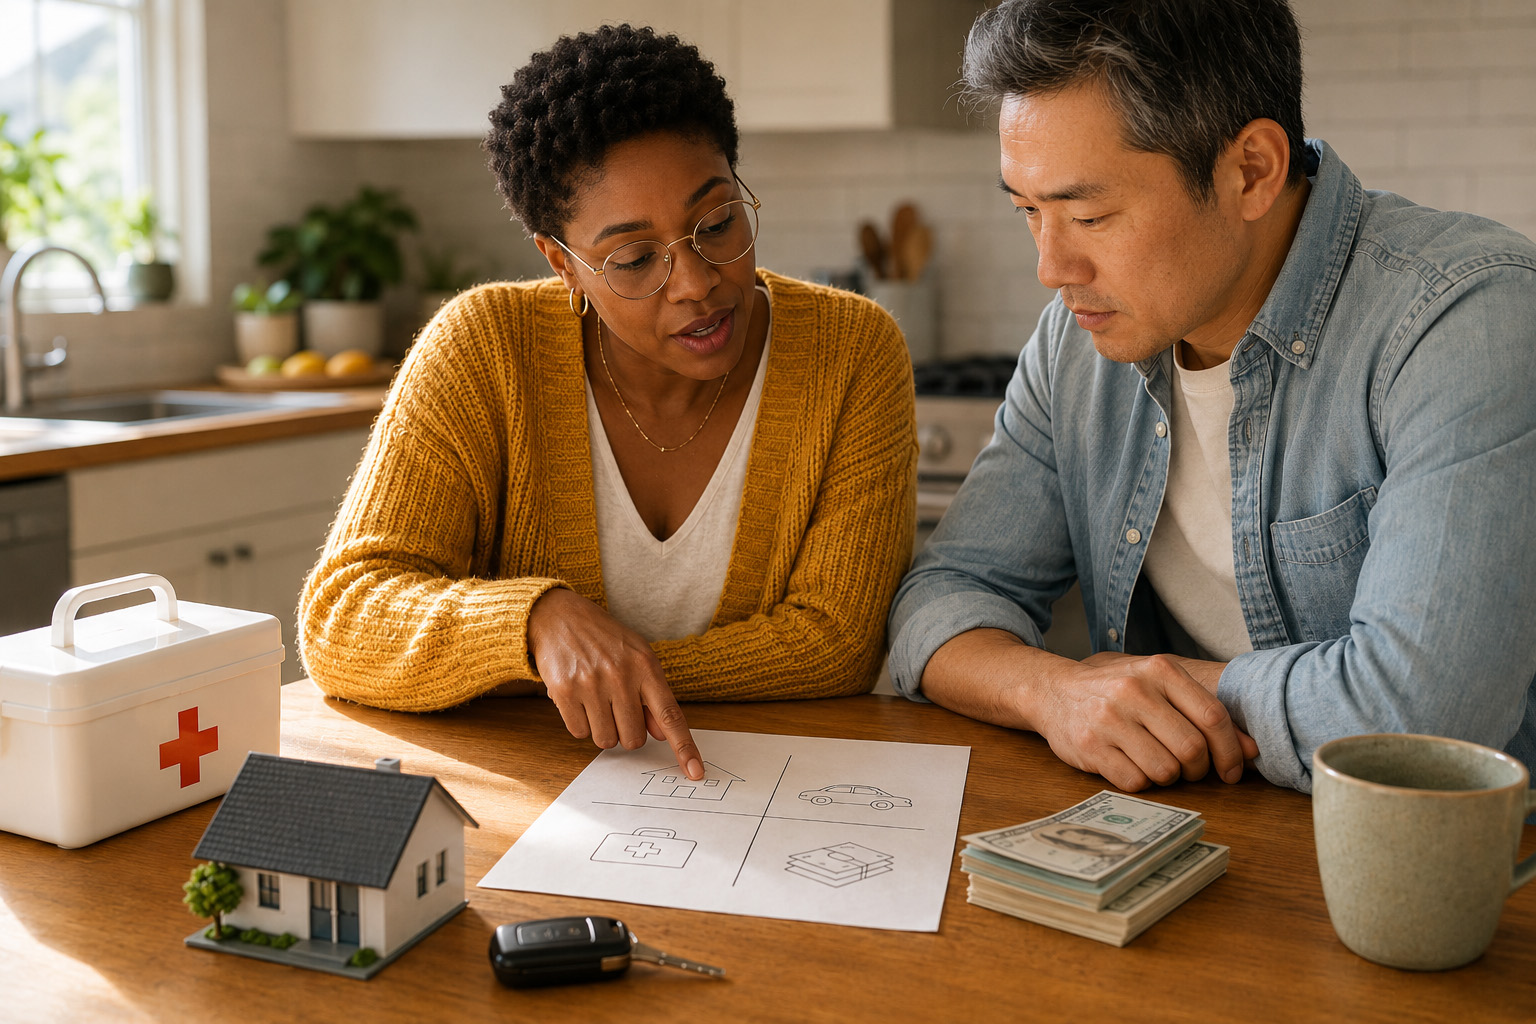
Use a simple matrix to pair items with recovery time and cost, and update it annually as priorities shift. That small exercise clarifies where insurance buys faster recovery rather than just covering inconvenience.
Balance Probability, Cost, and Recovery Speed
When evaluating coverage, weigh how likely an event is against how long and costly recovery would be without support. Coverages that have low probability but catastrophic recovery costs deserve different treatment than frequent minor losses that you can comfortably self-insure. Deductible levels and limits should reflect the point at which out-of-pocket costs would meaningfully delay getting back on your feet. This mindset shifts attention away from chasing comprehensive policies toward buying the protections that shorten recovery windows most.
Prioritize policies that materially reduce downtime even if they cost a bit more, and consider raising deductibles where recovery is affordable without a claim. Those trade-offs stretch insurance dollars toward faster stabilization.
Practical Steps to Apply Recovery-First Thinking
Run a compact audit: list assets and functions you rely on, estimate repair timelines and costs, and map existing policies to those recovery needs. Use two metrics when comparing quotes — expected time-to-recover with the policy, and maximum out-of-pocket cost — then choose coverage that optimizes the first metric while respecting budget constraints. Coordinate insurance choices with an emergency fund sized to cover short, high-frequency losses you decide to self-insure. Regularly revisit this approach after life changes such as moves, job shifts, or new dependents.
Communicating recovery priorities to your agent or advisor helps tailor quotes toward tangible outcomes instead of abstract coverage promises. Small, intentional changes can lead to quicker, less painful recoveries when losses occur.
Conclusion
Focusing on how quickly policies enable recovery turns insurance from a theoretical expense into a practical tool for restoring normal life. By assessing recovery needs, balancing probability with repair cost, and auditing policies against time-to-recover, you make smarter coverage choices. Those choices keep disruption short and your household moving forward after an unexpected event.