
Introduction
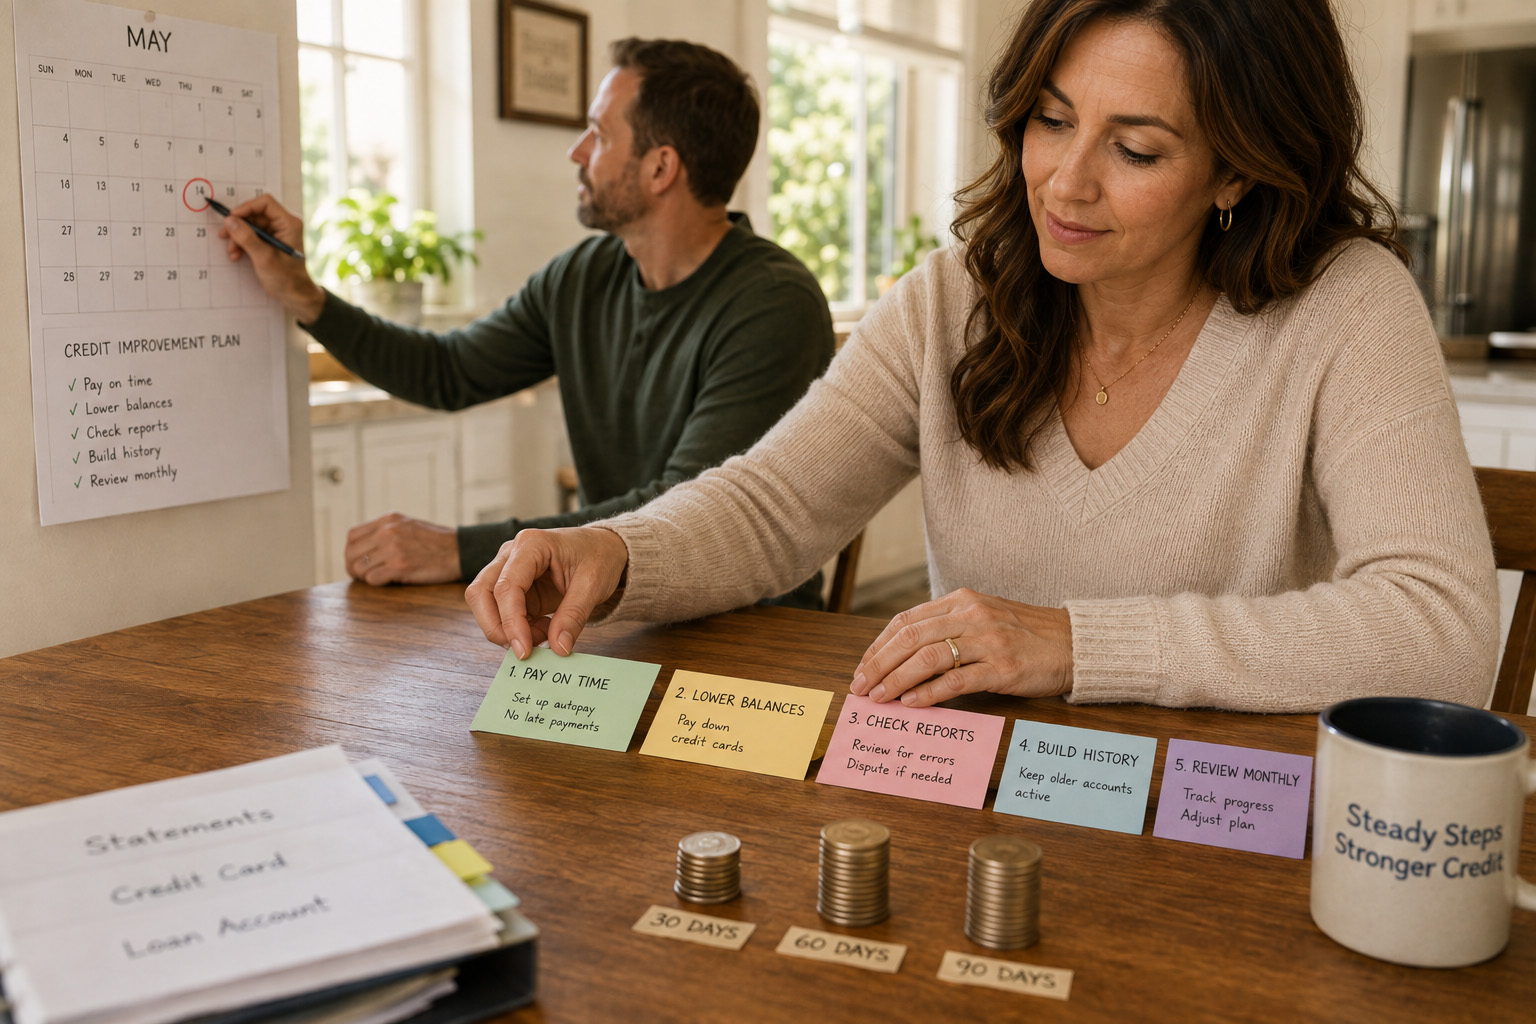
Improving a credit score is rarely about dramatic shortcuts and more about steady, prioritized actions over time. A planful approach helps you focus limited effort on moves that deliver the biggest return while minimizing risk. This article lays out how to assess where you are, choose high-impact priorities, and set simple systems that preserve gains. Use these steps as a framework you can adapt to your circumstances and measure month by month.
Assess Your Starting Point
Begin with a clear picture of your credit reports and the factors currently dragging on your score. Identify recent delinquencies, high utilization, collections, and any reporting errors that can be disputed. Understanding the age of accounts and the distribution of open credit helps you avoid counterproductive moves. Pulling data and categorizing items by impact reduces overwhelm and points to where effort matters.
Once you’ve mapped priorities, rank issues by how quickly they can be fixed and how much they affect the score. This ranking becomes the roadmap for the next 90 days of action.
Prioritize High-Impact Actions
With a roadmap, focus first on actions that reliably move a score: bringing past-due accounts current, lowering utilization, and correcting errors. Small shifts, like dropping utilization below 30% or ensuring on-time payments, often yield measurable gains faster than opening new accounts. Avoid chasing rapid boosts through risky products; steady improvements built on core metrics last longer. Where balances are high, target one account at a time to reduce utilization rather than scattering payments.
Track results monthly and adjust priorities when one tactic stops producing gains. Consistent, high-impact choices compound into notable score improvements over several months.
Build Simple Systems to Maintain Gains
Systems turn intentions into outcomes: automate payments, schedule monthly reviews, and set balance alerts to prevent backsliding. Automations reduce missed payments while simple monitoring catches creeping utilization before it becomes a problem. Use calendar reminders tied to billing cycles to optimize when you pay relative to statement dates. Keep documentation for disputes and record win milestones to stay motivated. Review credit utilization across cards to identify quick wins where a small payment yields visible change.
A compact system takes little time but protects improvements and helps prioritize next moves. Regular, small investments in routine processes preserve the benefits of earlier efforts.
Conclusion
Gradual credit growth is the product of informed priorities, targeted actions, and repeatable systems. Start with a clear assessment, focus on high-impact fixes, and automate to maintain progress. Over months those steady steps create measurable and sustainable improvements.