
Introduction
Short-term cash shortfalls are stressful but manageable with a focused plan. Start by assessing what must be paid now and what can wait, then create a simple sequence of actions. Small, immediate moves can restore breathing room and prevent costly decisions later. This article lays out practical steps you can take in the next few pay periods.
Map Immediate Cash Needs and Timing
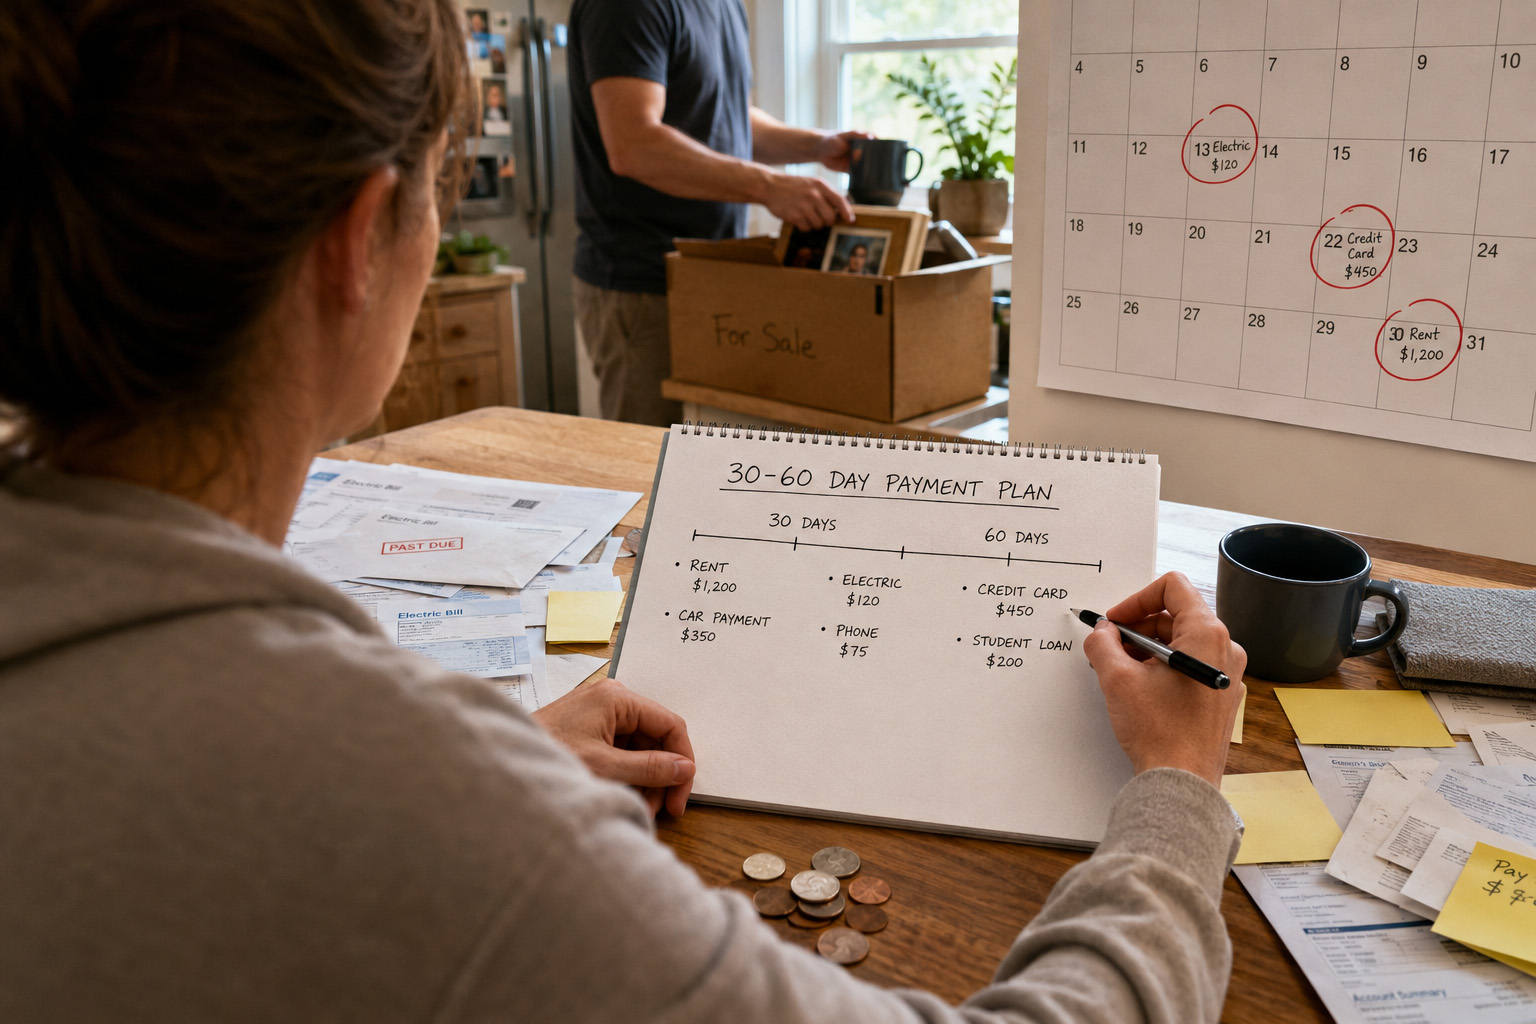
Begin by listing all upcoming payments and income for the next 30 to 60 days. Include fixed bills, essential living costs, and any known one-off expenses, then note the dates paychecks or other receipts arrive. This visual schedule helps you see gaps and identify which obligations are most urgent. Knowing the exact timing reduces guesswork and makes trade-offs clearer.
After mapping, highlight essentials like housing, utilities, food, and transportation. Defer nonessential charges and reach out to creditors for short extensions where sensible. Creating this timeline gives you a concrete plan rather than an abstract worry.
Prioritize and Trim with Intent
With your map in hand, apply a simple priority rule: protect essentials first, then obligations that prevent immediate penalties, and finally discretionary spending. Look for short-term trimming opportunities such as pausing subscriptions, reducing grocery costs with a focused list, or temporarily shifting optional payments. Small reductions across categories often free meaningful cash without dramatic lifestyle changes.
Communicate changes to household members or partners so everyone understands priorities. A shared plan reduces surprises and helps keep cuts consistent until cash recovery is achieved.
Use Short-Term Income and Liquidity Options Wisely
Boost inflows with targeted, low-friction actions: sell unused items, pick up a few hours of extra work, or accelerate expected payments from clients. When considering credit, choose the least costly and simplest option that avoids long-term strain—for example, a short-term low-interest loan from a community source rather than high-rate alternatives. Preserve emergency accounts for true crises to avoid repeating shortfalls.
Be cautious with solutions that add ongoing obligations. The goal is to bridge a brief gap, not to create new recurring costs that could deepen future shortfalls.
Conclusion
Create a clear schedule, protect essentials, and pursue short-term income boosts. Apply temporary trims consistently and choose liquidity options that don’t add long-term strain. With a compact, disciplined plan you can restore financial breathing room within a few pay periods.