
Introduction
Consistent weekly attention to your credit responsibilities makes steady improvement possible without dramatic disruption to daily life. Small, focused actions repeated each week reduce the risk of missed payments and help signal reliability to scoring models. This article outlines a compact routine you can follow every seven days to protect and gradually raise your credit profile. Use these steps as a template and adapt timing based on your billing cycles and goals.
By treating credit care as a short weekly task, it becomes easier to maintain discipline and spot issues early. The following sections break down what to check, how to prioritize tasks, and when to automate for long-term stability.
Weekly Checklist: Four High-Impact Tasks
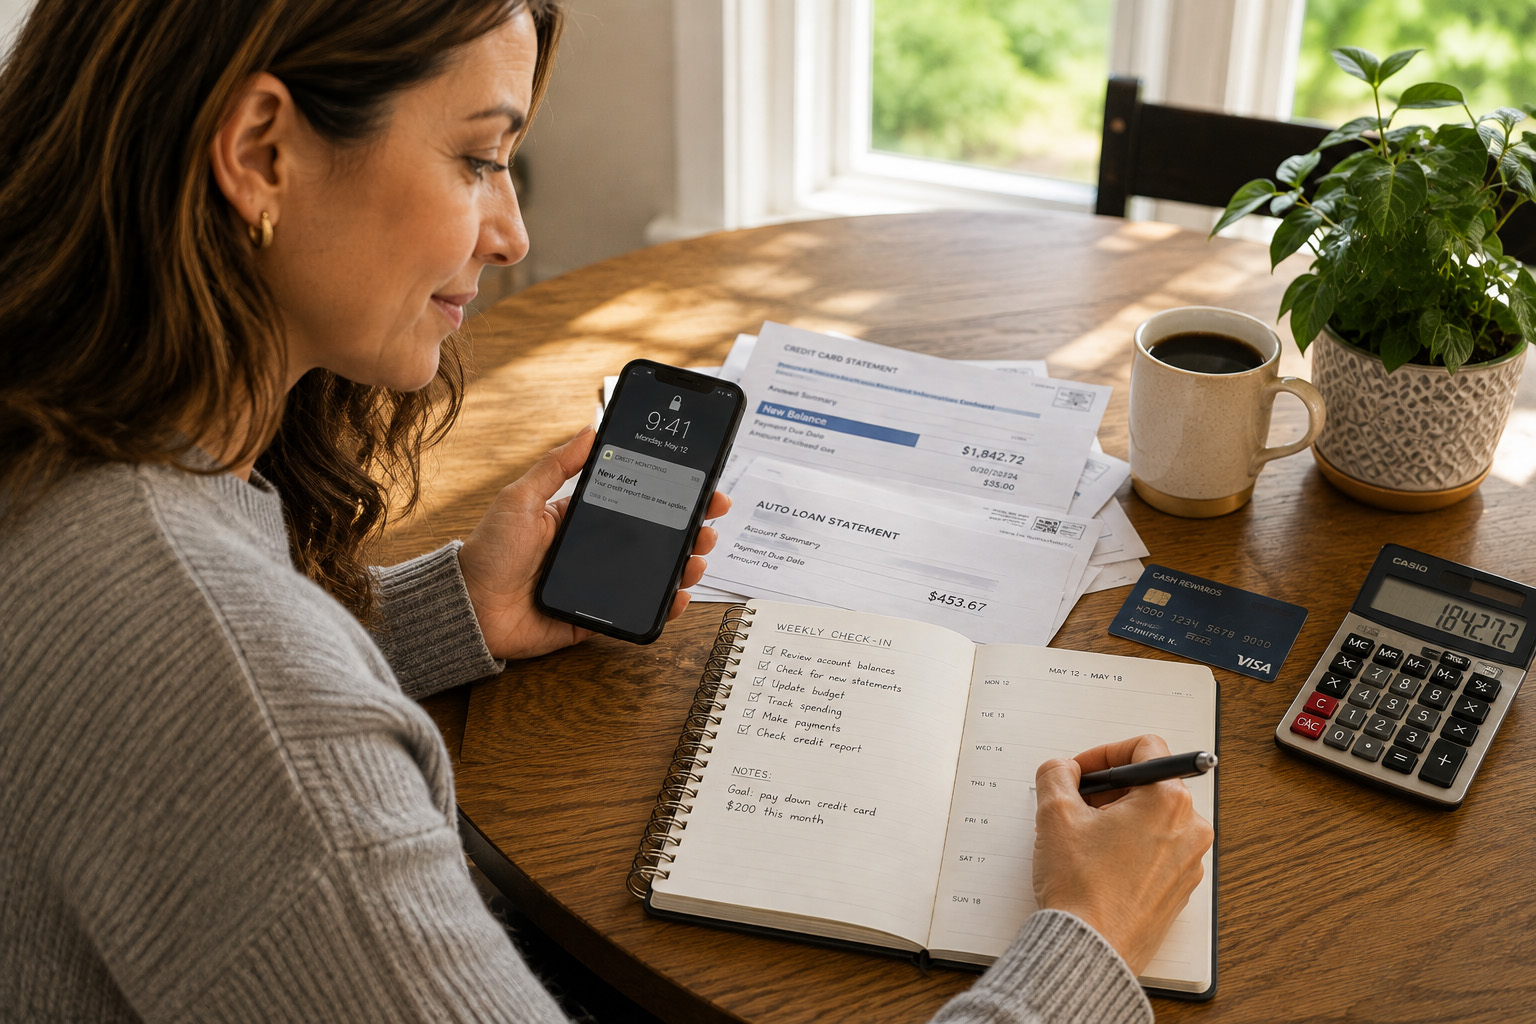
Start each week with a brief review of accounts and balances to catch anomalies before they affect your score. Focus on verifying upcoming due dates, checking for charges you don’t recognize, and confirming that credit utilization remains within your target. These checks take 15–30 minutes and help prevent late payments and sudden spikes that can hurt your score.
- Confirm upcoming payments and set reminders.
- Note current balances and utilization ratios.
- Flag unfamiliar transactions for investigation.
- Record any progress toward paying down high balances.
Completing this checklist weekly builds situational awareness and reduces surprises that lead to credit setbacks. Treat it as a short ritual—consistency is more important than perfection.
How to Prioritize Tasks Each Week
When time is limited, prioritize actions that have the largest, quickest impact on score and risk. On the top of the list are ensuring on-time payments, lowering balances on cards near their limits, and disputing clear errors on reports. Reserve lower-priority items, like opening new accounts or complex negotiations, for when you have more runway and information.
Use a simple ranking: due dates first, utilization second, and reporting errors third. This order minimizes immediate damage while preserving opportunities for gradual improvement.
Monitor, Record, and Adjust
Each week, document changes you observe so trends become visible over a month or quarter. Tracking the same metrics—payment timeliness, utilization percentage, and any disputes—lets you see which tactics are working and where to allocate effort. If a pattern of missed payments or rising balances appears, move into corrective action sooner rather than later.
Regular notes also make it easier to explain anomalies if you need to contact a creditor or dispute an item. Small records compound into clearer decisions and better outcomes.
Automate and Protect
Use automation to handle repetitive tasks like payments and balance alerts, freeing weekly time for oversight instead of execution. Set up autopay for at least the minimum due, and activate notifications when balances approach thresholds. Automation reduces the cognitive load and prevents late fees, while weekly reviews confirm the systems are working.
Combine automation with periodic manual checks to ensure you remain in control. A blend of tools and habit is the most resilient path to steady credit improvement.
Conclusion
Simple weekly habits prevent small problems from becoming score setbacks. Spend a short block of time each week on checks, prioritization, and documentation. Over months, these consistent steps produce measurable, sustainable credit improvement.