
Introduction
When cash is temporarily constrained, clear priorities help you protect essentials and keep momentum toward longer-term goals. Start by taking a calm inventory of what must be paid now versus what can wait, and avoid decisions driven by panic. Small, deliberate steps can prevent mistakes that make shortages last longer. This guide focuses on practical actions you can implement this month.
Assess Immediate Obligations
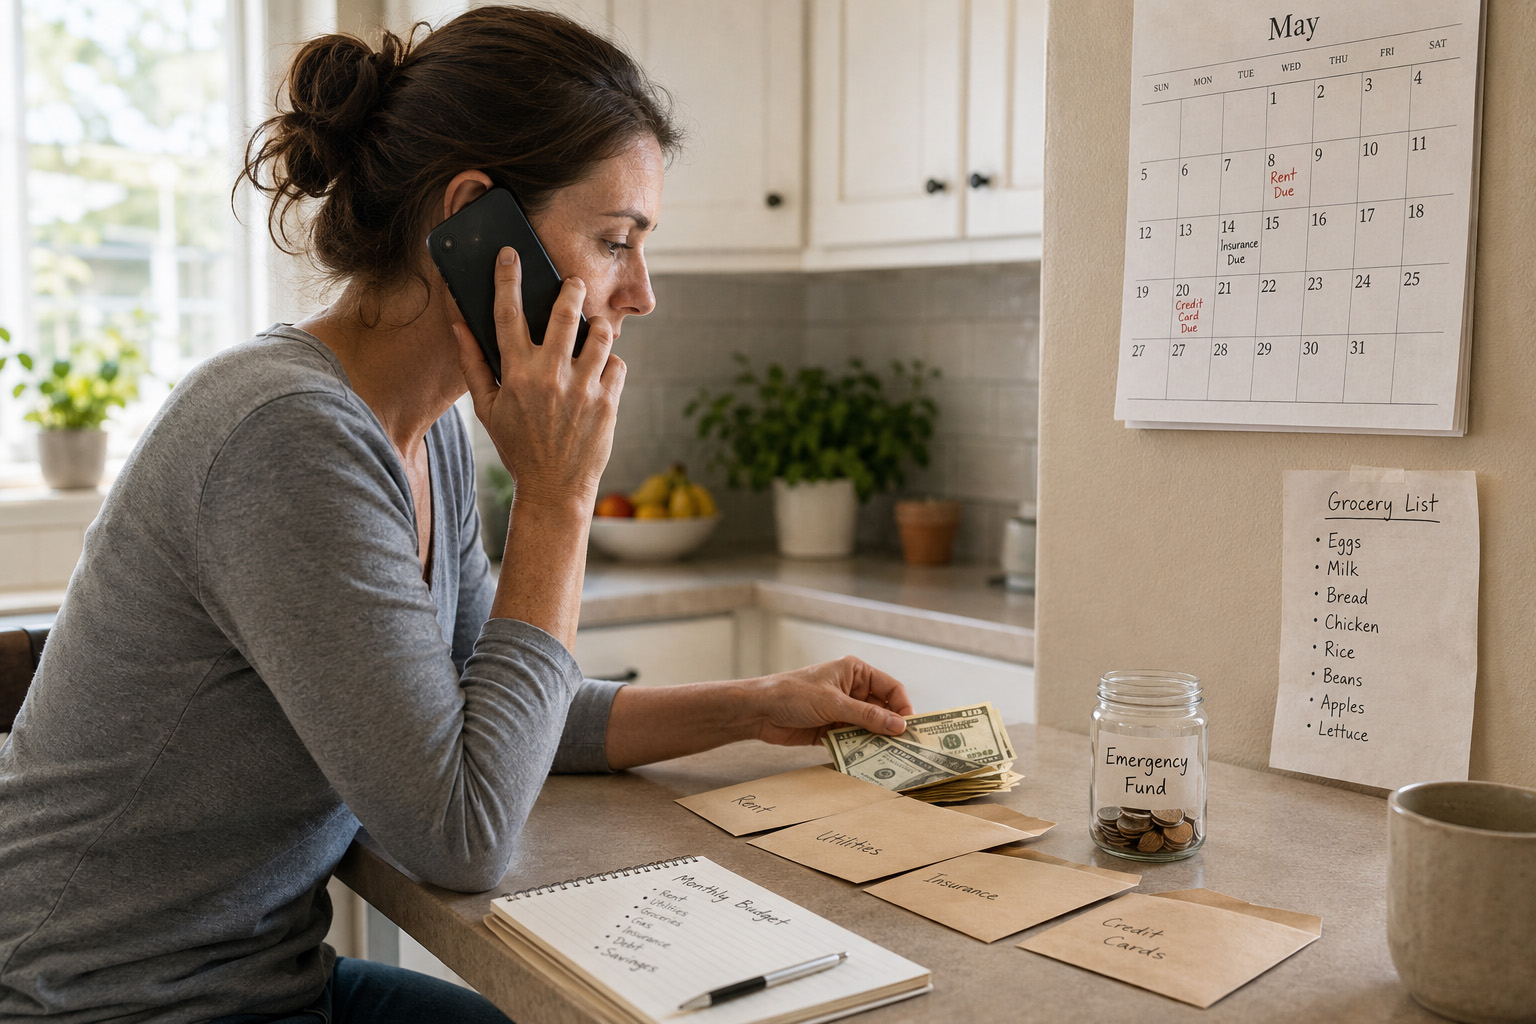
When money is tight, first separate nonnegotiable obligations from flexible ones. List rent or mortgage, utilities, essential transportation, and necessary food expenses, and mark any bills with late-fee deadlines. Contact creditors early if a payment will be late; many service providers offer temporary relief or payment plans if asked proactively. Prioritizing these items reduces the risk of cascading costs.
Keeping a short prioritized list makes choices clearer when income fluctuates. Revisit that list each week as balances and due dates change.
Trim Discretionary Spending
Next, identify discretionary spending you can pause or reduce without major disruption. Look at subscriptions, dining out, nonessential shopping, and entertainment, and decide which can be suspended for a few weeks. Small cuts accumulate quickly and free up cash for essentials or to build a tiny buffer. Use temporary limits rather than permanent bans so changes feel manageable.
- Pause one or two subscription services.
- Set a temporary low entertainment allowance.
- Shop with a simple list to avoid impulse buys.
These measures are short-term tools, not long-term austerity. Reintroduce items gradually as cash stabilizes.
Optimize Cash Flow
Finally, optimize incoming and outgoing cash to smooth the month. Sequence bills to match pay dates when possible, request advances for unpredictable income, or swap due dates with creditors. Consider small one-off actions like selling unused items or taking on a short gig to bridge a specific gap. Each action should be weighed against stress and time cost.
Combine modest income boosts with disciplined spending cuts for fastest effect. Track results so you can spot what worked and repeat it if needed.
Protect Credit and Essentials
Protecting credit and essential services preserves options once cash returns. When you can, keep minimum payments on credit accounts to avoid long-term damage to your score. If minimums are impossible, call lenders to ask about hardship options that may temporarily lower payments or pause interest. Document any agreements in writing to avoid surprises.
Small actions to protect credit prevent bigger costs down the road. Treat these steps as part of a short recovery plan rather than permanent change.
Conclusion
Short-term cash constraints are stressful but manageable with clear priorities. Focus on essentials, pause flexible spending, and optimize cash flow to regain breathing room. Small, deliberate moves this month can protect stability and preserve longer-term goals.