
Introduction
Improving your credit score is often about choosing the right actions at the right time. Small, focused steps can deliver measurable results without overwhelming your daily finances. This article outlines priority-based moves you can take now and sustain over months to strengthen your credit profile. The emphasis is on impact-first decisions and consistent follow-through.
Assess Your Starting Point
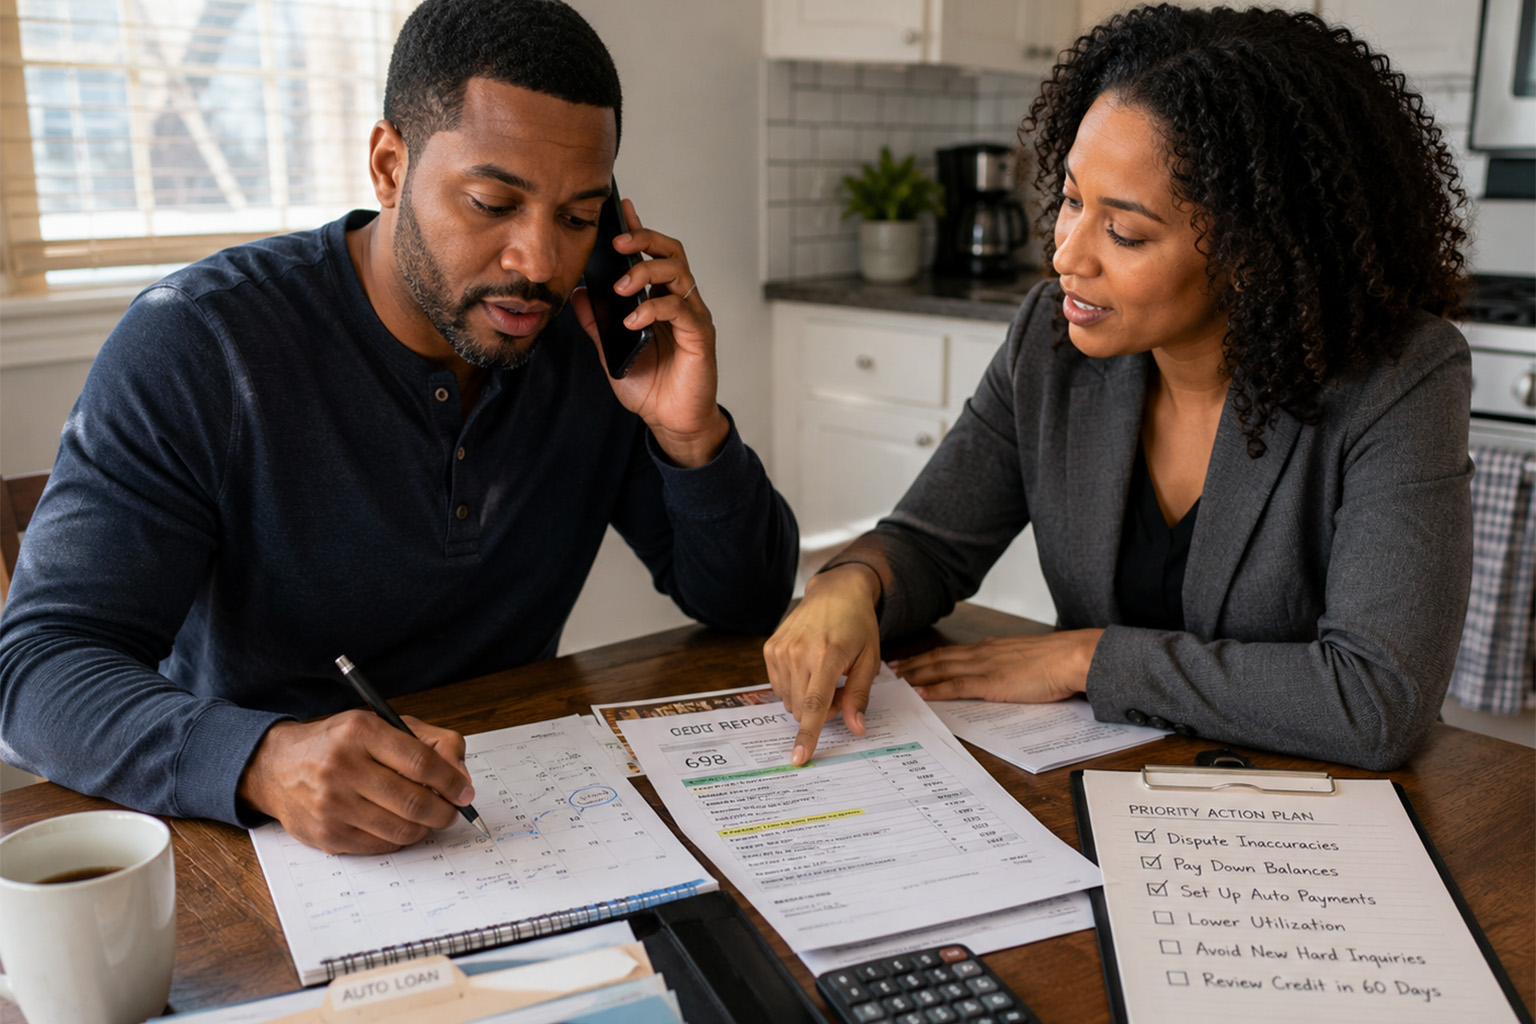
Begin by pulling your credit reports and reviewing key items: account statuses, balances, recent inquiries, and any negative entries. Identifying errors or outdated information is essential because correcting inaccuracies can yield a quick score benefit. Pay special attention to collections, late payments, and high-utilization accounts that have the largest negative influence. Understanding where problems cluster lets you focus effort where it matters most.
Set a realistic target and timeline based on your findings, prioritizing fixes with the highest impact. Use a simple checklist to track progress and keep follow-up dates visible.
Repair What Hurts Most
Address delinquencies and disputes early: contact creditors to request goodwill adjustments for isolated late payments and file disputes for factual errors on reports. For collection accounts, validate the debt and negotiate pay-for-delete or settlement terms when appropriate. Avoid opening multiple new accounts to chase score gains; instead concentrate on resolving or managing negative entries first. Calm, documented communications improve chances of favorable outcomes.
Document each interaction and follow up until the agreed changes appear on your reports. Prioritizing corrections reduces lingering damage and sets the stage for steady recovery.
Optimize Utilization and Account Management
Lowering revolving utilization is one of the fastest ways to improve scores: aim to keep balances under 30% of limits, and ideally under 10% for stronger effects. Requesting modest credit-line increases can help utilization if you maintain or reduce balances. Enroll in autopay and calendar reminders to avoid future late payments, which protect both score and lender relationships. Thoughtful payment timing—paying down balances before statement closing—can signal lower utilization to scoring models.
Maintain older accounts and avoid unnecessary closures; length of credit history matters. Consistent, on-time behavior compounds into meaningful gains over time.
Build Positive Habits and Monitor Progress
Adopt a monitoring cadence: review reports quarterly and set alerts for major changes. Consider a diverse credit mix only when it aligns with your needs and you can manage new obligations responsibly. Track improvements against your target and adjust tactics—such as accelerating payments or negotiating settlements—based on results. Patience matters: meaningful score changes often unfold over months rather than weeks.
Celebrate incremental wins and stay disciplined with payments and utilization. Regular monitoring helps catch issues early and keeps momentum moving forward.
Conclusion
Focus on high-impact fixes first: clear errors, reduce utilization, and stop late payments. Combine those actions with consistent monitoring and responsible account management to create steady improvement. Stay patient—sustained habits produce the most reliable credit gains.