
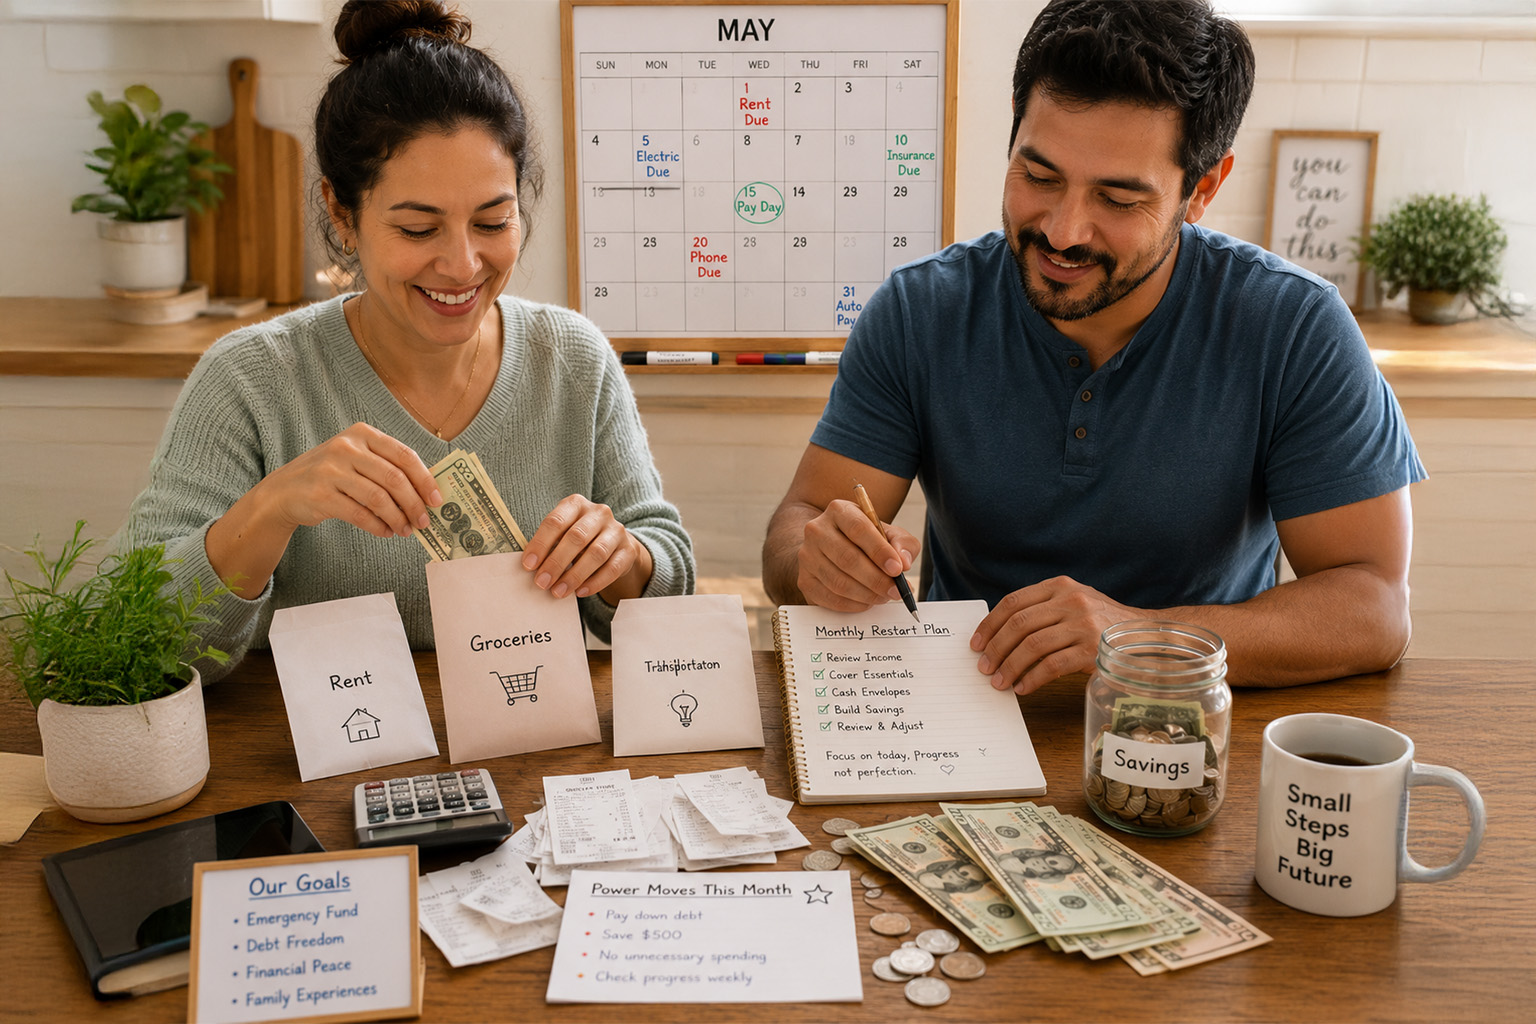
Introduction
Facing a tight month can be unsettling, but a clear restart plan brings control and calm. Start by clarifying immediate cash needs, then align spending and income to cover essentials first. This guide walks through quick assessments, pragmatic adjustments, and routines that restore breathing room. Followable steps and small habits create a realistic path to steady cash flow by the next cycle.
Assess Immediate Cash Needs
Begin with a short, focused inventory of all upcoming obligations due this month. Identify fixed essentials like rent or mortgage, utilities, groceries, and minimum debt payments, and mark any bills that are flexible or negotiable. Tally the total cash required within the next 30 days so you know the minimum you must secure. This precise view eliminates guesswork and guides your next moves.
With a clear list, prioritize payments that protect housing, transport, and necessary services. This order helps you allocate scarce funds without missing critical obligations.
Reorganize Short-Term Outflows
Look for quick wins by pausing or downgrading subscriptions, delaying nonessential purchases, and shifting due dates where possible. Contact service providers and explain a short-term constraint; many offer temporary hardship options or flexible schedules. If you use credit, determine minimum payments to avoid late fees while you stabilize cash. Sequencing income and withdrawals can prevent overdrafts and reduce stress.
- Move charge dates to align with upcoming deposits.
- Temporarily suspend noncritical subscriptions and memberships.
- Ask creditors for short-term payment arrangements or fee waivers.
These adjustments typically free up enough liquidity to cover essentials and buy you time to rebuild. Keep changes temporary and track their impact so you can reinstate services when feasible.
Build a Practical Recovery Routine
Establish a weekly check-in to review balances, upcoming bills, and progress toward a small buffer goal. Automate modest transfers into a separate account as soon as inflows arrive, even if the amount is minimal. Set a reachable target: for example, a two-week buffer within two or three pay cycles, then expand from there. Regular habits reduce the chance of repeating shortfalls.
Focus on consistency over speed; small, steady contributions compound into meaningful reserves. Celebrate progress and adjust the routine as income patterns change.
Conclusion
Regaining monthly cash stability starts with a clear snapshot of obligations and practical, temporary changes. Short-term reorganization and a simple recovery routine can restore breathing room within weeks. Stay disciplined and gradually rebuild a buffer to reduce future stress.