
Introduction
Establishing a dependable routine around your credit habits can produce steady, measurable gains over time.
Small, consistent actions often outweigh sporadic, large efforts when it comes to credit health.
This article outlines practical monthly checks and behaviors you can adopt without stress.
Follow a few focused steps and you’ll create momentum that lenders and future you will appreciate.
Understand the Key Credit Drivers
Your score reflects a handful of core behaviors: payment history, utilization, account age, credit mix, and inquiry frequency.
Knowing which of these factors matter most for your situation helps you prioritize where to act first.
For most people, keeping payments on time and utilization low delivers the fastest improvement.
Reviewing the relative impact of each driver gives clarity and reduces the temptation to chase every minor metric.
Start by pulling your credit information and noting any trends or recurring issues.
That snapshot will guide which monthly checks you schedule and which habits you reinforce.
Monthly Actions to Move the Needle
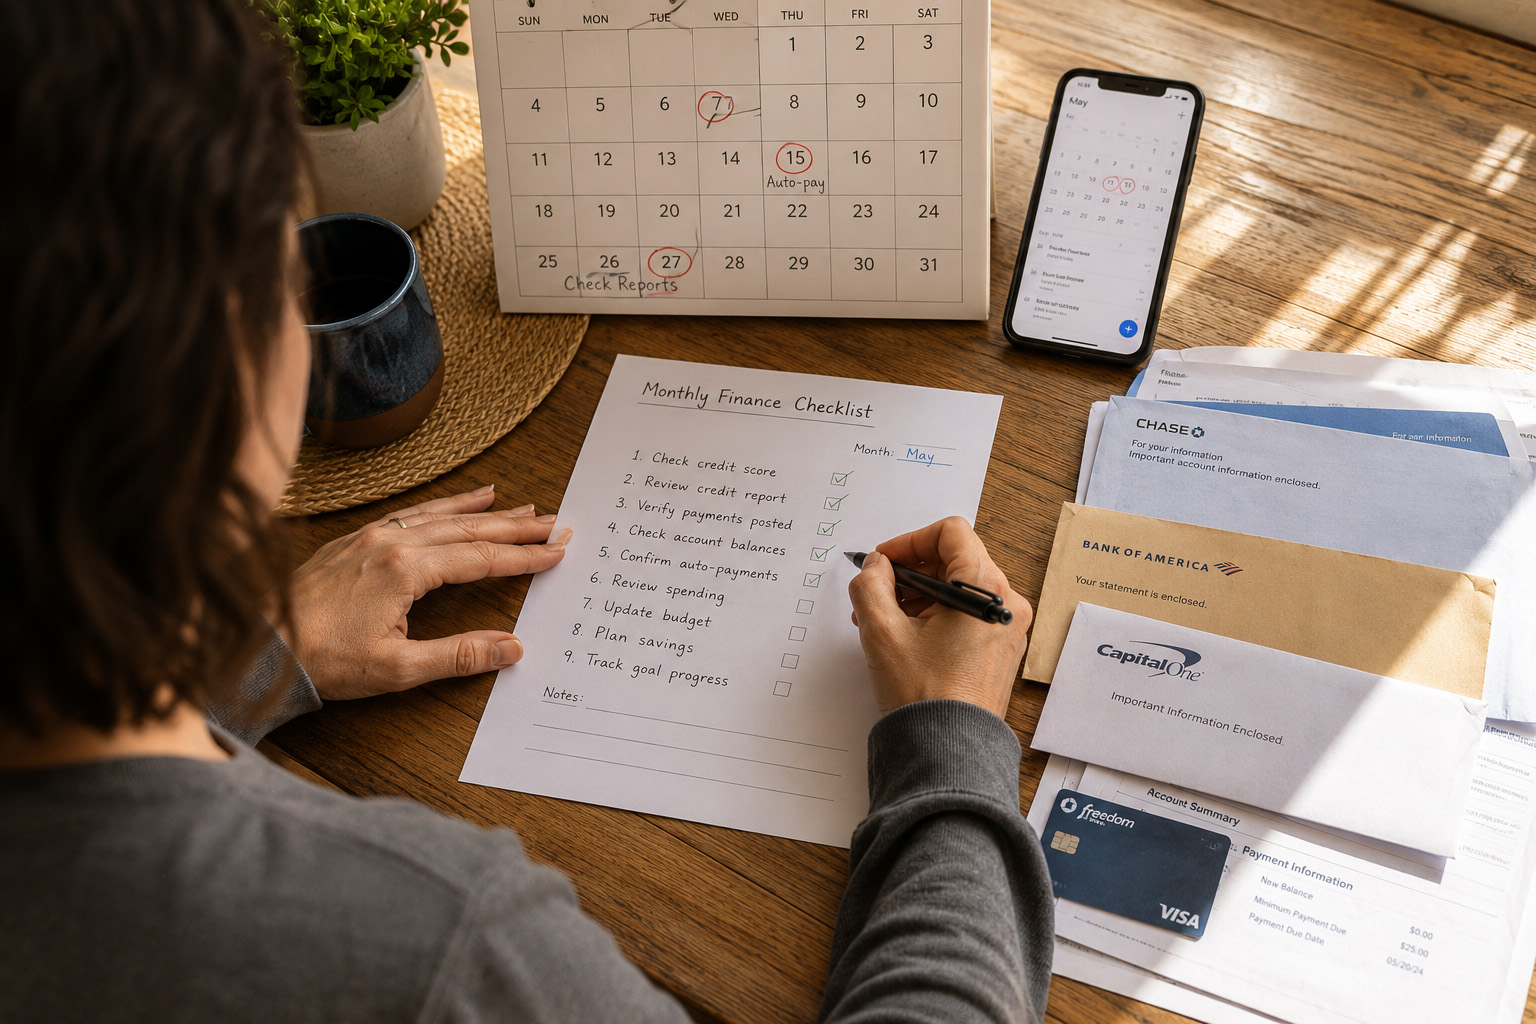
Create a concise monthly checklist you actually use: review balances, confirm due dates, and scan accounts for unexpected activity.
Automate payments where appropriate to protect your payment history and reduce missed-payment risk.
Monitor credit utilization by paying down rotating balances or requesting small credit limit increases when justified.
These consistent steps keep the biggest score drivers stable and predictable.
- Set calendar reminders for statement closing dates to manage reported balances.
- Use one card primarily for recurring charges, then pay it in full each month.
- Check your report quarterly and after any major life change or credit event.
Keeping the checklist short increases the chance you’ll follow it each month.
Over time, these modest actions compound into stronger credit signals and fewer surprises.
Common Pitfalls and How to Avoid Them
Frequent account openings, maxing out cards, and neglecting small collections can quickly erode progress.
Resist impulse credit applications and evaluate whether a new account serves a clear purpose.
If you find errors or outdated items on your report, file disputes promptly and follow up until resolved.
Addressing small issues early prevents them from becoming long-term obstacles to recovery.
Adopting a conservative, steady approach protects momentum when life becomes busy or unpredictable.
When exceptions occur, revert to automation and the checklist to regain balance quickly.
Conclusion
Consistent, manageable monthly checks keep the main credit drivers under control.
A short, repeatable routine reduces risk and builds positive trends over time.
Stick to the plan and review progress periodically to refine your approach.