
Introduction
Knowing which insurance to buy first helps protect income, assets, and recovery capacity.
Prioritizing coverages reduces the chance of crippling costs after common losses.
This article outlines a practical approach to decide what to insure and how much to pay.
Use these steps to align policies with likelihood, impact, and your budget.
Assess Immediate Financial Vulnerabilities
Start by listing events that would cause the most financial harm in the next few years. Focus on lost income, large medical bills, and damage to home or vehicle that you could not quickly repair. Estimate the out-of-pocket cost and how long you could cover it from savings. That clarifies which risks are urgent and which are tolerable.
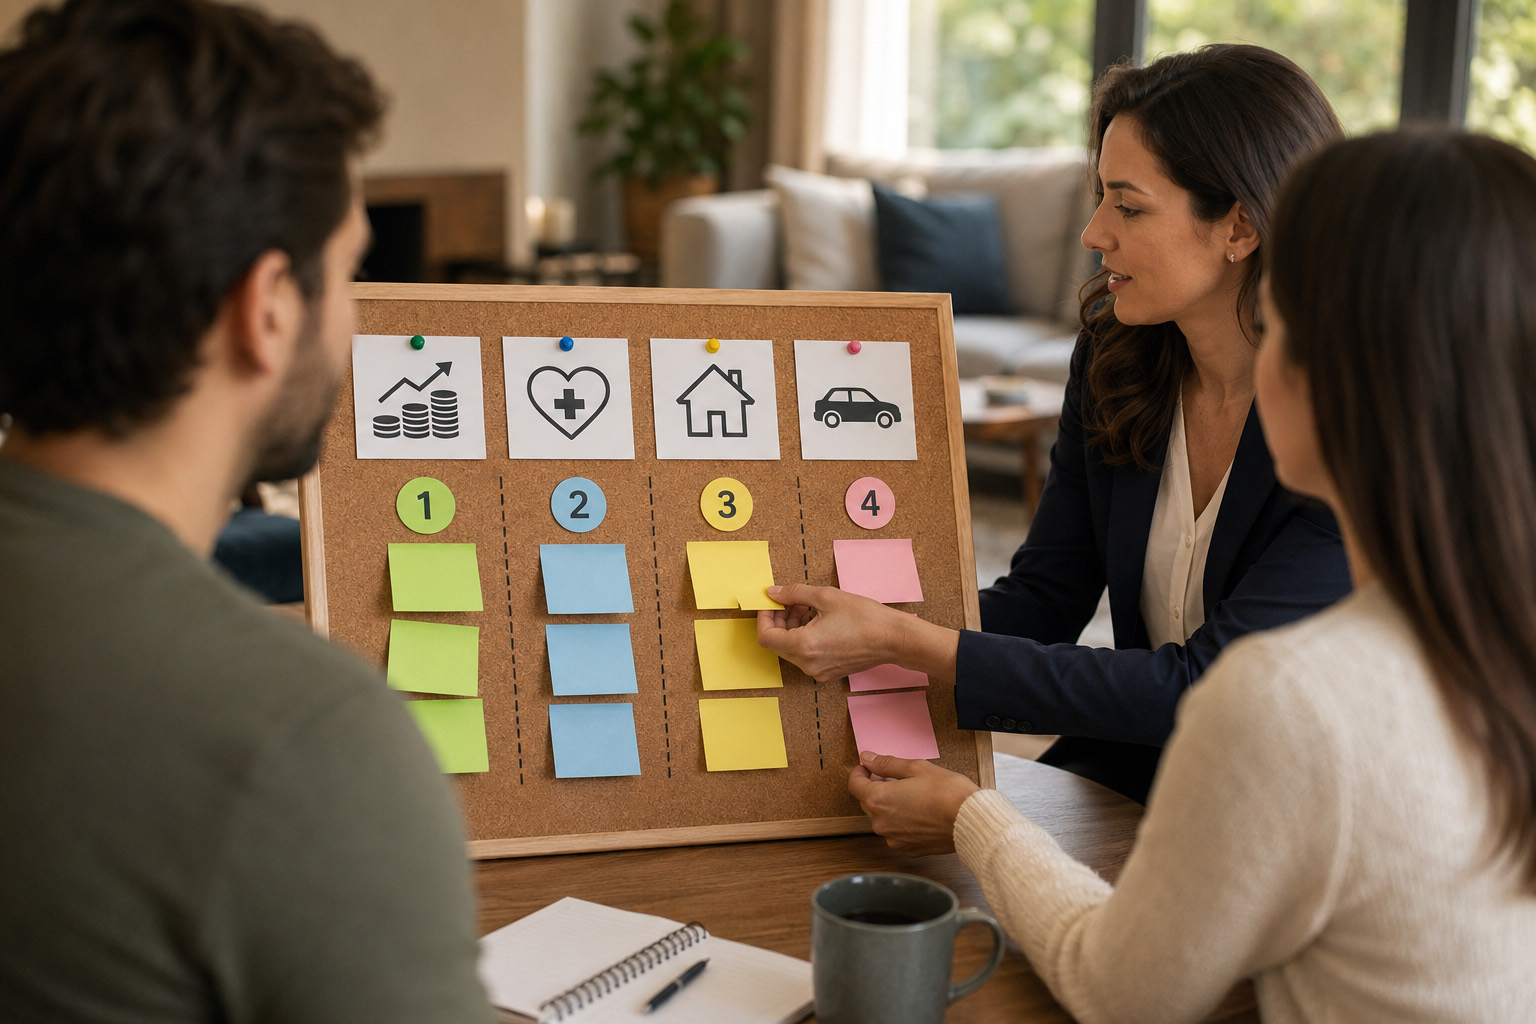
Turn that information into a short ranked list with dollar ranges so you can compare risks objectively. This baseline makes it easier to allocate policy dollars where they shorten recovery time most effectively.
Select Coverages That Speed Recovery
Choose policies that restore cash flow and replace essential assets quickly. Income protection, health coverage that prevents catastrophic debt, and adequate homeowner or renter replacement limits commonly matter first. Auto insurance with liability and appropriate physical damage coverage also makes sense when a vehicle is necessary for work. Prioritize coverages that reduce recovery time more than those that insure unlikely, low-impact events.
- Income protection or disability insurance
- Health insurance with strong catastrophic coverage
- Homeowner, renter, and liability coverages
- Auto coverage that supports mobility for work
Use these categories as a starting point rather than a checklist to buy everything at once. Tailor priorities to your specific vulnerabilities and dependents.
Balance Limits, Deductibles, and Cost
Adjust limits and deductibles to buy the most protection where it matters and accept more risk where recovery is affordable. Higher deductibles lower premiums but increase cash needs after a loss, so pair larger deductibles with a committed emergency fund. Review policy limits against replacement or rebuilding cost estimates rather than historical numbers. Small upgrades in liability or out-of-pocket caps can dramatically reduce long-term risk for modest additional premiums.
Run simple cost comparisons to see the premium per dollar of added protection. That keeps decisions practical and budget-friendly.
Review and Adjust Regularly
Life changes alter priorities: income shifts, home improvements, or new family members all matter. Schedule an annual review to update the ranked vulnerability list and check policy consistency. When renewing, ask agents for options that match your current recovery goals rather than renewing by default. Document decisions so future changes are easier to evaluate.
Regular reviews prevent gaps and avoid paying for unnecessary extras. They keep your insurance aligned with real-life needs as circumstances evolve.
Conclusion
Prioritize policies that shorten financial recovery and protect essentials.
Keep decisions simple, data-driven, and tied to ranked vulnerabilities.
Review annually to maintain alignment as needs change.