
Introduction
Deciding which insurance to buy first can feel overwhelming, especially with competing household priorities.
A clear sequence reduces guesswork and helps you protect finances where it matters most.
This approach focuses on exposure, recoverability, and the cost of transfer versus self-insurance.
Use these practical criteria to build a prioritized plan that fits your budget and life stage.
Start with Income Protection
Your ability to replace earned income is the single biggest financial risk for most households, so it should be a top priority. Consider short-term and long-term disability options, and evaluate life insurance if others depend on your earnings. Policies that stabilize cash flow after an illness, injury, or death reduce the chance of needing to liquidate assets or accumulate debt. Assess how long you could meet essential expenses without income and aim to fill that gap first.
Choosing policies that cover wage replacement helps preserve long-term goals and daily living standards. Income protection is often cost-effective relative to the financial disruption it prevents.
Cover High-Value and Hard-to-Replace Assets
After income, focus on assets whose loss would be hard to recover: your home, vehicle used for work, and essential tools. Homeowners or renters coverage plus appropriate limits and deductibles guard against major repair or replacement bills. Auto insurance with liability and collision protections addresses common and potentially expensive events. Prioritize coverages for assets tied to your livelihood or that could trigger major out-of-pocket costs.
Adjust limits and deductibles to balance premium affordability and potential recovery cost. Where possible, bundle policies to capture discounts and simplify management.
Layer Health and Disability Coverage Thoughtfully
Health insurance and long-term disability options address ongoing medical expenses and chronic impairments that can erode savings. Evaluate plan networks, out-of-pocket maximums, and how disability benefits integrate with employer plans and government programs. Preventive care and supplemental policies can reduce long-term exposure to medical bills and loss of earning capacity. Health-related protection often interacts with income and asset plans, so treat it as a coordinating layer rather than an isolated purchase.
Review this coverage annually, especially after changes in employment, health, or household composition. Minor tweaks can significantly improve protection and cost-effectiveness.
Practical Steps to Implement Your Order
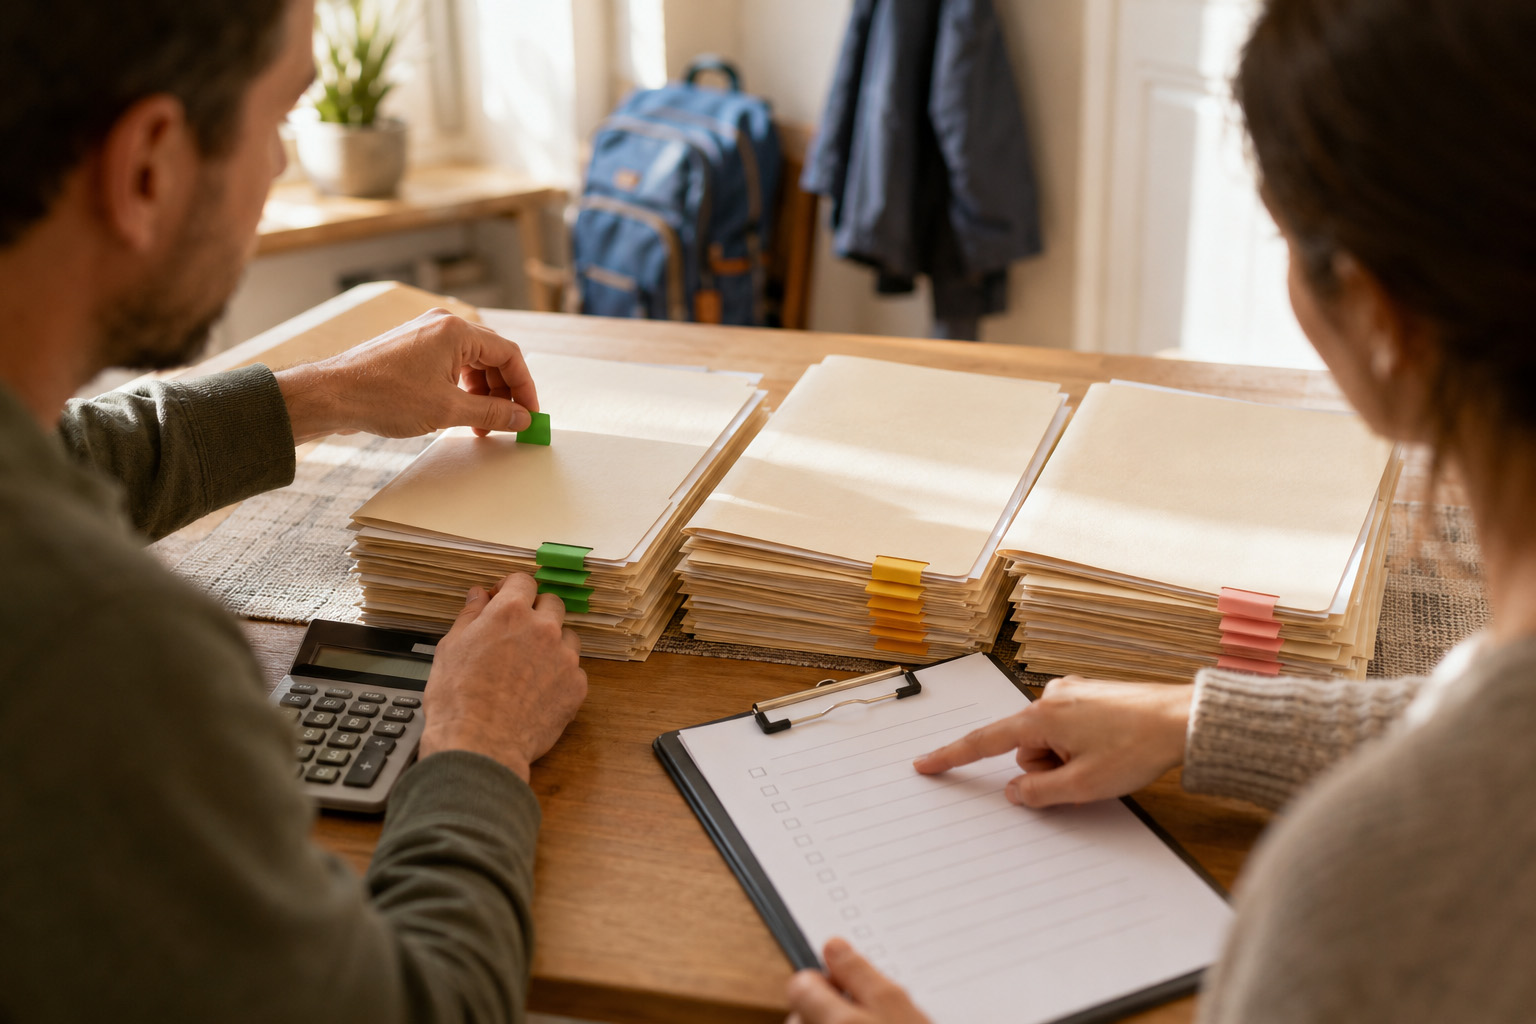
Start with a simple risk inventory: list earnings, essential expenses, and irreplaceable assets. Compare the cost of transferring risk via insurance versus retaining it through savings and emergency funds. Where premiums are limited, prioritize policies that prevent catastrophic losses over those that cover minor inconveniences. Seek quotes, ask targeted questions about exclusions, and document how each policy fits your prioritized plan.
- Calculate essential monthly expenses and desired replacement period.
- Identify assets that would force large, immediate payouts.
- Choose coverages in the order outlined and revisit annually.
Keep records and revisit priorities after major life events to ensure coverage stays aligned with evolving needs. Small, regular reviews preserve both protection and budget balance.
Conclusion
Prioritize policies that protect income, then secure hard-to-replace assets, and layer health protections next.
Use a simple inventory and cost-versus-recovery logic to order purchases and set deductibles.
Reassess annually and after major life changes to keep your plan effective and affordable.