
Introduction
When cash is tight, clear sequencing of spending can prevent small problems from becoming bigger ones. A calm, repeatable order for payments helps you cover essentials while buying time to adjust. This approach focuses on need, risk, and timing rather than emotion or convenience. With a simple plan you can protect your core finances and make deliberate choices until the next inflow arrives.
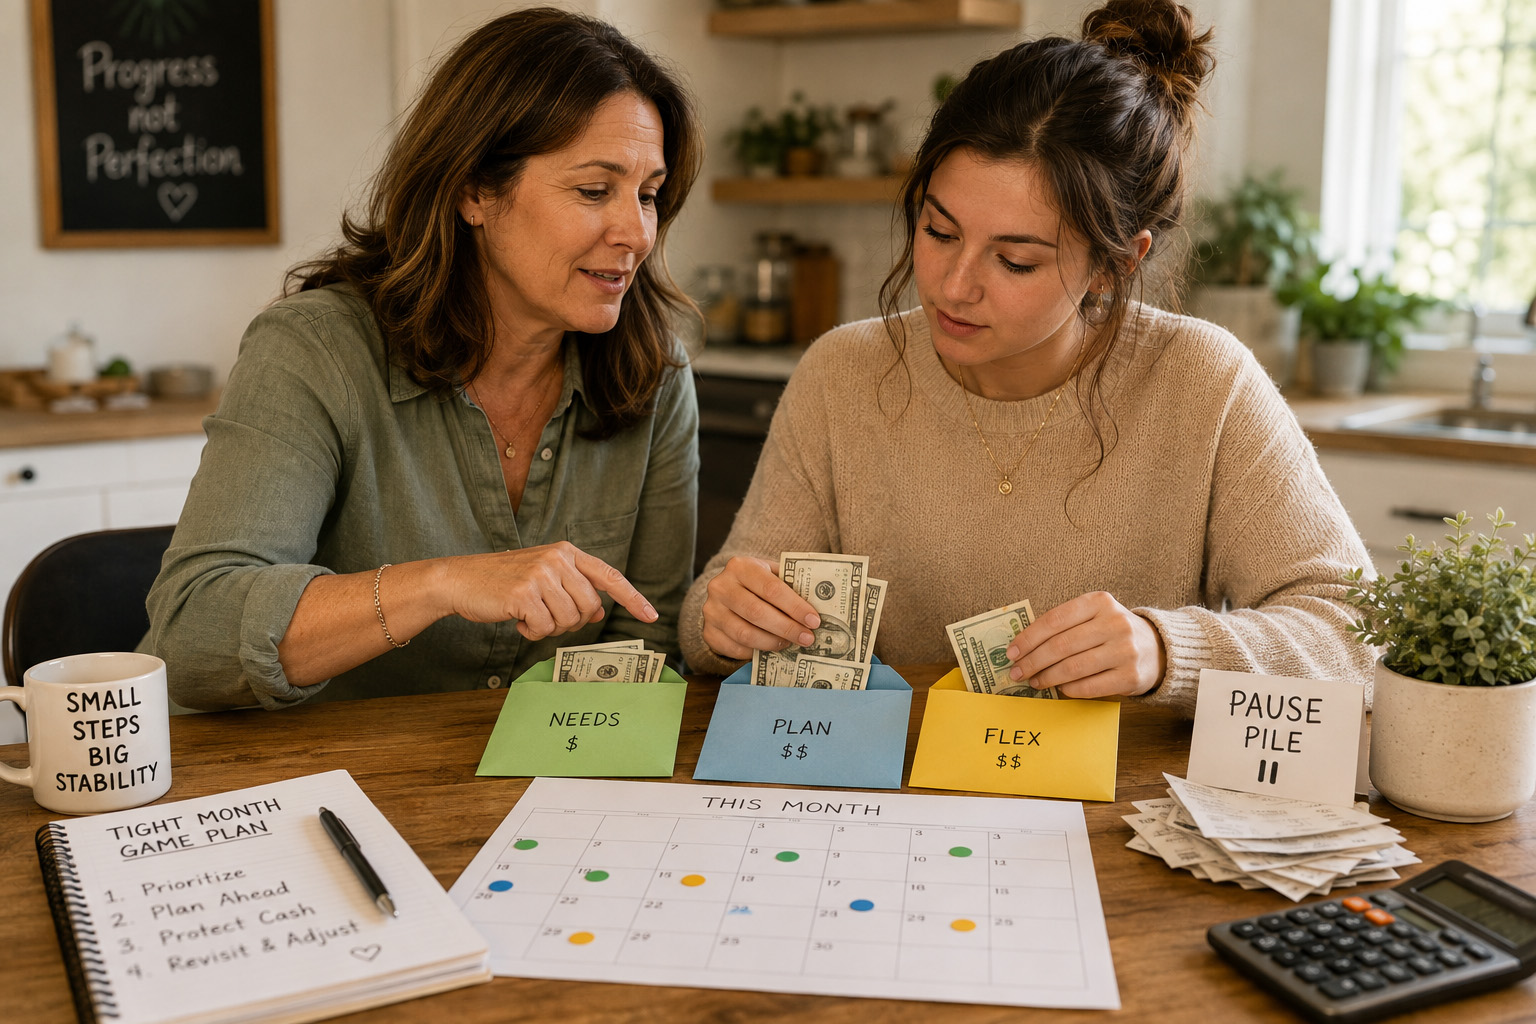
Start by taking a brief inventory of upcoming obligations and available balance. Next, decide which costs are non-negotiable and which can be shifted or paused. Finally, pick two immediate steps to lower outgoing cash in the short term.
Quick triage: decide what to pay first
Begin by grouping obligations into three practical categories: essentials that keep you housed, safe, and working; obligations with immediate legal or service risks; and flexible or deferrable costs. Essentials include rent or mortgage, utilities needed for safety, and transportation required to earn income. The second group covers payments that could trigger service interruptions, late fees, or significant penalties if missed. The third group captures discretionary subscriptions, non-urgent repairs, and optional purchases.
Use this triage to sequence payments until cash recovers. Prioritizing by consequence and timing keeps immediate risk low while you assess longer-term adjustments.
Trim and extend: practical adjustments that free cash
Look for low-friction changes that reduce spending quickly: pause nonessential subscriptions, cut discretionary purchases, and defer planned upgrades. Contact service providers to ask about short-term hardship options, lower-tier plans, or flexible billing dates. Small timing shifts—moving a payment a week or asking for a due-date change—can bridge a gap without harming relationships or credit.
- Pause or downgrade nonessential services.
- Ask about payment plans or temporary relief from providers.
These steps can buy breathing room while you stabilize income or reallocate funds to essentials.
Stabilize and rebuild: short-term actions with medium-term benefit
Once immediate risks are addressed, create a short plan to rebuild a small buffer quickly. Redirect any extra checks, side income, or refunded amounts to a dedicated short-term reserve. Keep the buffer modest and achievable—small, consistent deposits matter more than ambitious goals you cannot sustain. Track results weekly to maintain visibility and adjust priorities as needed.
Consistent monitoring and small, repeatable habits will prevent similar tight periods from recurring. Treat the buffer as operational cash, not long-term savings until it grows enough for both roles.
Conclusion
Sequencing spending during a cash shortage reduces risk and preserves essential services. Focus on consequence, timing, and simple adjustments that free immediate cash. With clear priorities and small habits you can protect today and rebuild for tomorrow.