
Introduction
Improving your credit score is rarely about a single dramatic move; it is the result of steady, well-timed actions. A structured routine that emphasizes small wins reduces risk and builds measurable momentum. This article outlines manageable weekly and quarterly steps that target payment behavior, utilization, and error correction. Follow a clear plan and adapt it to your situation for consistent progress.
Why incremental routines outperform big, sporadic changes
Large, infrequent changes can backfire by increasing volatility in your credit profile and raising short-term risk. Incremental routines keep utilization low, preserve positive payment history, and avoid sudden account openings or closures that confuse scoring models. Regular, modest improvements are easier to sustain and make it simpler to track what actually moves your score. Over time, cumulative small gains tend to produce steadier, more reliable improvements than one-off fixes.
By focusing on repeatable habits you also reduce stress and avoid costly mistakes. The predictable rhythm helps prioritize attention where it matters most.
Weekly checklist: simple habits with immediate benefits
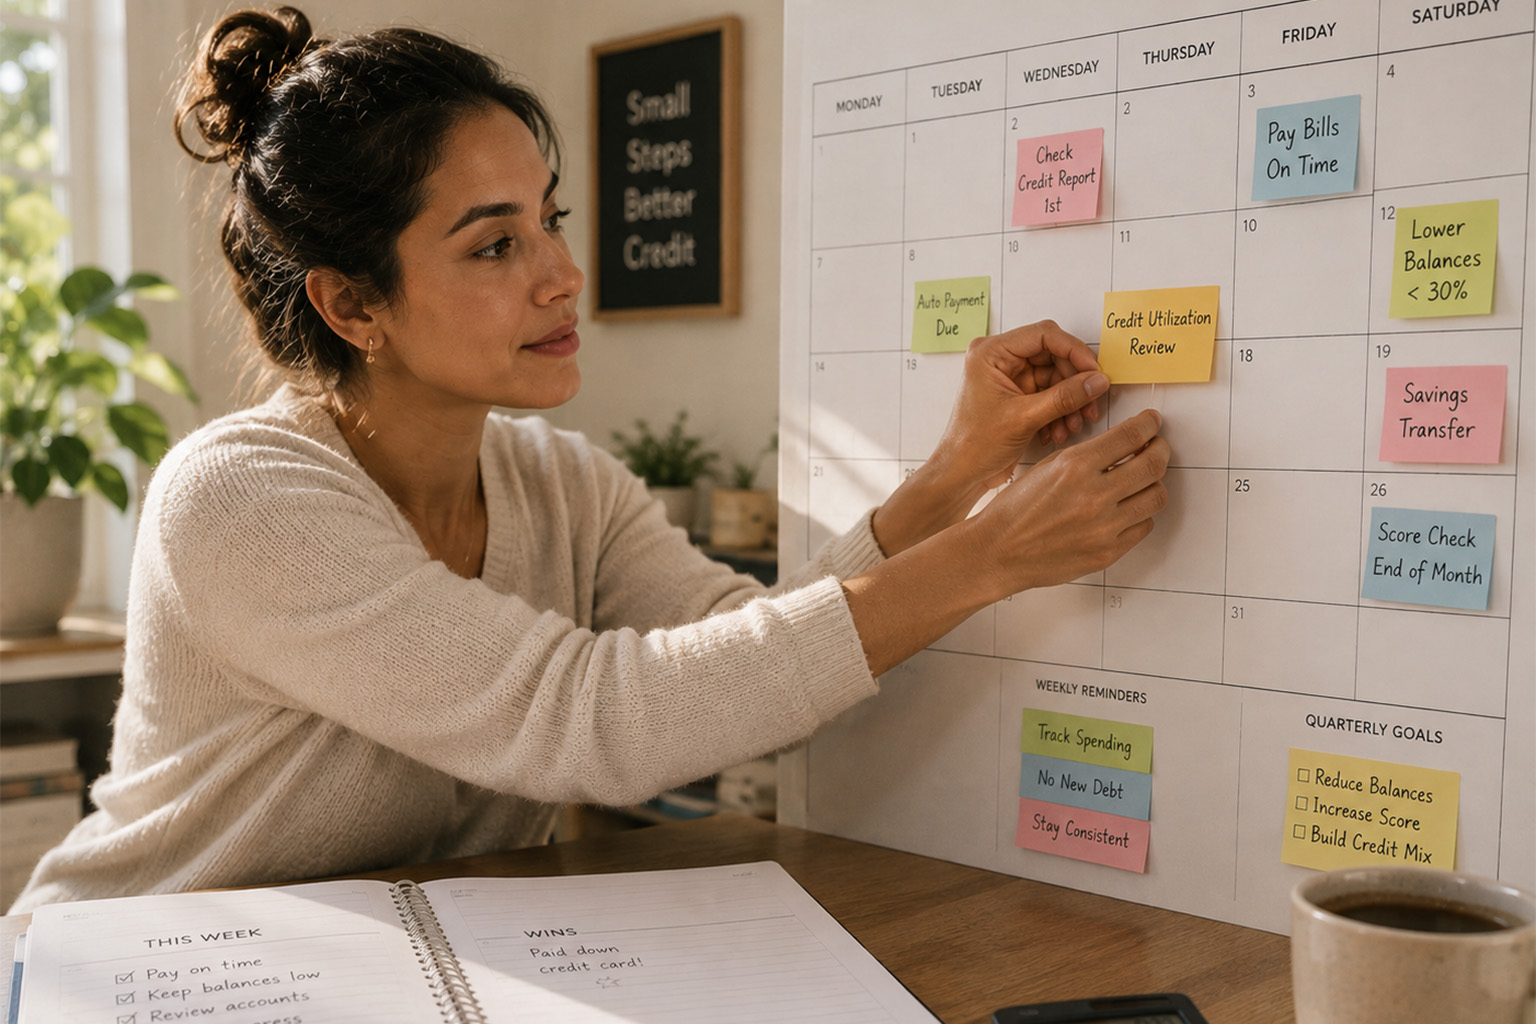
A weekly checklist keeps the most impactful tasks front and center so they don’t pile up into problems. Key weekly items include confirming scheduled payments, reviewing balances on major accounts, and flagging any new or unfamiliar activity. These quick checks protect payment history and limit utilization swings that scoring models penalize. A short, consistent review is often enough to catch issues before they affect your score.
- Confirm upcoming autopay and manual payment amounts.
- Scan recent transactions for unfamiliar charges.
- Note any balances creeping toward high utilization thresholds.
Keeping the checklist concise makes it realistic to maintain and ensures weekly effort yields visible results. It’s a practical foundation for longer-term planning.
Quarterly actions: targeted adjustments and account optimization
Every quarter, step back to assess account mix, outstanding balances, and any soft spots on your credit report. Consider small credit line increases only when you have steady on-time payments and low utilization, and avoid new accounts unless strategically necessary. Use quarterly reviews to dispute inaccuracies, update contact details, and reassess your debt repayment priorities. These periodic optimizations support steady upward movement without introducing volatility.
Quarterly work complements the weekly checklist by addressing structural items that require more time and oversight. Combined, they maintain steady forward progress.
Monitoring and modest adjustments to sustain momentum
Regular monitoring helps you understand what actions produce the most benefit so you can replicate them. Track score changes after significant steps like paying down a specific card or successfully disputing an error. Avoid overreacting to normal score fluctuations; instead, make modest adjustments based on observed outcomes. Consistent, data-informed tweaking keeps the plan efficient and focused.
Small, deliberate changes minimize risk and support continuous improvement over months. Consistency is the most reliable path to stronger credit.
Conclusion
Adopt a routine that balances weekly checks with quarterly optimizations to build reliable credit momentum. Focus on on-time payments, controlled utilization, and correcting errors while making modest, data-driven adjustments. Over time these structured small steps yield steady, sustainable score improvement.