
Introduction
Credit management becomes more practical when you respond to specific events rather than vague resolutions. Financial triggers are moments—like billing cycles, account openings, or large purchases—that signal a targeted action. Treating these signals as checkpoints reduces procrastination and channels effort to what affects your score most. Below are steps to identify triggers and link them to straightforward credit actions.
Identify Your Financial Triggers
Start by listing recurring dates and atypical events that change your credit picture. Examples include statement closing dates, notification of a new account, upcoming large payments, or a planned loan application. Each of these moments creates an opportunity to check utilization, verify reporting, or pause new credit activity. Recognizing them in advance converts occasional scrambles into predictable routines.
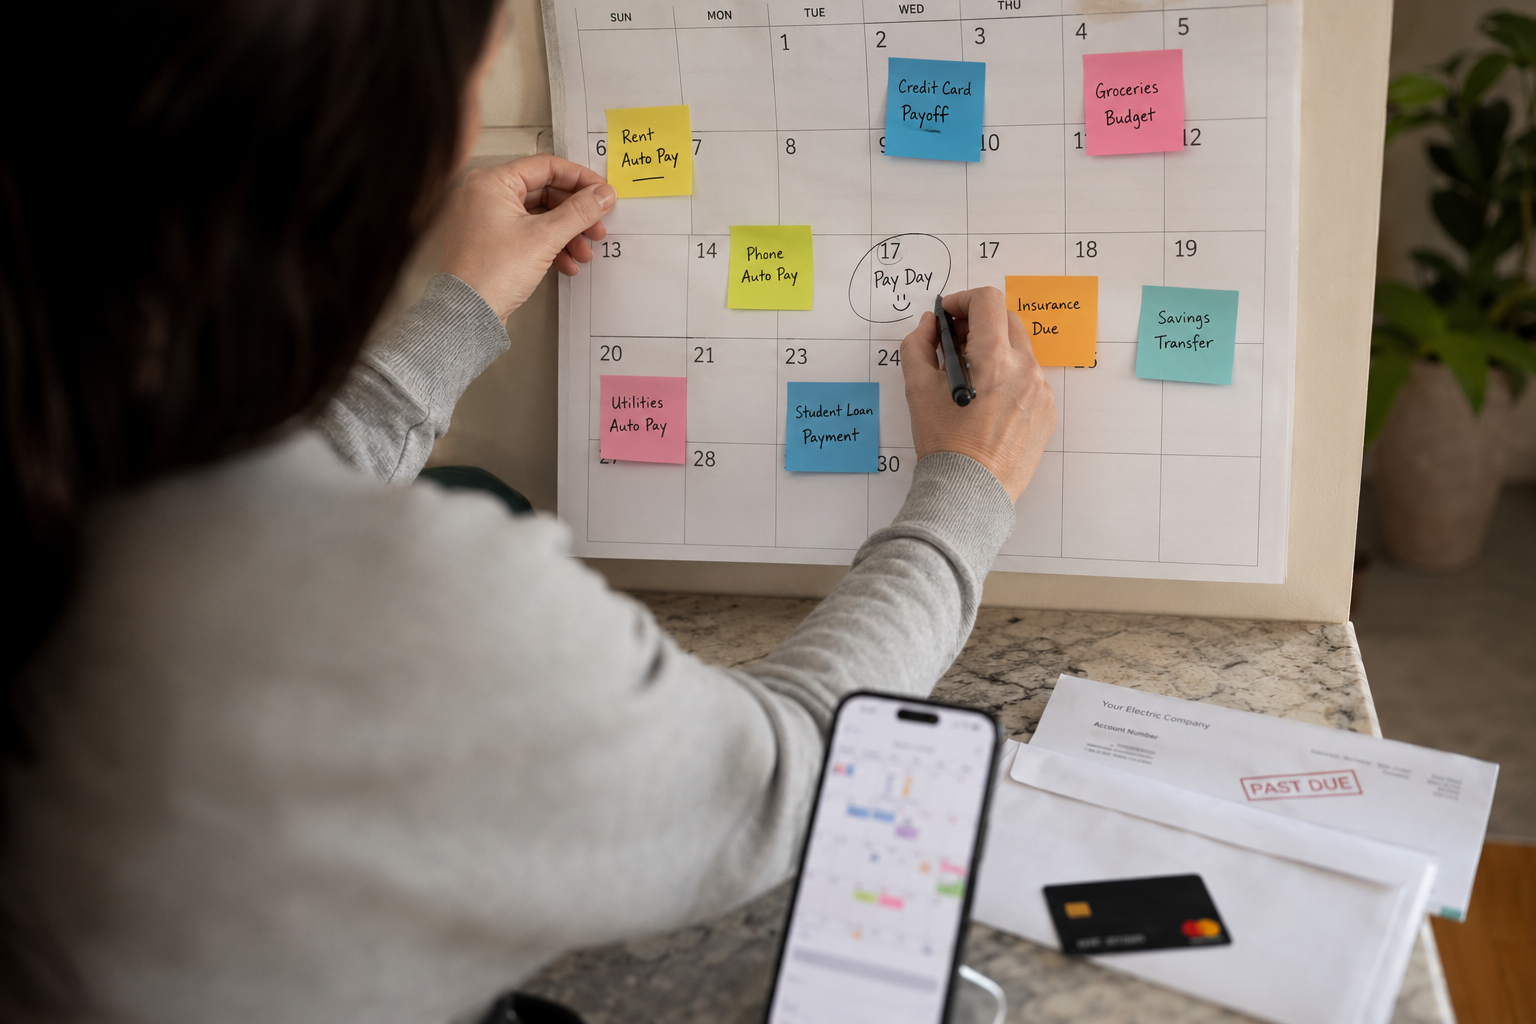
Make the list visible in a calendar or task app so triggers are hard to miss. Over time the list will reveal which events most influence your score and warrant regular attention.
Map Actions to Each Trigger
Once triggers are identified, assign one clear action per trigger that is simple to execute. For a statement closing date, aim to reduce utilization below a target percentage; for a new-account alert, verify account details and watch for unexpected hard inquiries. Before a planned loan application, temporarily minimize balances and avoid opening additional accounts. Small, specific responses produce measurable effects while avoiding overreaction.
Prioritize actions that address the largest score drivers first, such as on-time payment and utilization. This keeps efforts efficient and results observable.
Automate Reviews and Alerts
Automation reduces the mental load of following triggers without eliminating thoughtful review. Set calendar reminders around key dates, enable account alerts for balance thresholds, and use credit monitoring for new accounts or inquiries. Autopay can secure punctual payments, while scheduled manual checks ensure automated systems didn’t miss errors. Combining automation with periodic hands-on reviews strikes a durable balance.
Choose two cadence tiers: a monthly quick check for balances and payments, and a quarterly deeper review of reports and credit mix. That cadence keeps tasks manageable and outcomes trackable.
Tactical Moves That Respect Your Score
When a trigger calls for action, favor low-risk tactics that respect score mechanics. Pay down balances rather than closing accounts, spread necessary spending across cards to avoid spikes, and limit hard inquiries to planned windows. If an error appears after a trigger event, file a prompt dispute and follow up until resolved. Small, consistent moves usually outperform sporadic drastic changes.
Adopt a calm, evidence-based response to each trigger to build momentum without creating volatility. Over months, those steady choices compound into meaningful credit improvement.
Conclusion
Using financial triggers turns abstract credit goals into concrete, repeatable actions that fit your calendar. By mapping simple, prioritized responses to specific events and automating reminders, you maintain control with minimal effort. Consistency around those triggers produces steady improvement and greater credit resilience.