Introduction Insurance can feel overwhelming when budgets are tight and risks vary across daily life. A simple triage approach helps you focus on coverages that restore function quickly after a loss. This article outlines how to rank protections by…
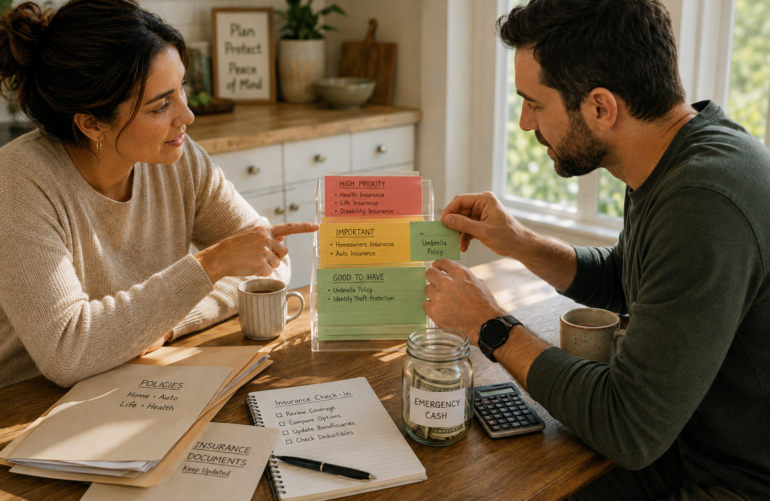

Introduction Insurance can feel overwhelming when budgets are tight and risks vary across daily life. A simple triage approach helps you focus on coverages that restore function quickly after a loss. This article outlines how to rank protections by…
Introduction Insurance works best when it supports quick recovery, not when it creates more friction after a loss. Start by thinking about what must be fixed or replaced immediately to keep your household functioning. Consider cash flow shocks, physical…
Introduction When paydays are unpredictable, small, repeatable habits help prevent stress and missed payments. This short guide focuses on weekly moves you can adopt quickly and keep over time. It highlights simple steps to map money, reduce friction, and…
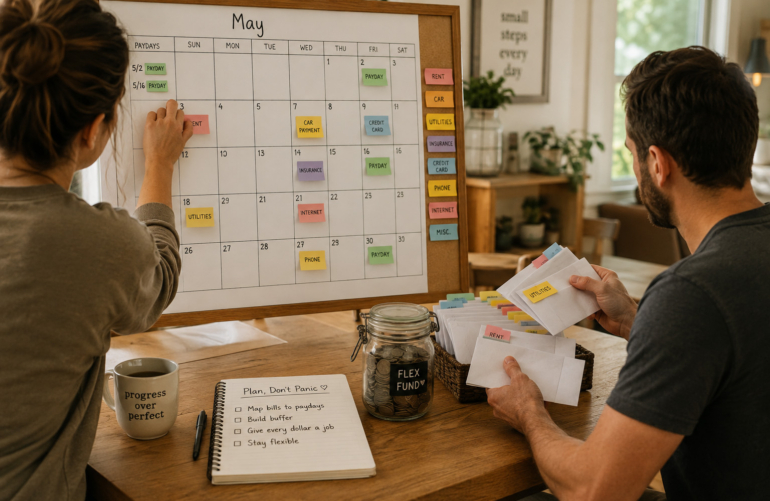
Introduction Unexpected due dates and uneven income are common stressors for everyday finances. A flexible bill calendar helps you match payment timing to cash flow without complex spreadsheets. This approach focuses on sequencing, small buffers, and predictable categories for…
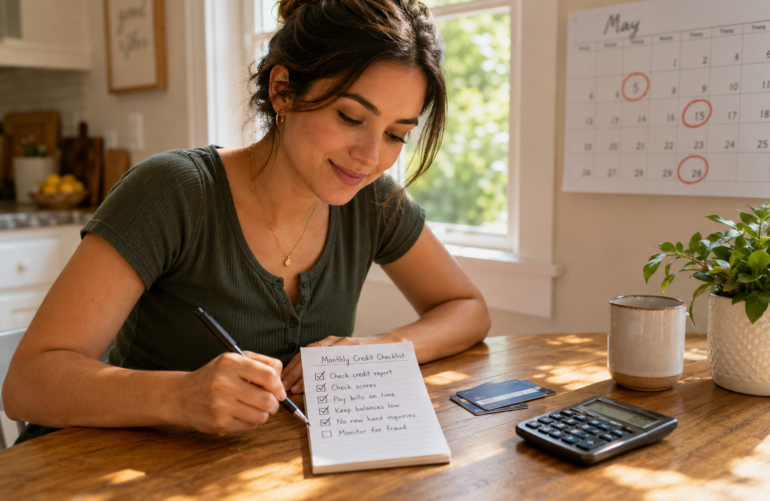
Introduction Keeping credit healthy doesn’t require a complex plan; a few clear workflows deliver more reliable results. By standardizing the small, repeatable actions you take each month—like reconciling balances and confirming scheduled payments—you reduce mistakes and create measurable momentum…
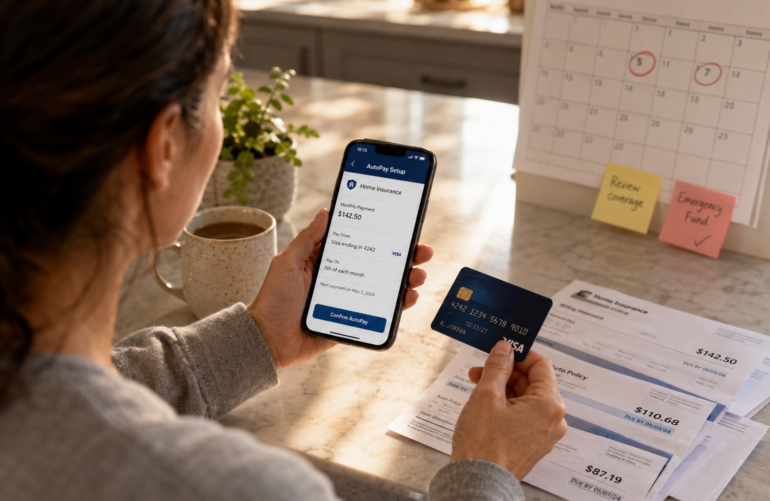
Introduction Improving a credit score rarely happens overnight; it grows through steady, intentional choices. Small adjustments to how you pay, borrow, and monitor accounts can compound into meaningful gains over months. By focusing on a few measurable behaviors you…
Introduction Insurance is a tool to transfer risk, not to prevent every setback. Deciding what to insure means weighing how a loss would affect your cash flow, daily routine, and long-term plans. Some losses are cheap to absorb yourself,…
Introduction Insurance decisions are most effective when they follow a clear framework rather than impulse or fear. This article outlines practical steps to evaluate coverage by impact, cost, and recoverability. The goal is to help households prioritize protections that…
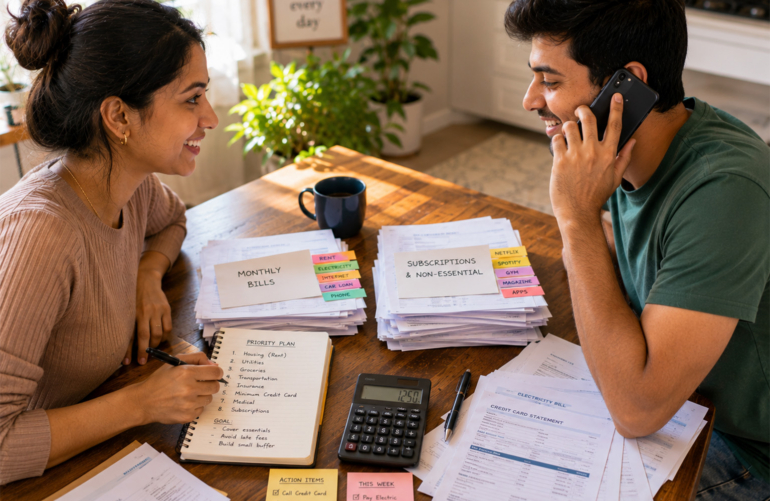
Introduction Facing a tight month can feel overwhelming, but clear steps make the situation manageable. Start by identifying non-negotiable obligations and simple areas where spending can be paused. A calm, ordered approach reduces stress and prevents costly mistakes like…

Introduction When your take-home pay varies from month to month, a short, practical plan can prevent stress and missed obligations. This framework focuses on identifying firm commitments, sequencing spending, and creating small, flexible reserves. It is meant to be…